Penalty-Free Early IRA Distributions for College Education Expenses

Do you have tuition or other college expenses due for yourself, your spouse, or your child? Would you like to use your IRA to pay for these expenses? Would you like to avoid the 10% early withdrawal penalty for accessing your IRA funds before you are age 59 ½? This article outlines how you can avoid the 10% early withdrawal penalty when using your IRA to pay for higher education expenses.

Whether you should actually take a distribution from your IRA to pay for the higher education expenses of your child is another topic. Sadly, too many parents have raided their own retirement savings to pay for their children’s college education expenses. They then reach retirement age with a sliver of what savings or retirement accounts they could’ve otherwise relied on. Everyone’s situation and goals are unique but if you have decided to use IRA funds to help pay for educational expenses here’s how you can avoid the 10% penalty for accessing your own money.

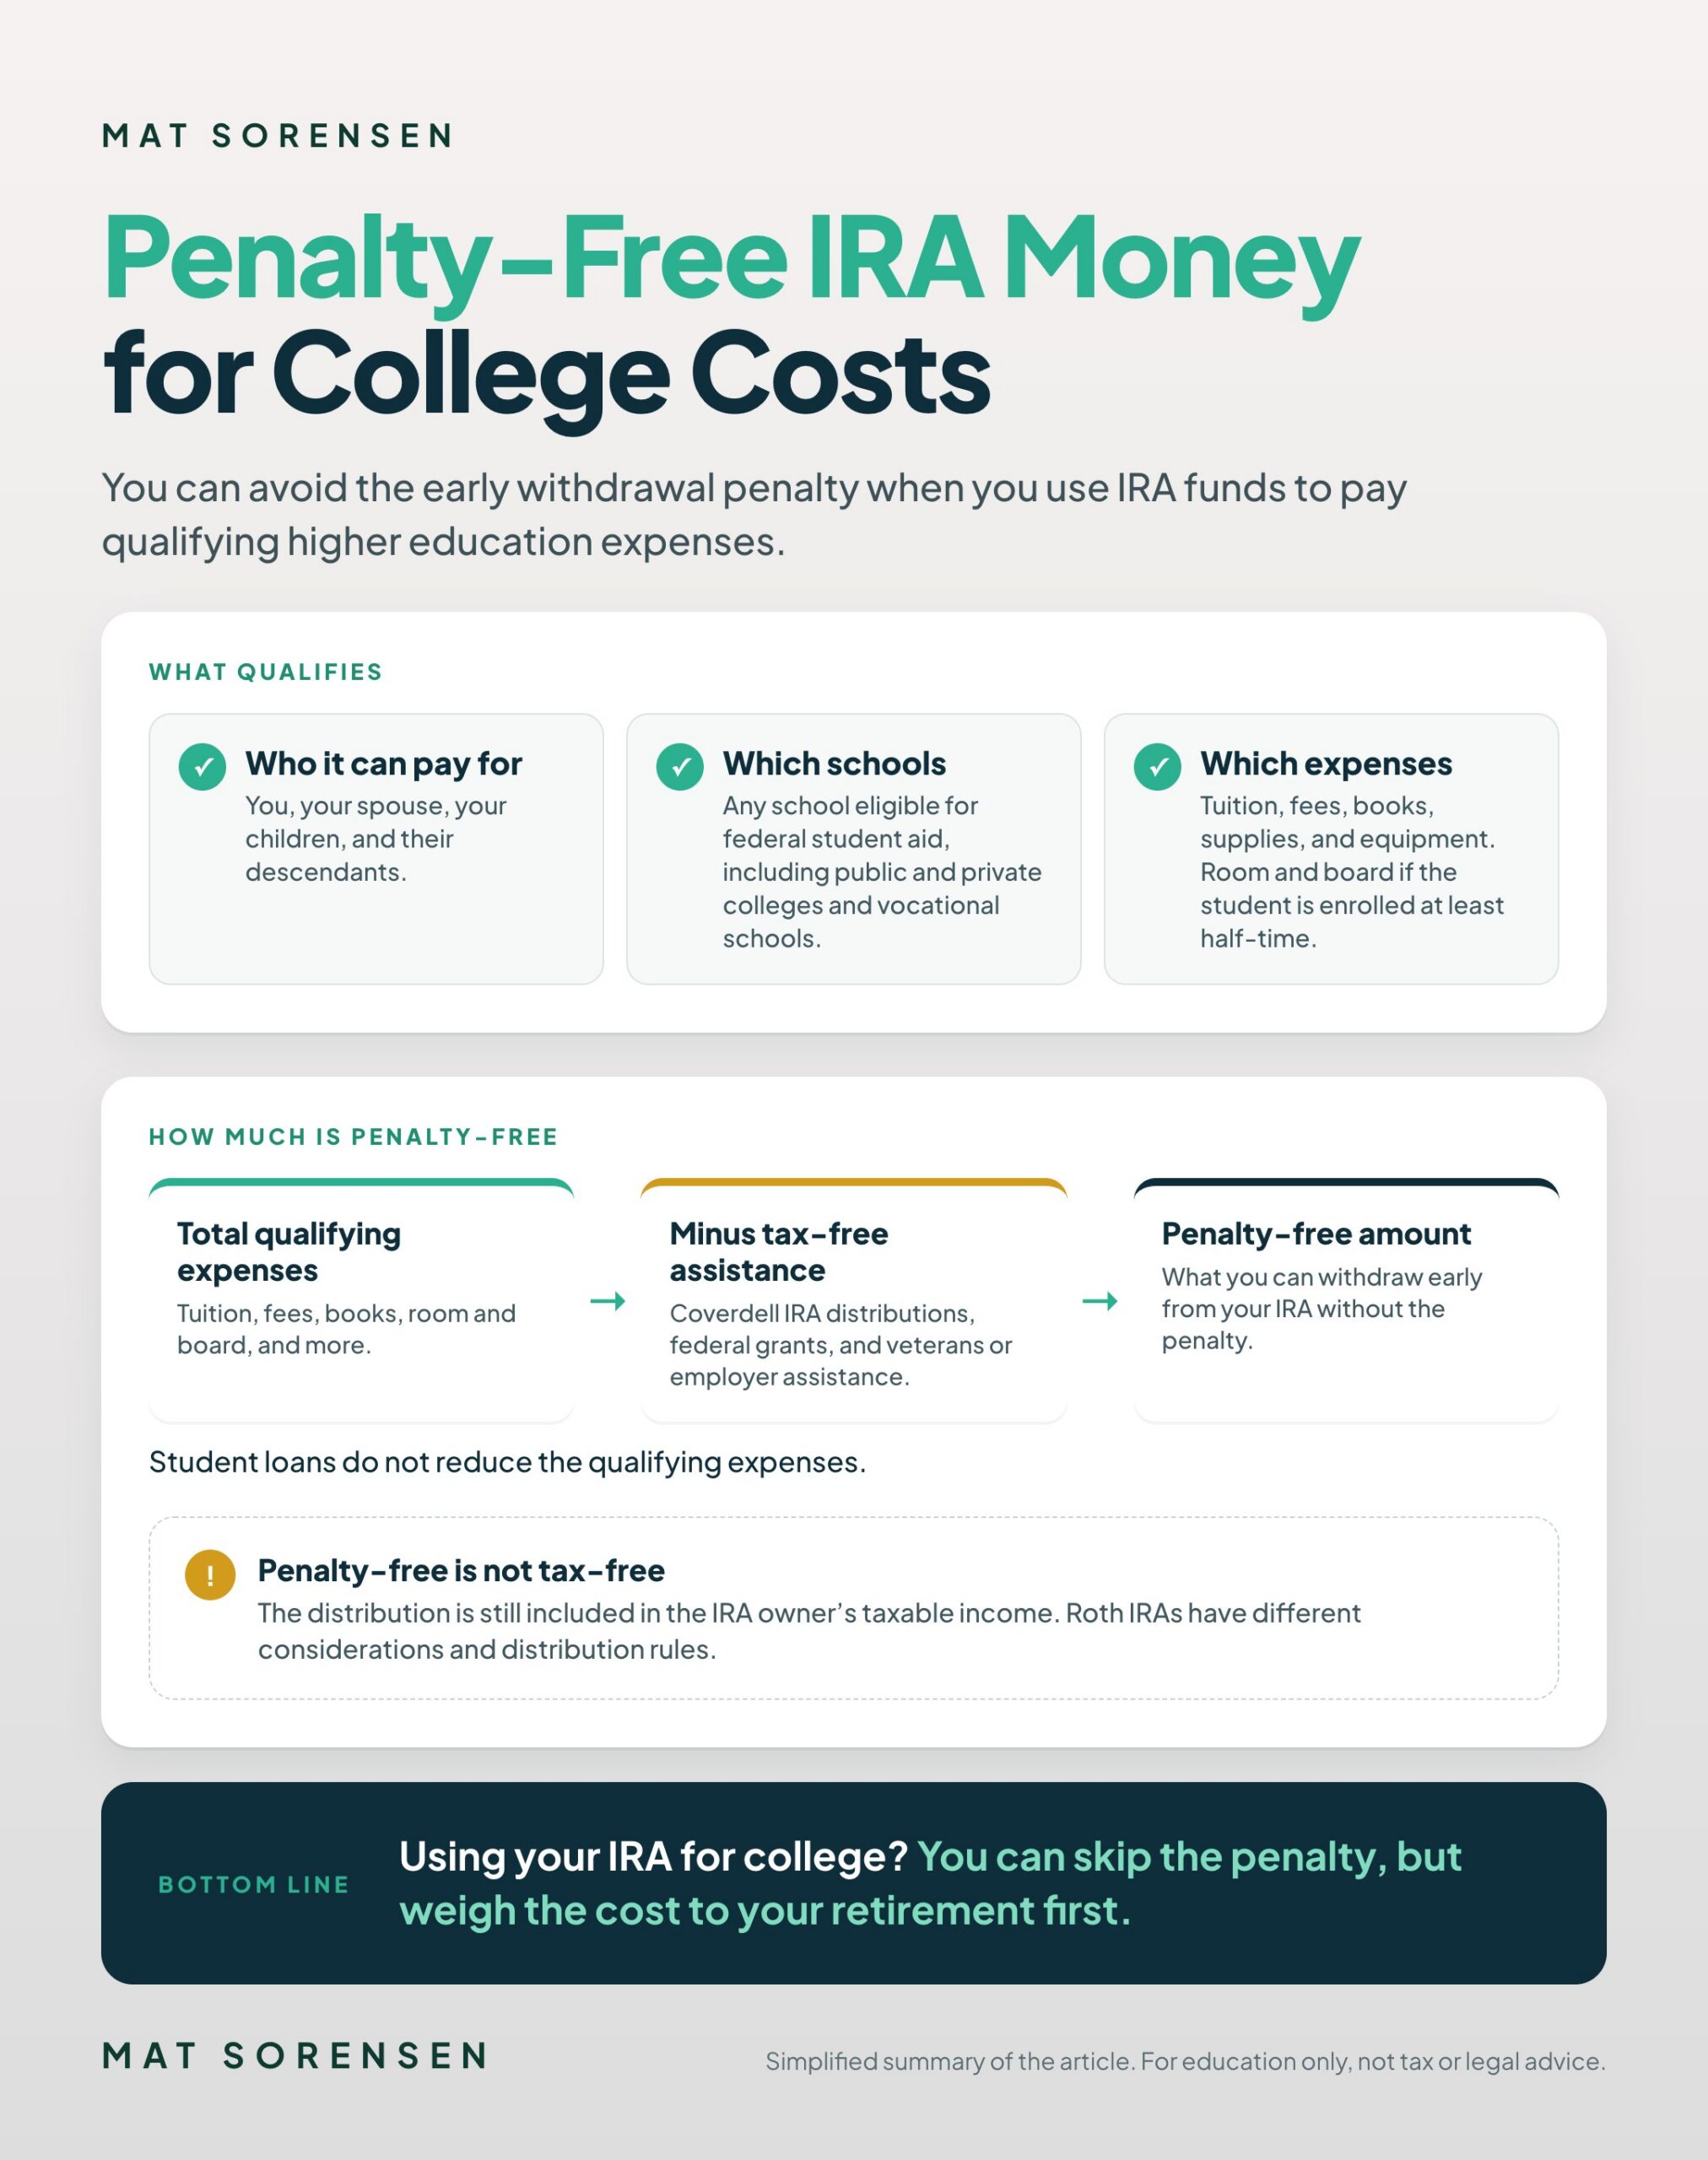
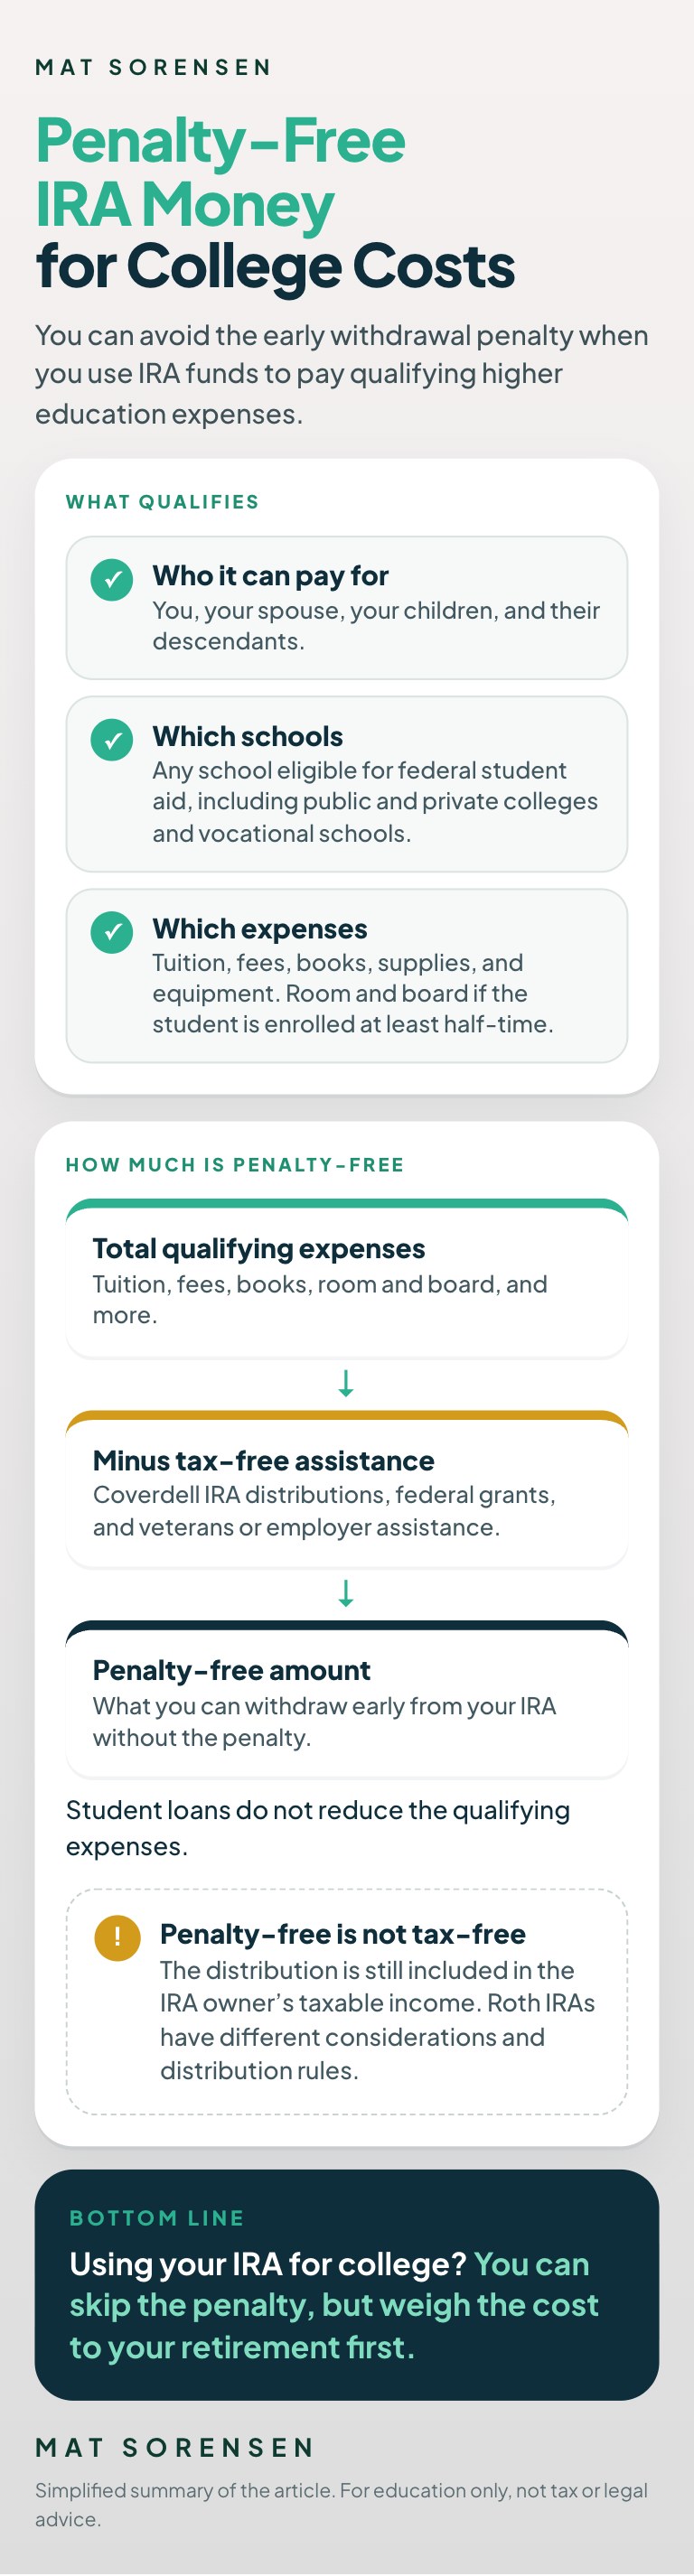
Infographic: who, which schools, and which expenses qualify for penalty-free early IRA distributions for college, and how to figure the penalty-free amount

10% Penalty Exception Rules for Higher Education Expenses

Here’s a quick breakdown on how the 10% withdrawal penalty can be avoided when you use IRA funds to pay for qualifying higher education expenses.

1. Who can the IRA money be used for?

 Your IRA funds may be used for qualifying higher education expenses of the IRA owner, their spouse, children, and their descendants.

2. What schools qualify?

Any school eligible to participate in federal student aid programs qualifies. This would include public and private colleges as well as vocational schools. Any school where you, your spouse, or your child completed a FAFSA application will qualify.

3. What expenses qualify?

There is a broad list of qualifying expenses. These include tuition, fees, books, supplies, and equipment. Also, room and board is included if the student is enrolled at least halftime.

4. How much is exempt?

The amount of your distribution that is exempt from tax is computed in three steps. First, determine the total qualifying expenses (tuition, fees, books, room and board, etc.) Second, reduce the qualifying expenses by any tax-free education expenses. These include Coverdell IRA distributions, federal grants (e.g. Pell grants), and any veterans or employer assistance received. Third, subtract any tax-free education assistance from the total qualifying expenses incurred and this gives you the total qualifying amount that you may take an early withdrawal from your IRA and avoid the 10% penalty.

Example

Here’s a quick example to illustrate these rules: You’re age 53 and have an IRA you’d like to access to help cover your daughter’s education expenses. Your daughter Jane is attending Harrison University, a private college that participates in federal student aid programs.

EXAMPLE

Her expenses for the year are as follows:

Tuition: $22,000
Room and Board: $13,000
Books: $1,000
Supplies: $500
Equipment: $500
Total Qualifying Expenses: $37,000

Jane received the following aid:

Federal Grant: $2,400
Coverdell IRA Payment: $5,000
Federal Student Loan: $10,500 (loans do not reduce the qualifying expenses)
Total Tax-Free Assistance: $7,400
Total Amount Eligible for a Penalty-Free 10% Early Withdrawal: $29,600

You decide to take a $10,000 withdrawal from your IRA. Since the total amount eligible is $29,600, the entire distribution will be penalty-free. Keep in mind that while the $10,000 distribution is penalty-free it is still included into the taxable income of the IRA owner.

$37,000

Total qualifying expenses

$7,400

Total tax-free assistance

$29,600

Eligible for a penalty-free early withdrawal

For more details on the 10% early withdrawal exception for higher education expenses, refer to IRS Publication 970. Also, the above example presumes the IRA owner has a traditional IRA. If the IRA owner has a Roth IRA, there are different considerations and distribution rules.

FREE SELF-DIRECTED IRA GUIDE

Learn how to invest your IRA in real estate, private companies, notes, precious metals, and more.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist
Correcting Your IRA’s RMD Failures and Avoiding the Penalty

If you failed to take required minimum distributions (RMD’s) from your IRA, then you are subject to a 25% penalty (10% if corrected within two years). The penalty is 25% on the amount you should have distributed from your IRA to yourself. It’s a steep penalty for simply failing to pay yourself from your own IRA and it’s something every IRA owner with RMD needs to understand. For my prior article explaining RMD rules for IRAs, please click here.

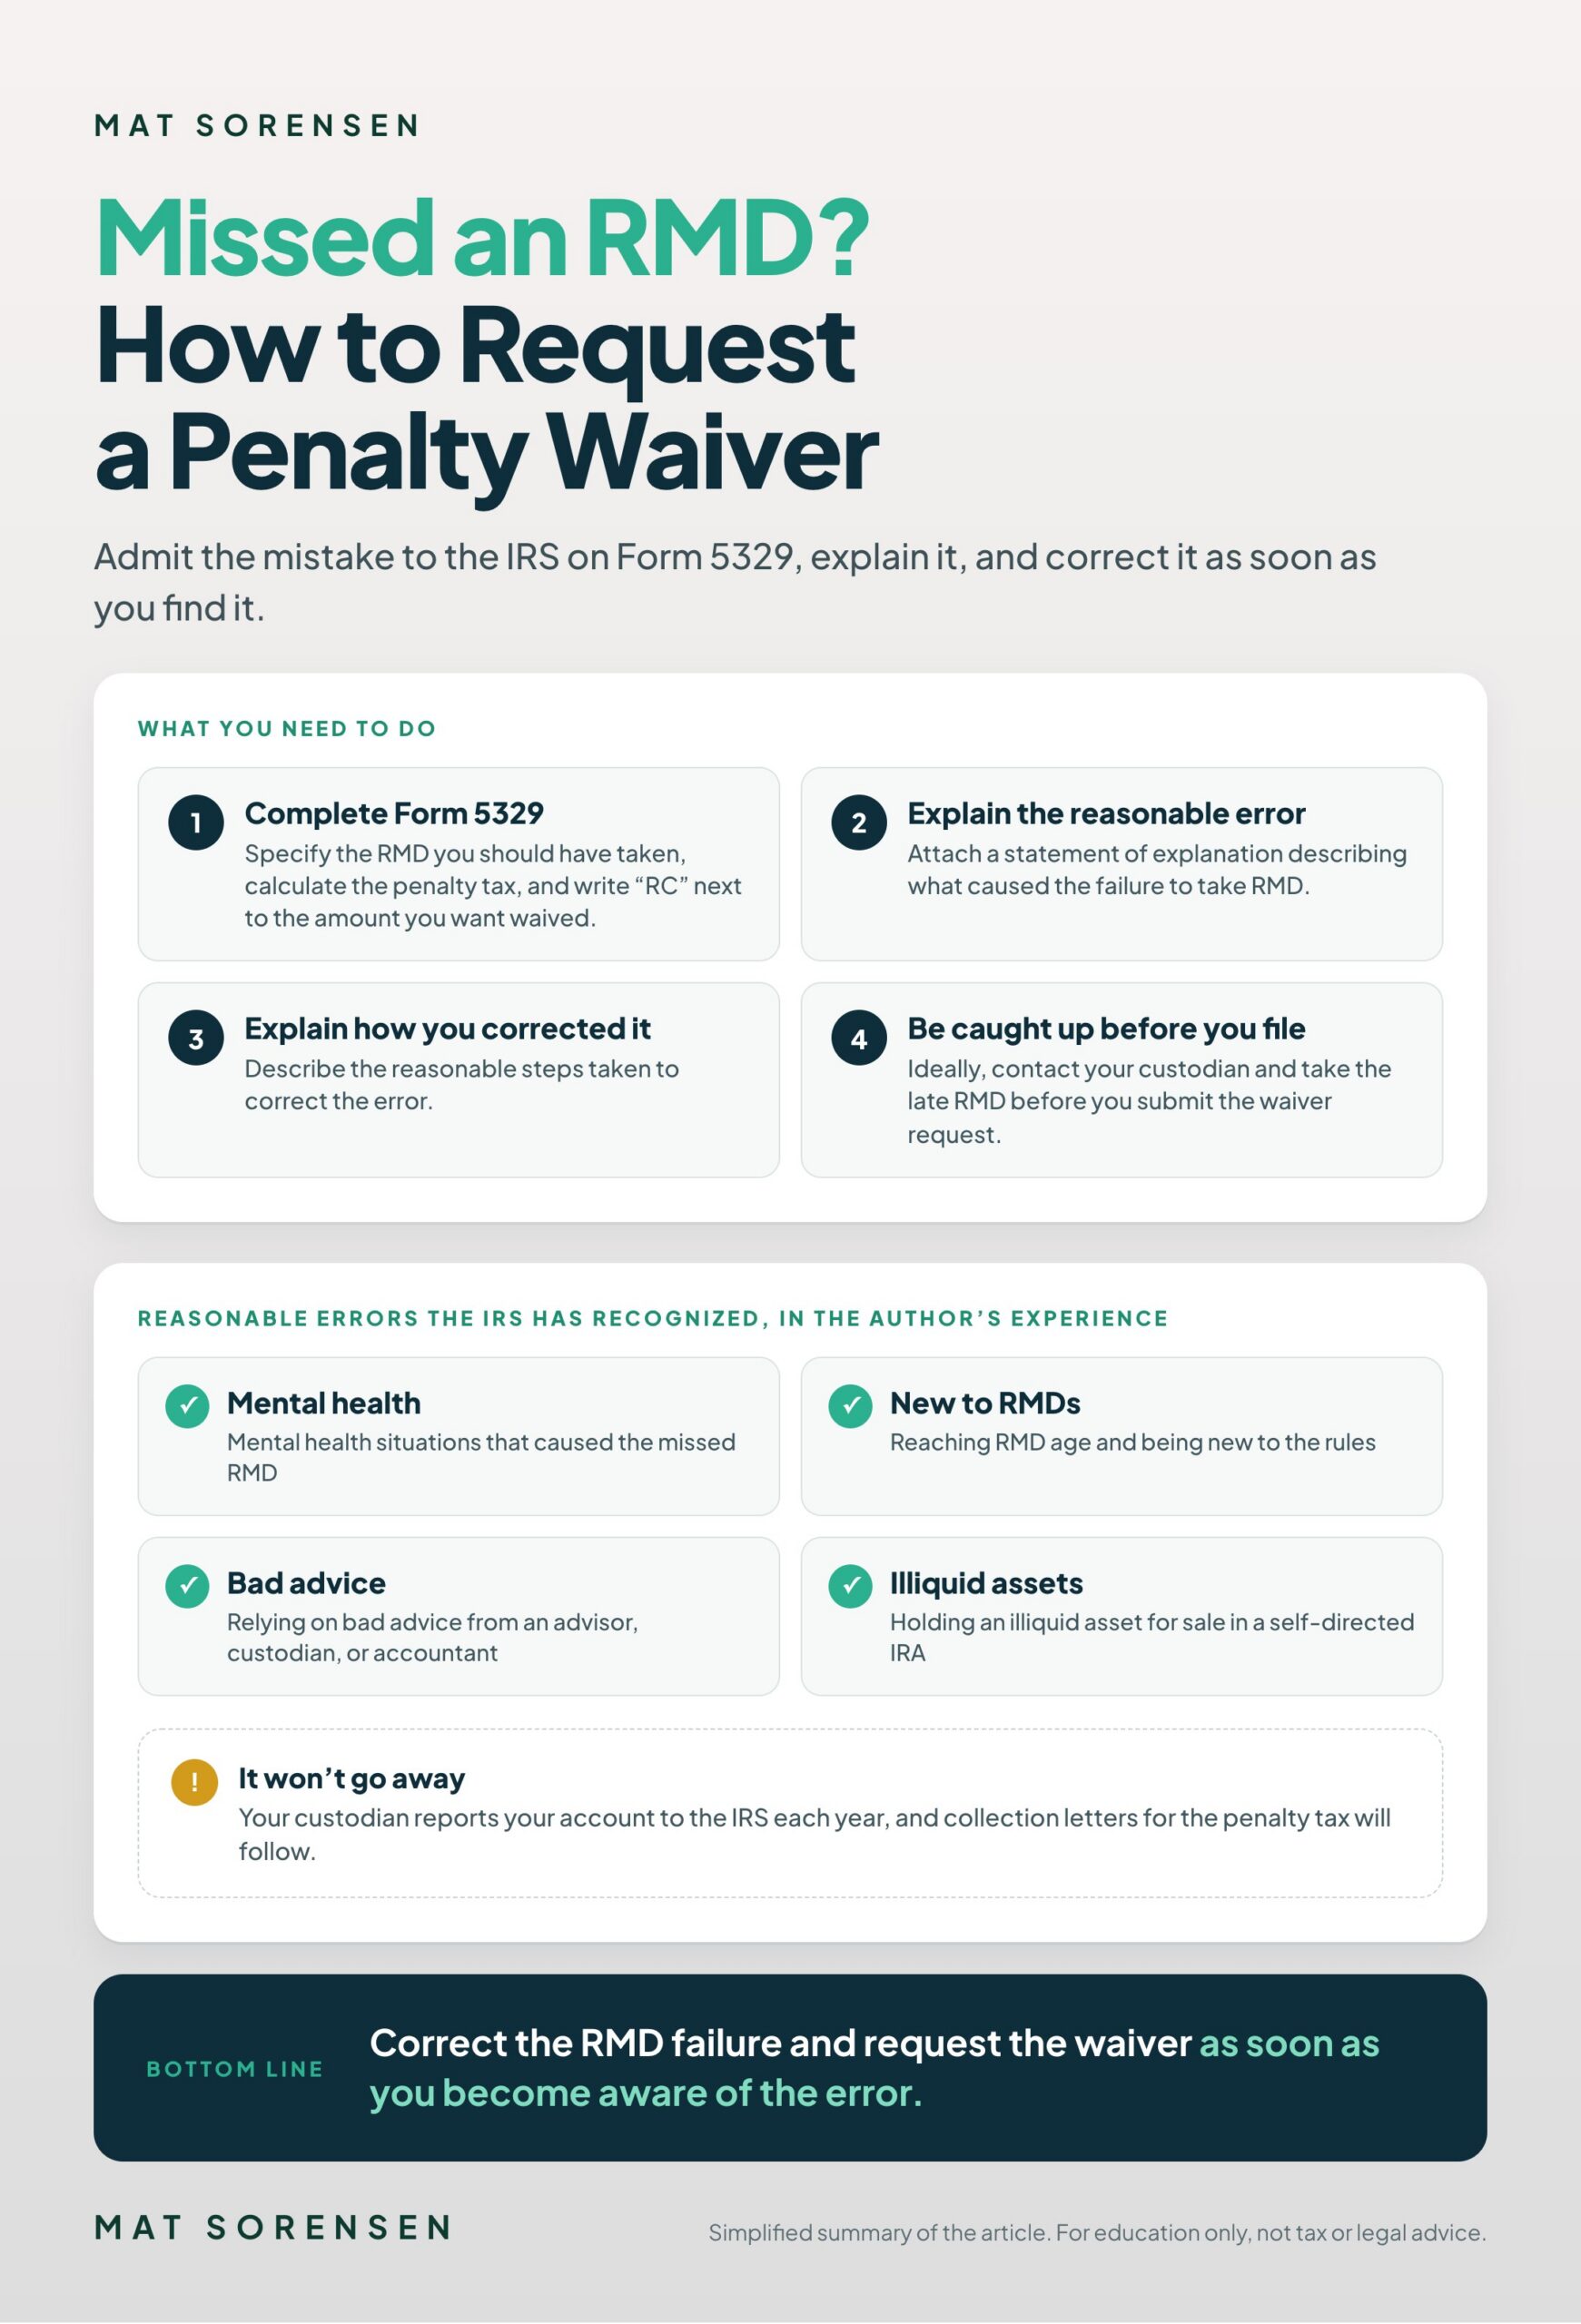
Infographic: the steps to request an IRS waiver of the missed RMD penalty on Form 5329, and examples of reasonable errors

Waiver of the Penalty Tax

UPDATE (NOV 2026)

The penalty for a missed RMD is now 25% of the amount not taken, or 10% if you correct it within two years. It was 50% when this article was written. (Source: IRS)

If you’ve failed to take RMD for your IRA, you have a chance at obtaining a waiver from the penalty but you must admit the mistake to the IRS by filing IRS form 5329. In the instructions to form 5329, the IRS outlines the waiver process to avoid the 50% penalty tax.

What You Need to Do

  1. 1Complete Section IX of Form 5329. You need to specify what you should have taken as RMD  and then you calculate the penalty tax due. You then write the letters “RC” next to the amount you want waived on line 52.
  2. 2Statement of Explanation. Attach a Statement of Explanation outlining two items.
    1. First, explain what was the “reasonable error” that caused a failure to take RMD. The IRS does not provide a definition or acceptable examples of “reasonable error”. See IRC 4974(d)(1). From my own experience and from examples I’ve heard from colleagues, the IRS does recognize reasonable errors and oversights in most situations where there is reason for the error. This would include situations such mental health, to turning 73 and being new to RMD, to relying on bad advice from an advisor, custodian or accountant, to holding an illiquid asset for sale in a self directed IRA.
    2. Second, explain the reasonable steps taken to correct the error. Ideally, by the time you’re filing the exemption request you would’ve already contacted your IRA custodian and would’ve taken the late RMD so that by the time you submit the RMD penalty tax waiver, you would be caught up and would have already remedied the error.  This makes for an easy and clean explanation of what steps you’re going to take as your explanation will be that you already corrected the RMD failure once you realized the error.

WATCH OUT

Keep in mind that RMD failures won’t go away as your IRA custodian will be updating your account each year with the IRS. Eventually, you’ll start getting collection letters from the IRS requesting the penalty tax. Consequently, IRA owners are well advised to correct the RMD failure and request the waiver as soon as they become aware of the error or oversight.

FREE SELF-DIRECTED IRA GUIDE

Learn how to invest your IRA in real estate, private companies, notes, precious metals, and more.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist
Fact and Fiction for IRA RMDs

If you are age 70 1/2 or older and if you have a traditional IRA (or SEP or SIMPLE IRA or 401k), you must take your 2015 required minimum distributions (“RMD”) by December 31, 2015. In short, the RMD rules require you to distribute a portion of funds from your retirement account to yourself personally. These distributed funds are subject to tax and need to be included on your personal tax return.

UPDATE (NOV 2026)

This article was written for the 2015 tax year. Required minimum distributions now start at age 73 (rising to 75 in 2033) under the SECURE 2.0 Act, and the penalty for a missed RMD is now 25% of the amount not taken (10% if corrected within two years). When this article was written, RMDs started at 70½ and the penalty was 50%. (Source: IRS)

EXAMPLE

Let’s take an example to illustrate how the rule works. Sally is 72 and is required to take RMD each year. She has an IRA with $250,000 in it. According to the distribution rules, see IRS Publication 590-B, she will need to distribute $9,765 by the end of the year. This equates to about 4% of her account value. Next year, she will re-calculate this annual distribution amount based on the account’s value and her age.

Once you know how to calculate the RMD, determining the distribution amount is relatively easy. However, the rules of when RMD applies and to what accounts can be confusing. To help sort out the confusion, I have outlined some facts and fiction that every retirement account owner should know about RMDs. First, let’s cover the facts. Then, we’ll tackle the fiction.

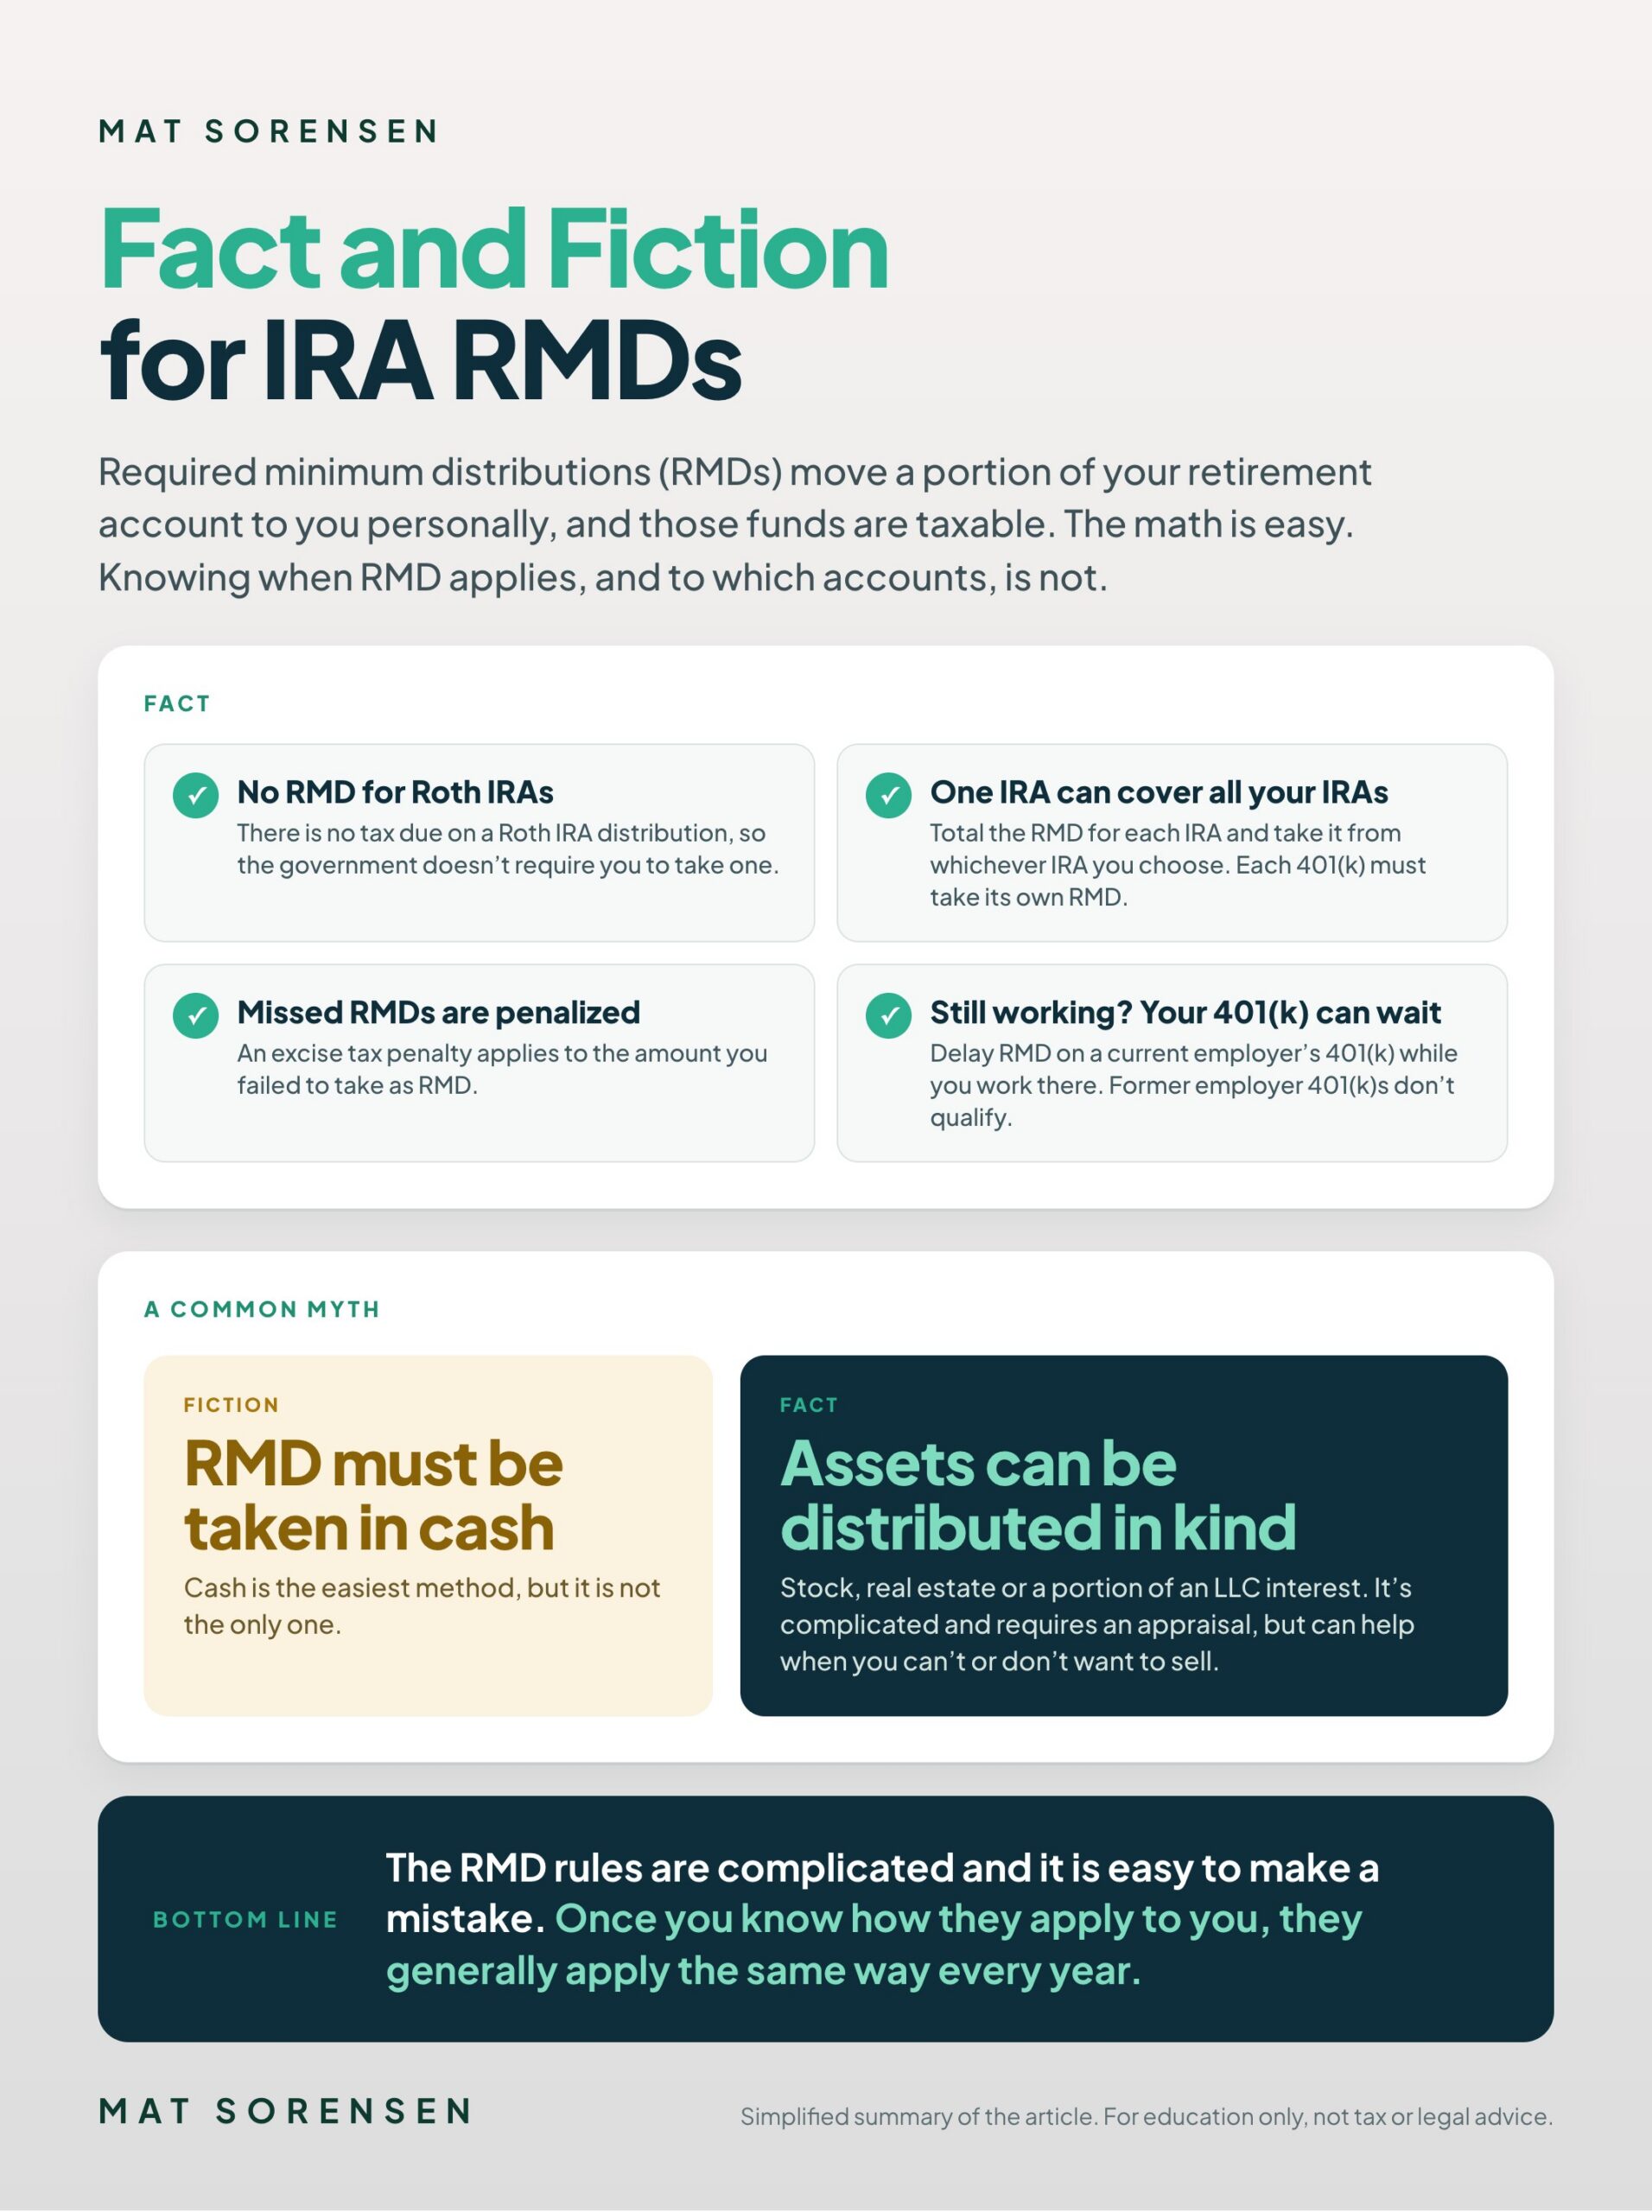
Infographic: facts about IRA required minimum distributions and the myth that RMD must be taken in cash

Fact

  1. 1No RMD for Roth IRAs: Roth IRAs are exempt from RMDs. Even if you are 73 or older, you’re not required to take distributions from your Roth IRA. Why is that? Because there is no tax due when you take a distribution from your Roth IRA. As a result, the government doesn’t really care whether you distribute the funds or not as they don’t receive any tax revenue.
  2. 2RMD Can Be Taken From One IRA to Satisfy RMD for All IRAs: While each account will have an RMD amount to be distributed, you can total those amounts and can satisfy that total amount from one IRA. It is up to you. So, for example, if you have a self directed IRA with a property you don’t want to sell to pay RMD and a brokerage IRA with stock you want to sell to pay RMD, then you can sell the stock in the brokerage IRA and use those funds to satisfy the RMD for both IRAs. You can’t combine RMD though for 401(k) and IRA accounts. Only IRA to IRA. Each 401(k) must take its own RMD.
  3. 350% Excise Tax Penalty: There is a 50% excise tax penalty on the amount you failed to take as RMD. So, for example, if you should’ve taken $10,000 as RMD, but failed to do so, you will be subject to a $5,000 excise tax penalty. Check back next month where I will summarize some measures and relief procedures you can take if you failed to take required RMD.
  4. 4401(k) Account Holder Still Working for 401(k) Employer: If you have a 401(k) with a current employer and if you are still working for that employer, you can delay RMD for as long as you are still working at that employer. This exception doesn’t apply to former employer 401(k) accounts even if you are otherwise employed.

Fiction

UPDATE (NOV 2026)

Since 2024, Roth 401(k) and Roth 403(b) accounts no longer require RMDs during the owner’s lifetime (SECURE 2.0 Act). Item 2 below describes the rules before that change. (Source: IRS)

  1. 1RMD Due by End of Year: You can make 2015 RMD payments until the tax return deadline of April 15, 2016. Wrong! While you can make 2015 IRA contributions up until the tax return deadline of April 15, 2016, RMD distributions must be done by December 31, 2015.
  2. 2Roth 401(k)s are Subject to RMDs: While Roth IRAs and Roth 401(k)s are both tax-free accounts, the RMD rules apply differently. As I stated above, Roth IRAs are exempt from RMD rules. However, Roth 401(k) owners are required to take RMD. The distributions will not be subject to tax but they will start the slow process of removing funds from the tax-free account.
  3. 3RMD Must Be Taken In Cash: False. Required Minimum distributions may be satisfied by taking cash distributions or by taking a distribution of assets in kind. While a cash distribution is the easiest method to take RMD, you may also satisfy RMD by distributing assets in kind. This may be stock or real estate or other assets that you don’t want to sell or that you cannot sell. This doesn’t occur often but some self directed IRA owners will end up holding an asset they don’t want to sell because of current market conditions (e.g. real estate) and they decide to take distributions of portions of the real estate in-kind in order to satisfy RMD. This process is complicated and requires an appraisal of the asset(s) being distributed and partial deed transfers (or partial LLC membership interest transfers, if the IRA owns an LLC and the LLC owns the real estate) from the IRA to the IRA owner. While this isn’t the recommended course to satisfy RMD, it is a potential solution to IRA owners who are holding an asset, who have no other IRA funds to distribute for RMD, and who wish to only take a portion of the asset to satisfy their annual RMD.

The RMD rules are complicated and it is easy to make a mistake. Keep in mind that once you know how the RMD rules apply in your situation it is generally going to apply in the same manner every year thereafter with only some new calculations based on your age and account balances each year thereafter.

Click here for a nice summary of the RMD rules from the IRS.

FREE SELF-DIRECTED IRA GUIDE

Learn how to invest your IRA in real estate, private companies, notes, precious metals, and more.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist