Where Should I Title My Real Estate: An LLC, a Trust, or Personally?

Real estate may be owned in your personal name, in a business name, or in a trust. You may have heard of revocable living trusts, corporations, LLCs, series LLCs, or limited partnerships. Here’s a quick guide to where you should own different types of properties.

Infographic: where to own a personal residence, rental property, land or second home, and where properties should not be held

1. Personal Residence

Your home should be owned in your revocable living trust. A living trust is an excellent choice to own your personal residence as the property can pass under the terms of your trust upon your death and your heirs won’t need to go to probate court to transfer ownership. If your residence is owned in your personal name it can only pass to your children/heirs after you’ve gone to probate court which requires far more legal fees and time than setting up a  trust now. For homes with significant equity you may want to consider a domestic asset protection trust which can protect the equity in the home from personal creditors.

2. Rental Property

Your rental property should be owned in an LLC. Rental properties generate income and wealth but they can also create liabilities. If a rental property is owned in your personal name everything that happens on the home creates personal liability to you and a plaintiff can go after all of your personal assets, income, and wages. On the other hand, if a rental property is owned in an LLC the plaintiff will be required to sue the LLC and can’t go after the LLC owner personally. In certain states where you have lots of properties you may want to consider a series LLC which provides liability protection in the LLC between multiple properties such that if something happens to one property in the series LLC it doesn’t affect the other properties in the series LLC.

An LLC owned by one person isn’t too difficult to manage and generally doesn’t require a separate LLC tax return. Instead, you report the property and its profit or loss on your personal return, the same way you would if you owned it in your own name. If you and your spouse own the LLC together, it generally files a partnership return unless you live in a community property state, where you may be able to treat it like a single-member LLC. In most instances, limited partnerships should not be used to hold rental properties as your tax losses and write offs are restricted when you own them in a limited partnership.

3. Land or Second Home

Your land or second home should be owned in your revocable living trust. Again, this helps keep your assets coordinated with your estate plans and outside of probate court. For land or second homes with significant equity you may want to consider a limited partnership or domestic asset protection trust which can protect the property from the owner’s personal liabilities. Generally, an LLC is not used unless the property itself creates liability.

EXAMPLE

For example, if you rent your second home or cabin you may want an LLC for liability protection but most second homes or parcels of land do not create liability  and therefore do not need an LLC.

4. Where Should Properties Never Be Held

Except for short-term real estate holds (under one year) properties should not be owned in an S corporation and should never be held in a C corporation. Additionally, we rarely recommend clients use land trusts to own property for asset protection purposes as land trusts provide little actual asset protection beyond making the owner of the property difficult to determine at the county records.

There are lots of options and many nuances to how you should own your real estate. For a more detailed and specific analysis for your properties please contact the law firm for an estate and asset protection plan that fits your needs. We can also assist with deed transfers to get your properties into the right place.

When is a Business Partner a Disqualified Person to My Self-Directed IRA?

Most self directed IRA owners know that their self directed IRA cannot conduct transactions with themselves or certain family members (e.g. spouse, kids, parents, etc.). Most self directed IRA owners also know that their self directed IRA cannot do business with a company they own or that their disqualified family members own 50% or more of. However, one of the most confusing areas of the prohibited transaction rules are the prohibited transaction rules which apply to business partners or officers, directors, and/or highly compensated employees of companies the IRA owner or family members are personally involved in. For example, what if I own a business with a partner? Can my IRA enter into a transaction with that business partner if we aren’t family? Well, it depends.

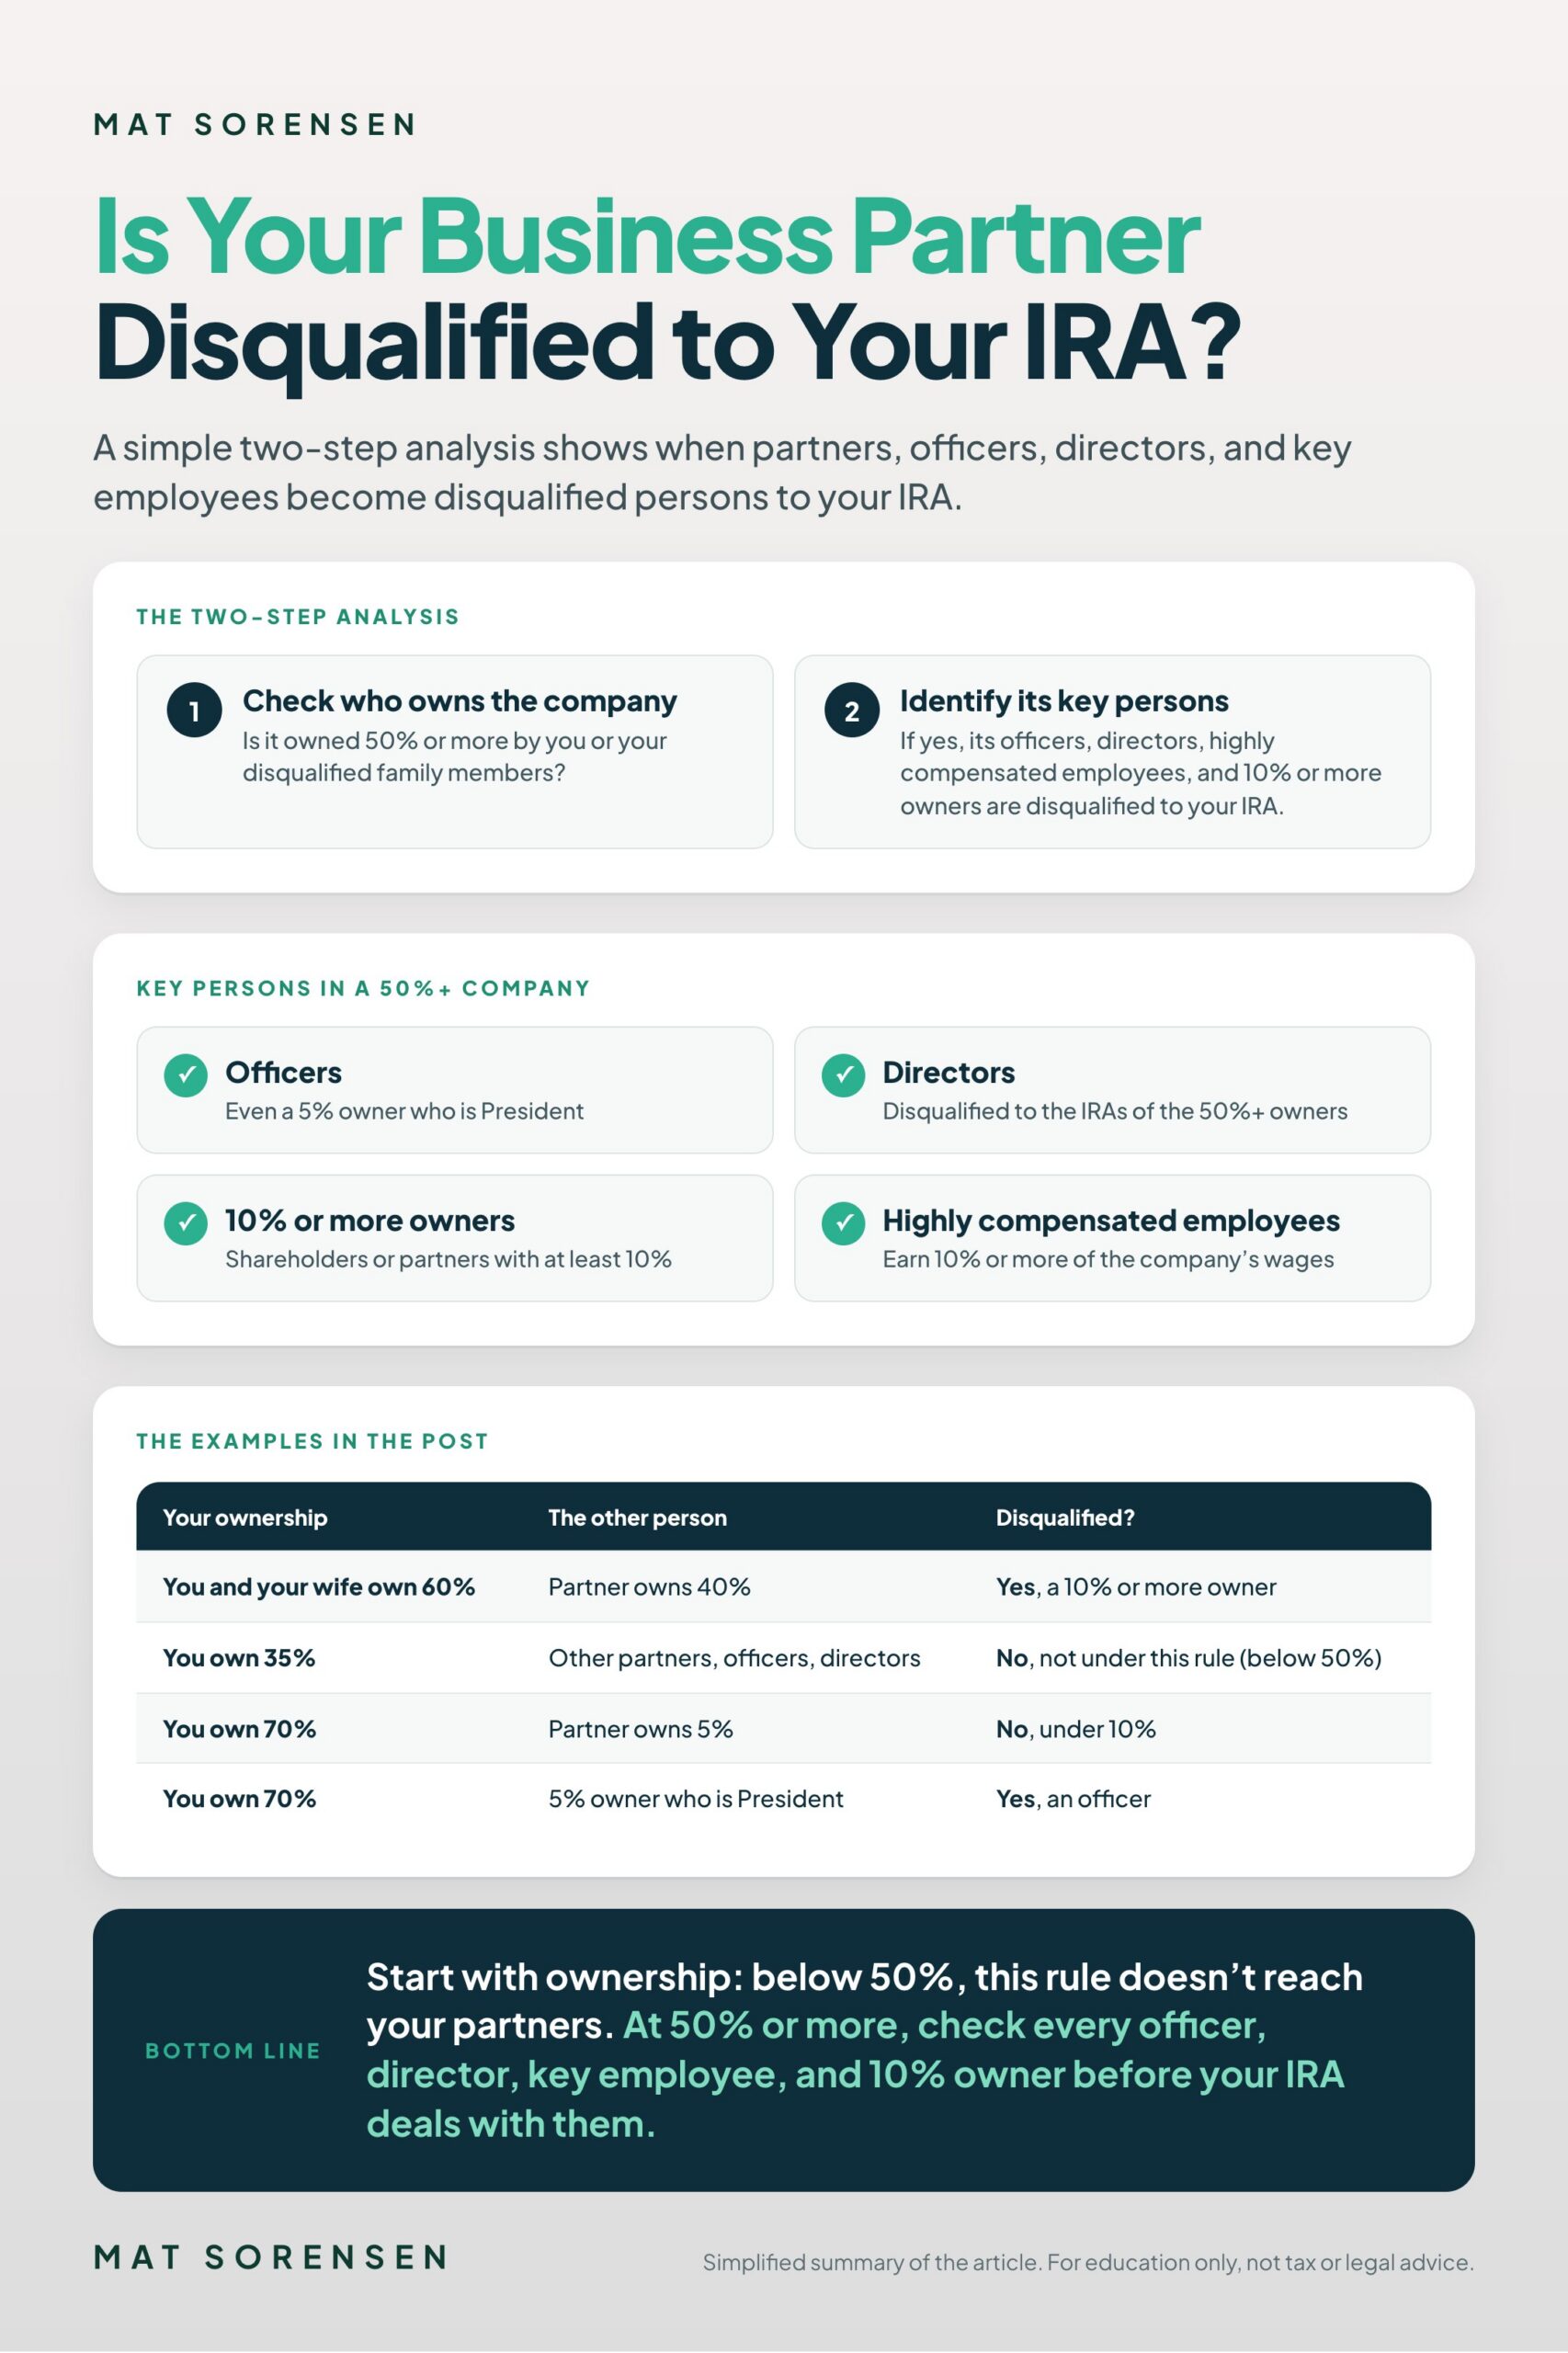
Infographic: the two-step analysis for when a business partner, officer, director, or key employee is a disqualified person to your IRA

Disqualified Person Analysis

To analyze the rules you first need to determine whether the company in which the business partner (or officer, or director) is involved in is a company that is owned 50% or more by the IRA owner or their disqualified family members. IRC 4975 (e)(2)(E),(H), (I). So, for example, if my wife and I owned 60% of the business and our partner owned 40% of the business, then this company would be owned 50% or more by disqualified persons.

Once we know that the company is owned 50% or more by disqualified persons, we need to identify all of the officers, directors, highly compensated employees, and 10% or more owners of that company. In sum, all of these persons are disqualified to the IRAs of the 50% or more owners. In the example above, since my business partner owned 40% of the company, he is a 10% or more owner and as a result he is a disqualified person to my IRA (since my wife and I own 50% or more of the company).

EXAMPLE

Let’s look at another example. Say that I am a 35% owner of a business with a few other partners who are not disqualified family members to me.  Since I do not own 50% or more of this company, it doesn’t matter who the other partners, officers, or directors, are, as they are not disqualified to my IRA as part of this rule since my ownership (and that of my disqualified family members) is below 50%.

EXAMPLE

As a final example, let’s say that I own 70% of a company and that I have a partner who owns 5%. Under the rule, my partner or fellow shareholder does not have 10% or greater ownership and as a result they are not disqualified to my IRA. However, if that 5% owner was the President of my company then they would be a disqualified person.

These rules can be tough to understand when you read the code, but if you take the two step analysis you can easily determine what partners, officers, directors, or highly compensated employees are disqualified to your IRA.

Here’s also a quick summary of the rule from my book where I took the text of the tax code and put it into plain language.

Key Persons in Company Owned 50% or More by Disqualified Persons

An officer, director, or 10% or more shareholder, or highly compensated employee (earns 10% or more of the company’s wages) of a company owned by the IRA owner or other disqualified persons. IRC § 4975 (e)(2)(H).

Before investing with someone who is an officer, director, highly compensated employee, or a shareholder/owner in a company you are involved in, please consult these rules and where you are unclear, seek the advice of competent counsel.

THE SELF-DIRECTED IRA HANDBOOK

Mat’s best-selling guide to the rules: prohibited transactions, UBIT, IRA/LLCs, and the mistakes to avoid.

Get the Free Handbook

Prefer to talk it through? Book a call with a Directed IRA specialist

Who is Prohibited to My Self-Directed IRA?

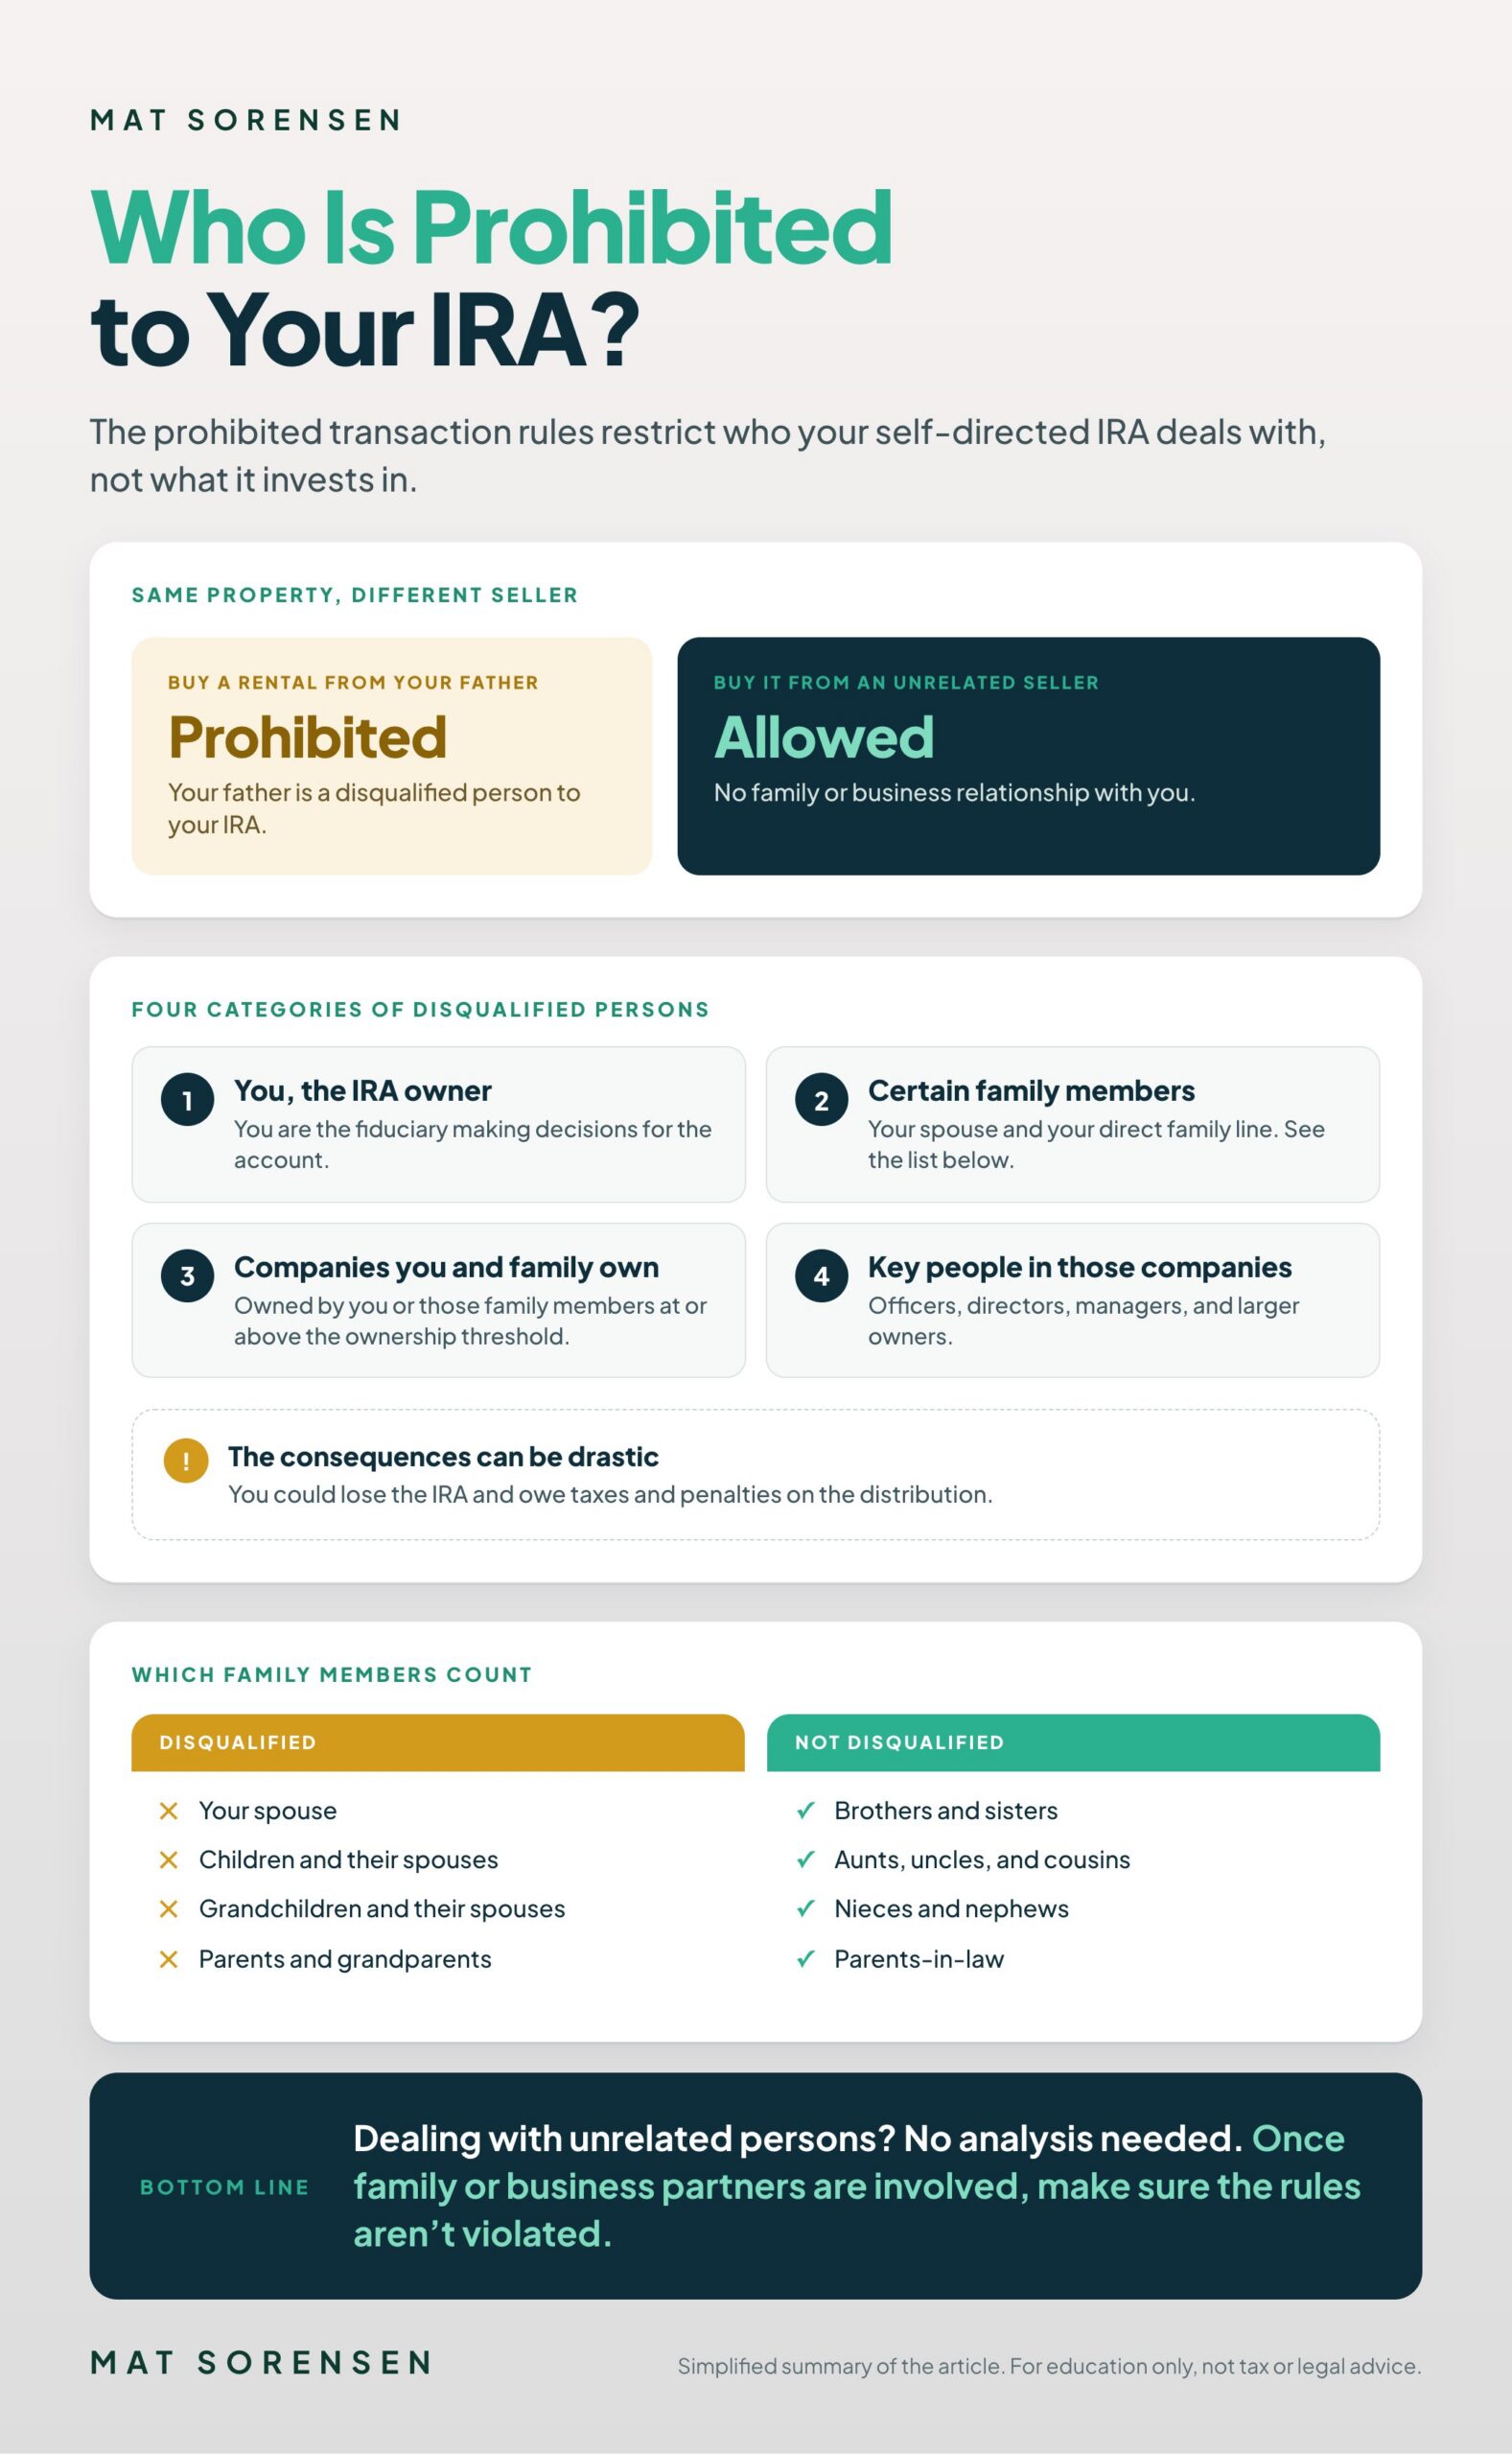
The prohibited transaction rules applicable to self directed IRAs prohibit not what your IRA can invest into but WHO your IRA may engage in a transaction with. For example, the prohibited transaction rules restrict my IRA from buying a rental property from my father. This is not because rental properties are prohibited to my IRA but because my father is prohibited by law from transaction with my IRA. My self directed IRA could buy a rental property from a third party seller whom I have no family or other business relationship with since there is nothing wrong in buying the rental property the question is just who am I buying it from.  Congress decided to restrict investments with certain persons who could potentially collude with the IRA owner to unfairly avoid taxes. As a result, transactions with certain family members and business partners of an IRA owner are prohibited.  The consequence for engaging in a prohibited transaction can be drastic (e.g. no longer have an IRA, penalties and taxes on distribution) so IRA owners must avoid them in all situations.

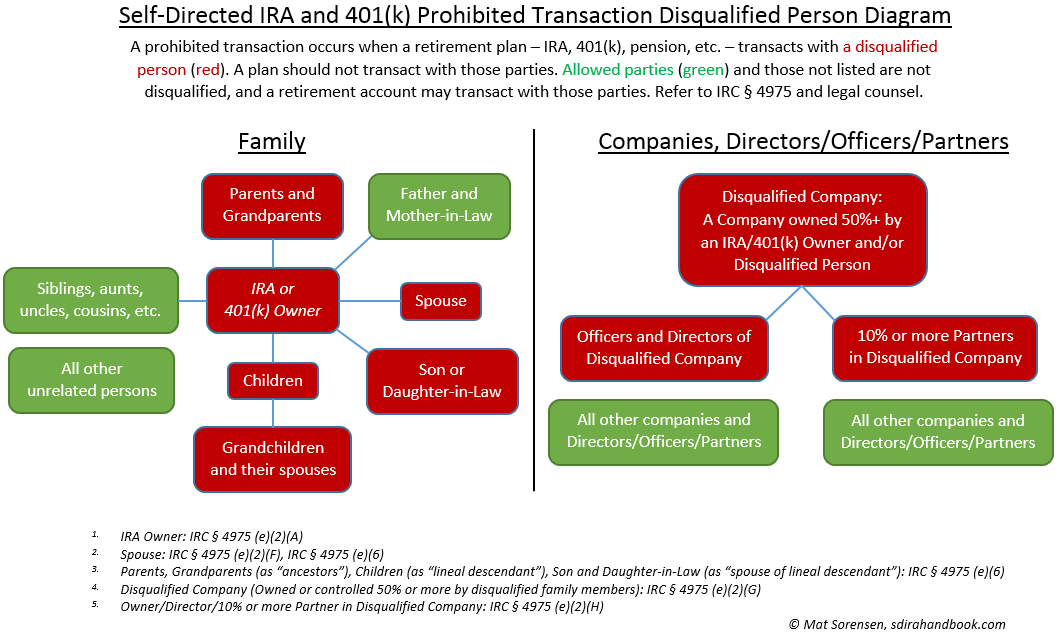
Infographic: who is prohibited to your self-directed IRA. The four categories of disqualified persons, which family members are and are not disqualified, and why buying from your father is prohibited but buying from an unrelated seller is allowed

The prohibited transaction rules therefore provide the greatest restriction on using self directed IRA funds and must be understood by self directed IRA investors. These rules are found in IRC 4975 and state that a prohibited transaction occurs when an IRA engages in a transaction (e.g. buy, sell) with a disqualified person. The question immediately arises, who is a disqualified person to my IRA?

Categories of Persons Disqualified to Your SDIRA

There are essentially four categories of disqualified persons to your IRA and they are as follows.

  1. 1IRA Owner. The IRA owner is disqualified to his/her own IRA as the fiduciary making decisions for the account. IRC 4975(e)(2)(A), Harris v. Commissioner, 76 T.C.M. 748 (U.S. Tax Ct. 1994).
  2. 2Certain Family Members. Disqualified family members include the IRA owner’s spouse, children, spouses of children, grandchildren and their spouses, and the IRA owner’s parents and grandparents. Family members who are NOT disqualified persons are siblings (e.g. brothers and sisters), aunts and uncles, cousins, nieces and nephews, and parent in-laws (e.g. spouses parents). IRC 4975 (e)(2)(F), IRC 4975 (e)(6).
  3. 3Company Owned 50% or More by IRA Owner or Certain Family Members. Any Company that is owned 50% or more by the IRA Owner or Certain Family Members outlined above are disqualified to the IRA. For example, an LLC owned 30% by the IRA owner, 30% by the IRA owner’s spouse, and 40% by an un-related partner is a disqualified company to the IRA (owned 50% or more by disqualified persons) and any transaction between the IRA and the company would be a prohibited transaction.  IRC 4975 (e)(2)(G).
  4. 4Key Persons in Company Owned 50% or More by IRA Owner or Certain Family Members. Any person who is a 10% or more owner of a company owned 50% or more by disqualified persons (e.g. number 3 above) or any person who is an officer, director, or manager of a disqualified company (owned 50% or more by disqualified persons) is also disqualified. For example, if my wife and I own 60% of a company and if Julie is an officer of that company then Julie is a disqualified person to my IRA. Additionally, if Julie was a 10% or more owner of the company she would also be prohibited to my IRA.

When you are dealing with unrelated persons (not related as family or as business partners) the prohibited transaction rules do not need to be analyzed but once family members or business partners are involved in any part of the transaction, the IRA owner must ensure that the prohibited transaction rules are not being violated.

THE SELF-DIRECTED IRA HANDBOOK

Mat’s best-selling guide to the rules: prohibited transactions, UBIT, IRA/LLCs, and the mistakes to avoid.

Get the Free Handbook

Prefer to talk it through? Book a call with a Directed IRA specialist