Stuck With a 401K Loan and Leaving Your Job

Have you taken a loan from your employer 401(k) plan and plan on leaving? Unfortunately, most company plans will require you to repay the loan within 60 days, or they will distribute the amount outstanding on the loan from your 401(k) account. It’s one of the ways they try to keep their employees from leaving. “Don’t leave or we’ll distribute your 401(k) loan that you took from your money in your 401(k) account.”
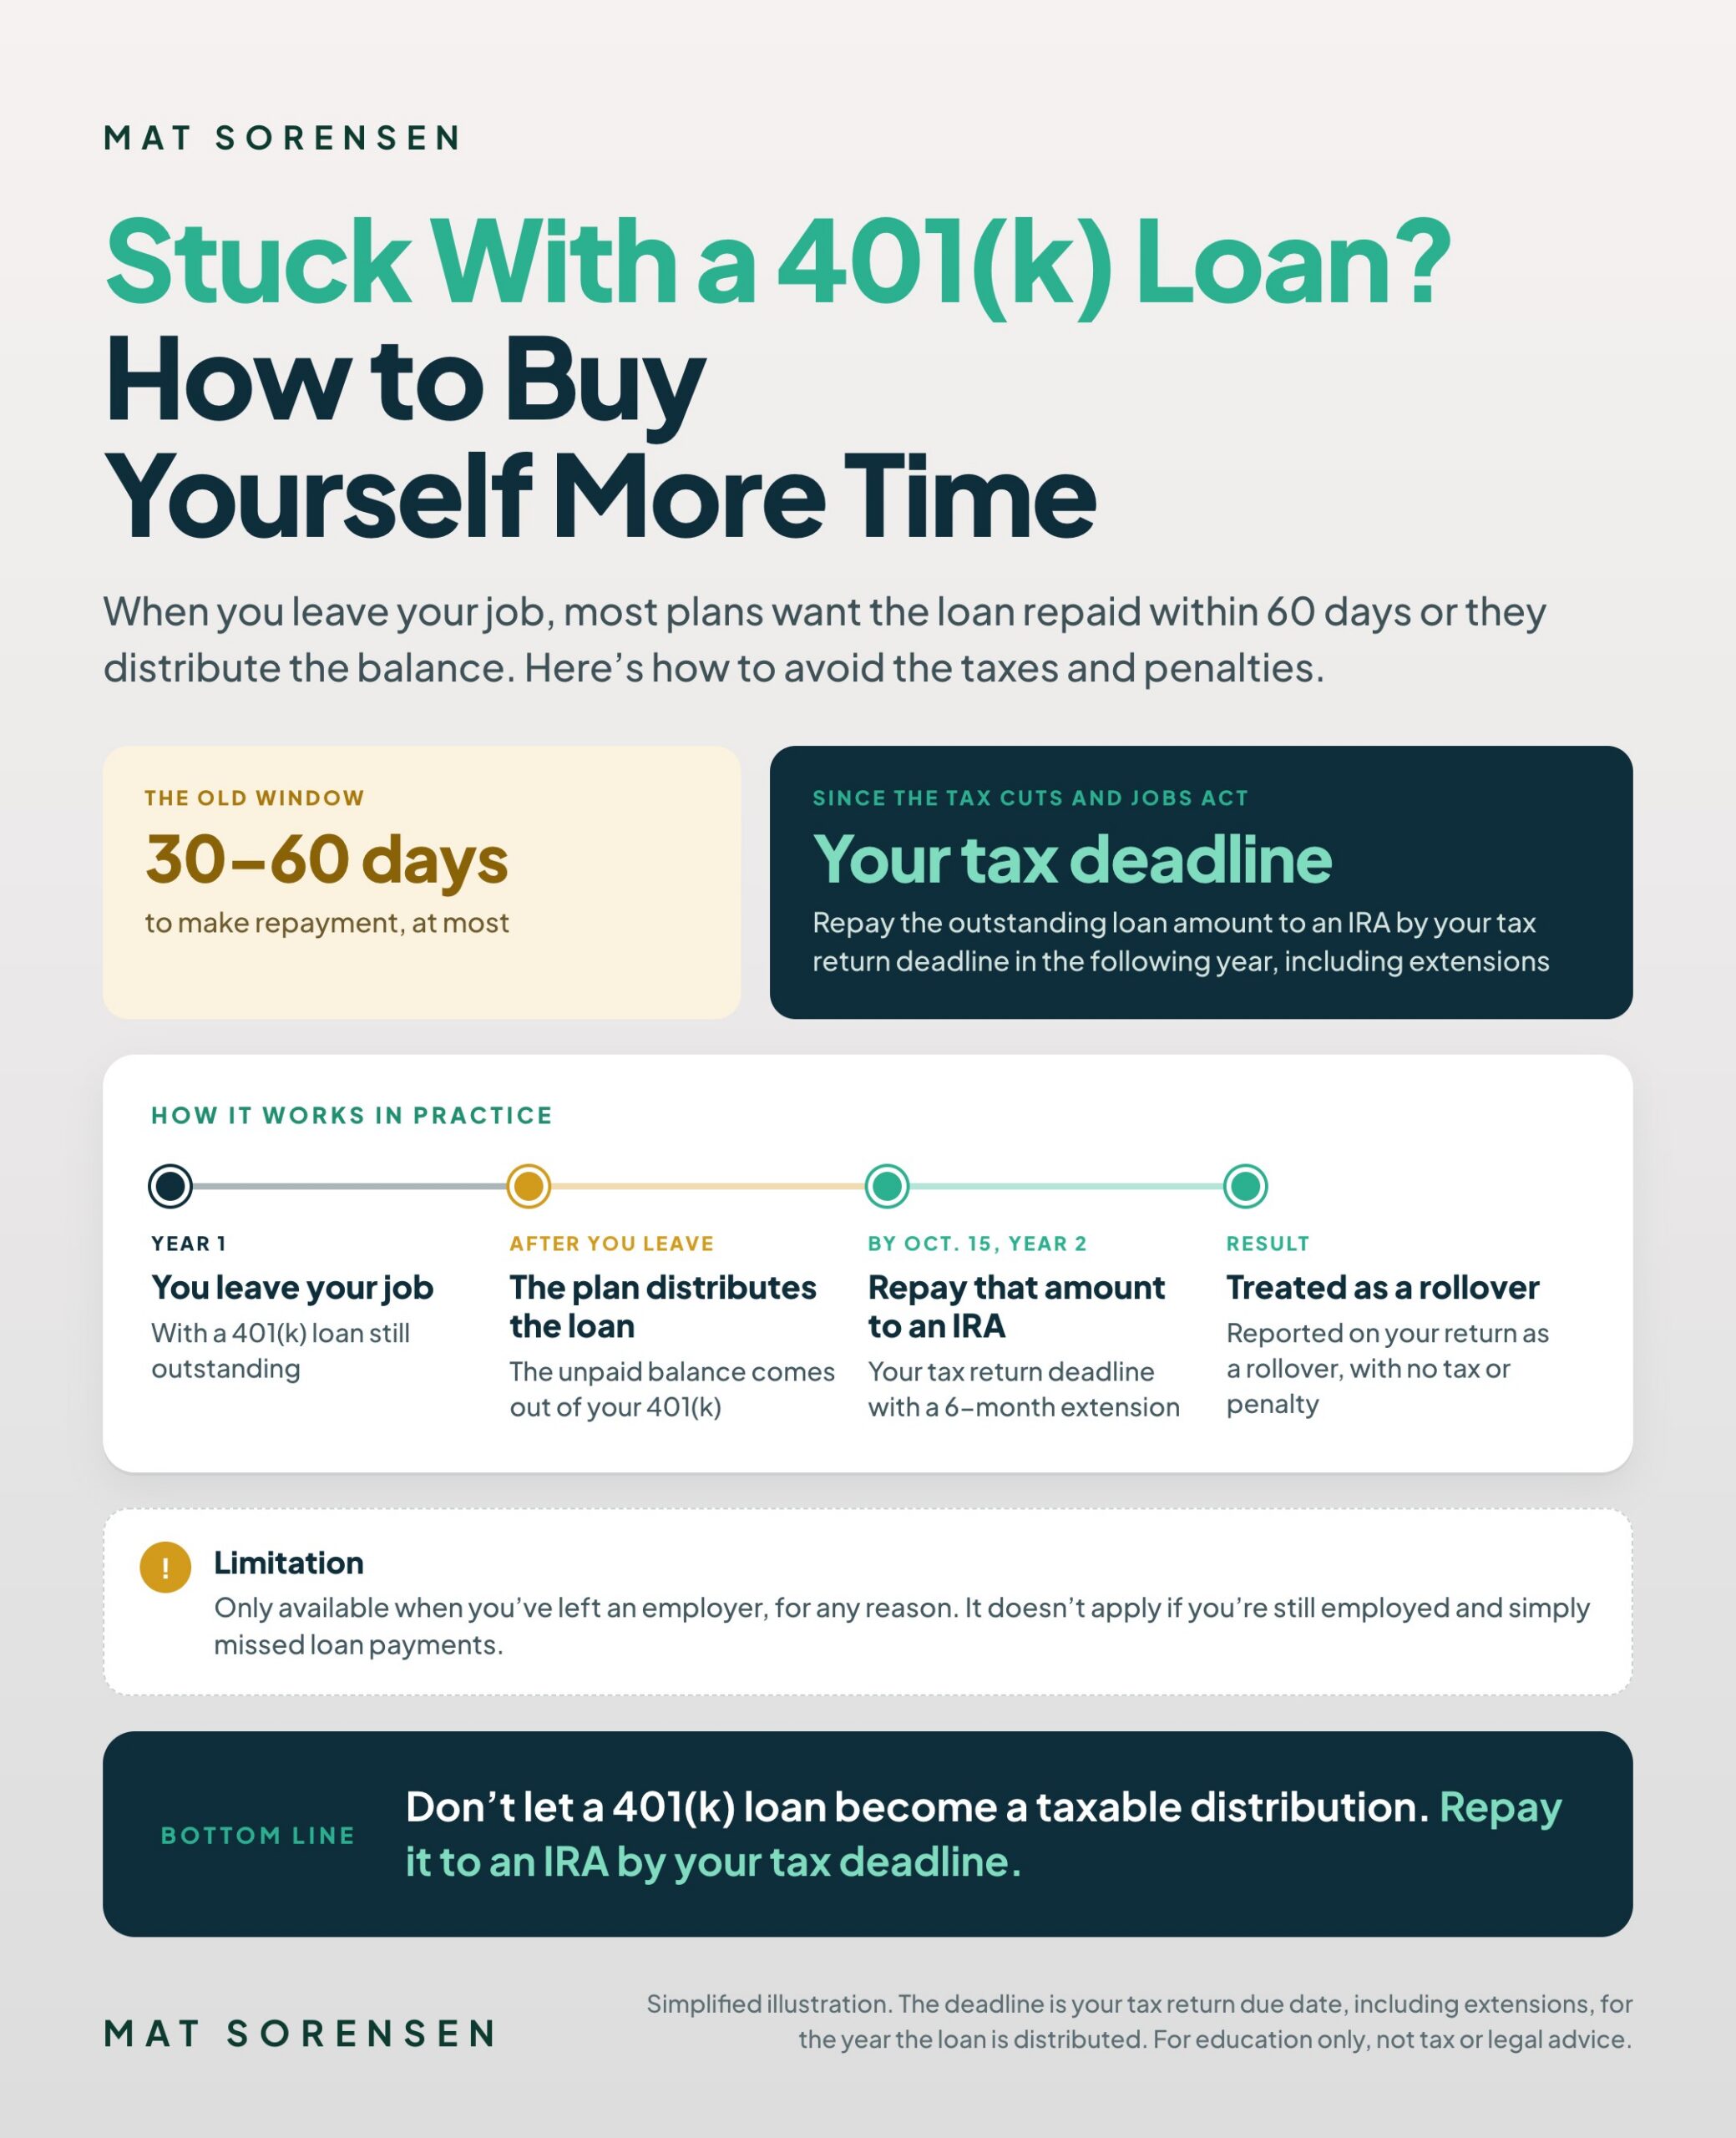
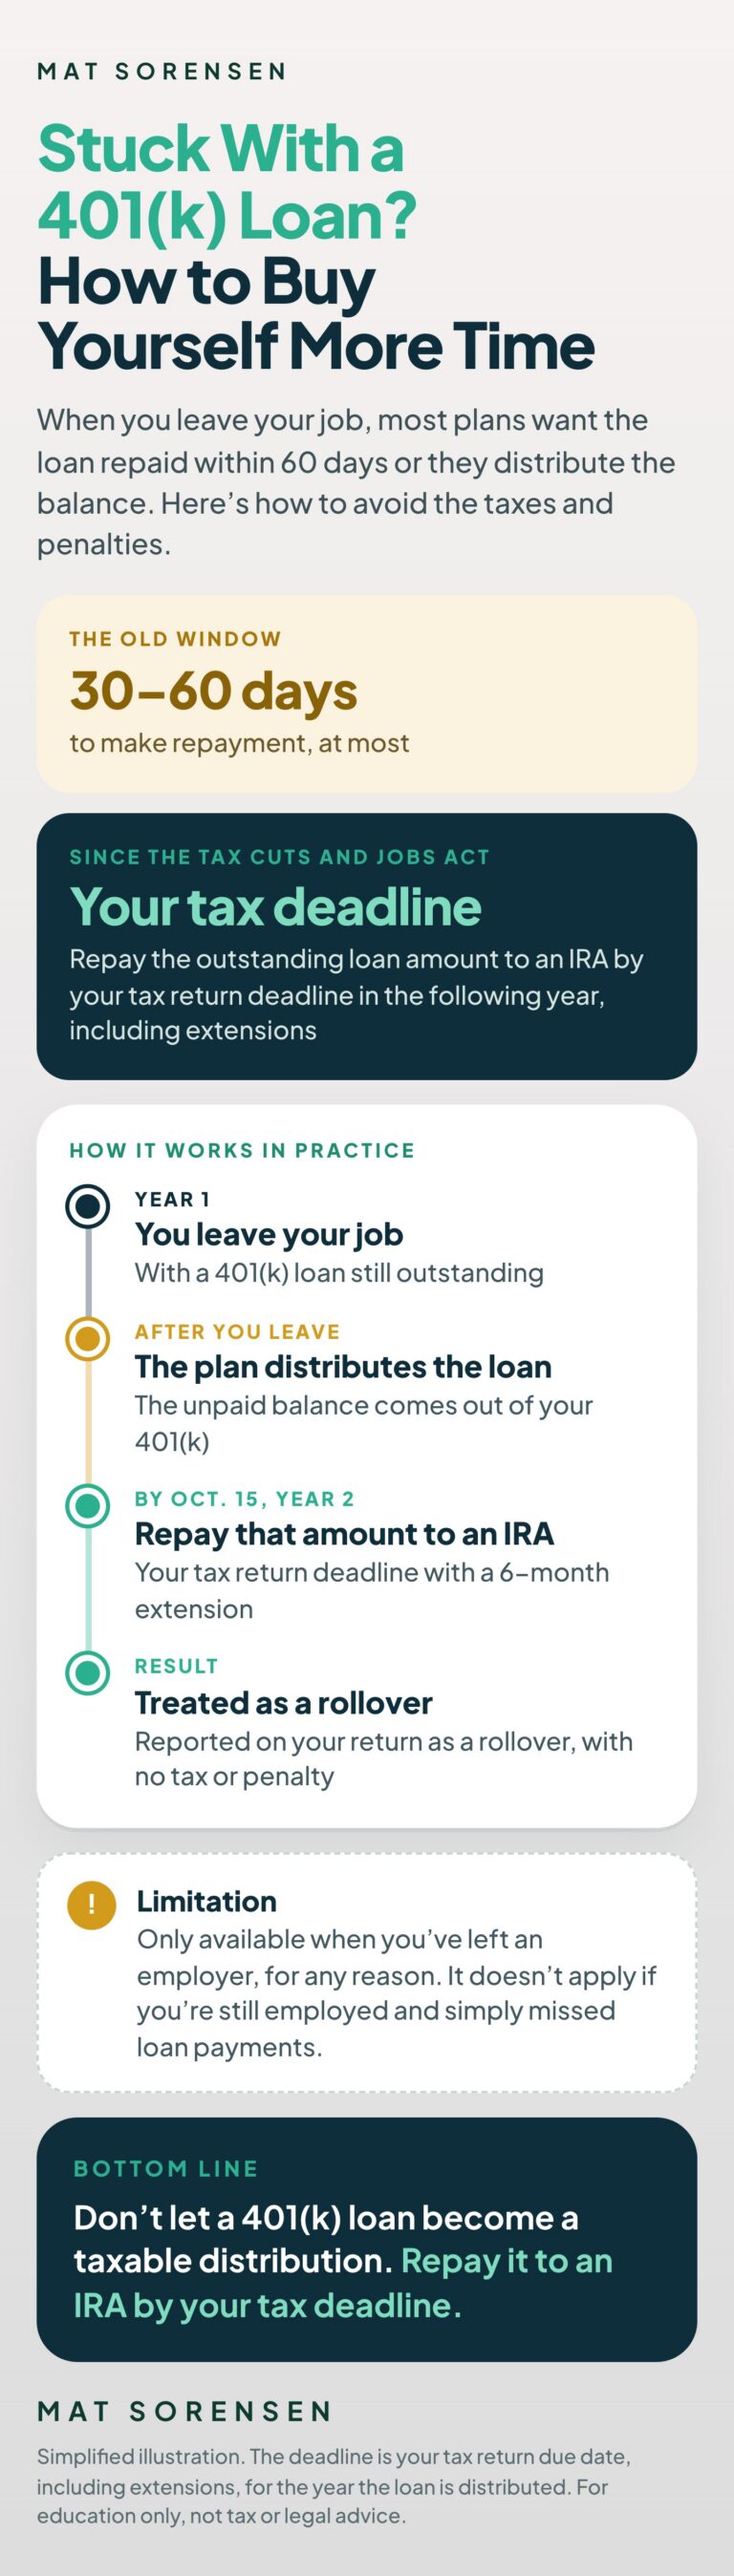
Infographic: leaving your job with a 401(k) loan. Repay the outstanding loan amount to an IRA by your tax return deadline, including extensions, to avoid taxes and penalties

How to Buy Yourself More Time & Avoid the Distribution

The good news is that following the Tax Cuts and Jobs Act (TCJA) you now have the option to re-pay the loan to an IRA to avoid the distribution and you have until your personal tax return deadline of the following year (including extensions) to contribute that re-payment amount to an IRA. By re-paying the amount outstanding on the loan to an IRA, you will avoid taxes and penalties that would otherwise arise from distribution of a participant 401(k) loan.

How It Works In Practice

EXAMPLE

Let’s say you left employment from your employer in February 2026 and that you had a 401(k) loan that was distributed by your employer’s plan following your termination of employment. You will have until October 15th of 2027 (if you extend your personal return, 6 month extension from April 15th) to make re-payment of the amount that was outstanding on the loan to an IRA. These funds are then treated as a rollover to your IRA from the 401(k) plan and your distribution and 1099-R will be reported on your federal tax return as a rollover and will not be subject to tax and penalty. While it’s not perfect it’s far greater time than was previously allowed. Traditionally, you had 30 or 60 days at most to make re-payment.

Limitations

The ability to rollover an outstanding 401(k) loan amount to an IRA is only available when you have left an employer (for any reason). It does not apply in instances where you are still employed and have simply failed to re-pay the loan or to make timely payments.

FREE ROLLOVER GUIDE

Learn how to move an old 401(k) or IRA into a self-directed IRA, tax-free.

Get the Free Transfers & Rollovers Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

Mat Sorensen

Mat has been at the forefront of the self-directed IRA industry since 2006. He is the CEO of Directed IRA & Directed Trust Company where they handle all types of self-directed accounts (IRAs, Roth IRAs, HSAs, Coverdell ESA, Solo Ks, and Custodial Accounts) which are typically invested into real estate, private company/private equity, IRA/LLCs, notes, precious metals, and cryptocurrency. Mat is also a partner at KKOS Lawyers and serves clients nationwide from its Phoenix, AZ office.

He is published regularly on retirement, tax, and business topics, and is a VIP Contributor at Entrepreneur.com. Mat is the best-selling author of the most widely used book in the self-directed IRA industry, The Self-Directed IRA Handbook: An Authoritative Guide for Self-Directed Retirement Plan Investors and Their Advisors.

Solo K 5500-EZ Requirement and Failure to File Penalty Relief

Up close photo of an egg-shaped egg timer.Do you have a Solo 401(k)? Have you been filing form 5500-EZ each year for the Solo 401(k)? Are you aware that there is a penalty up to $150,000 per year for failure to file? While some Solo 401(k)s are exempt from the 5500-EZ filing requirement, we have run across many Solo 401(k) owners who should have filed, but have failed to do so.

The return a Solo 401(k) files is called a 5500-EZ, and it is due annually on July 31st for the prior year. If you have a Solo 401(k) and you have no idea what I’m talking about, stay calm, but read on.

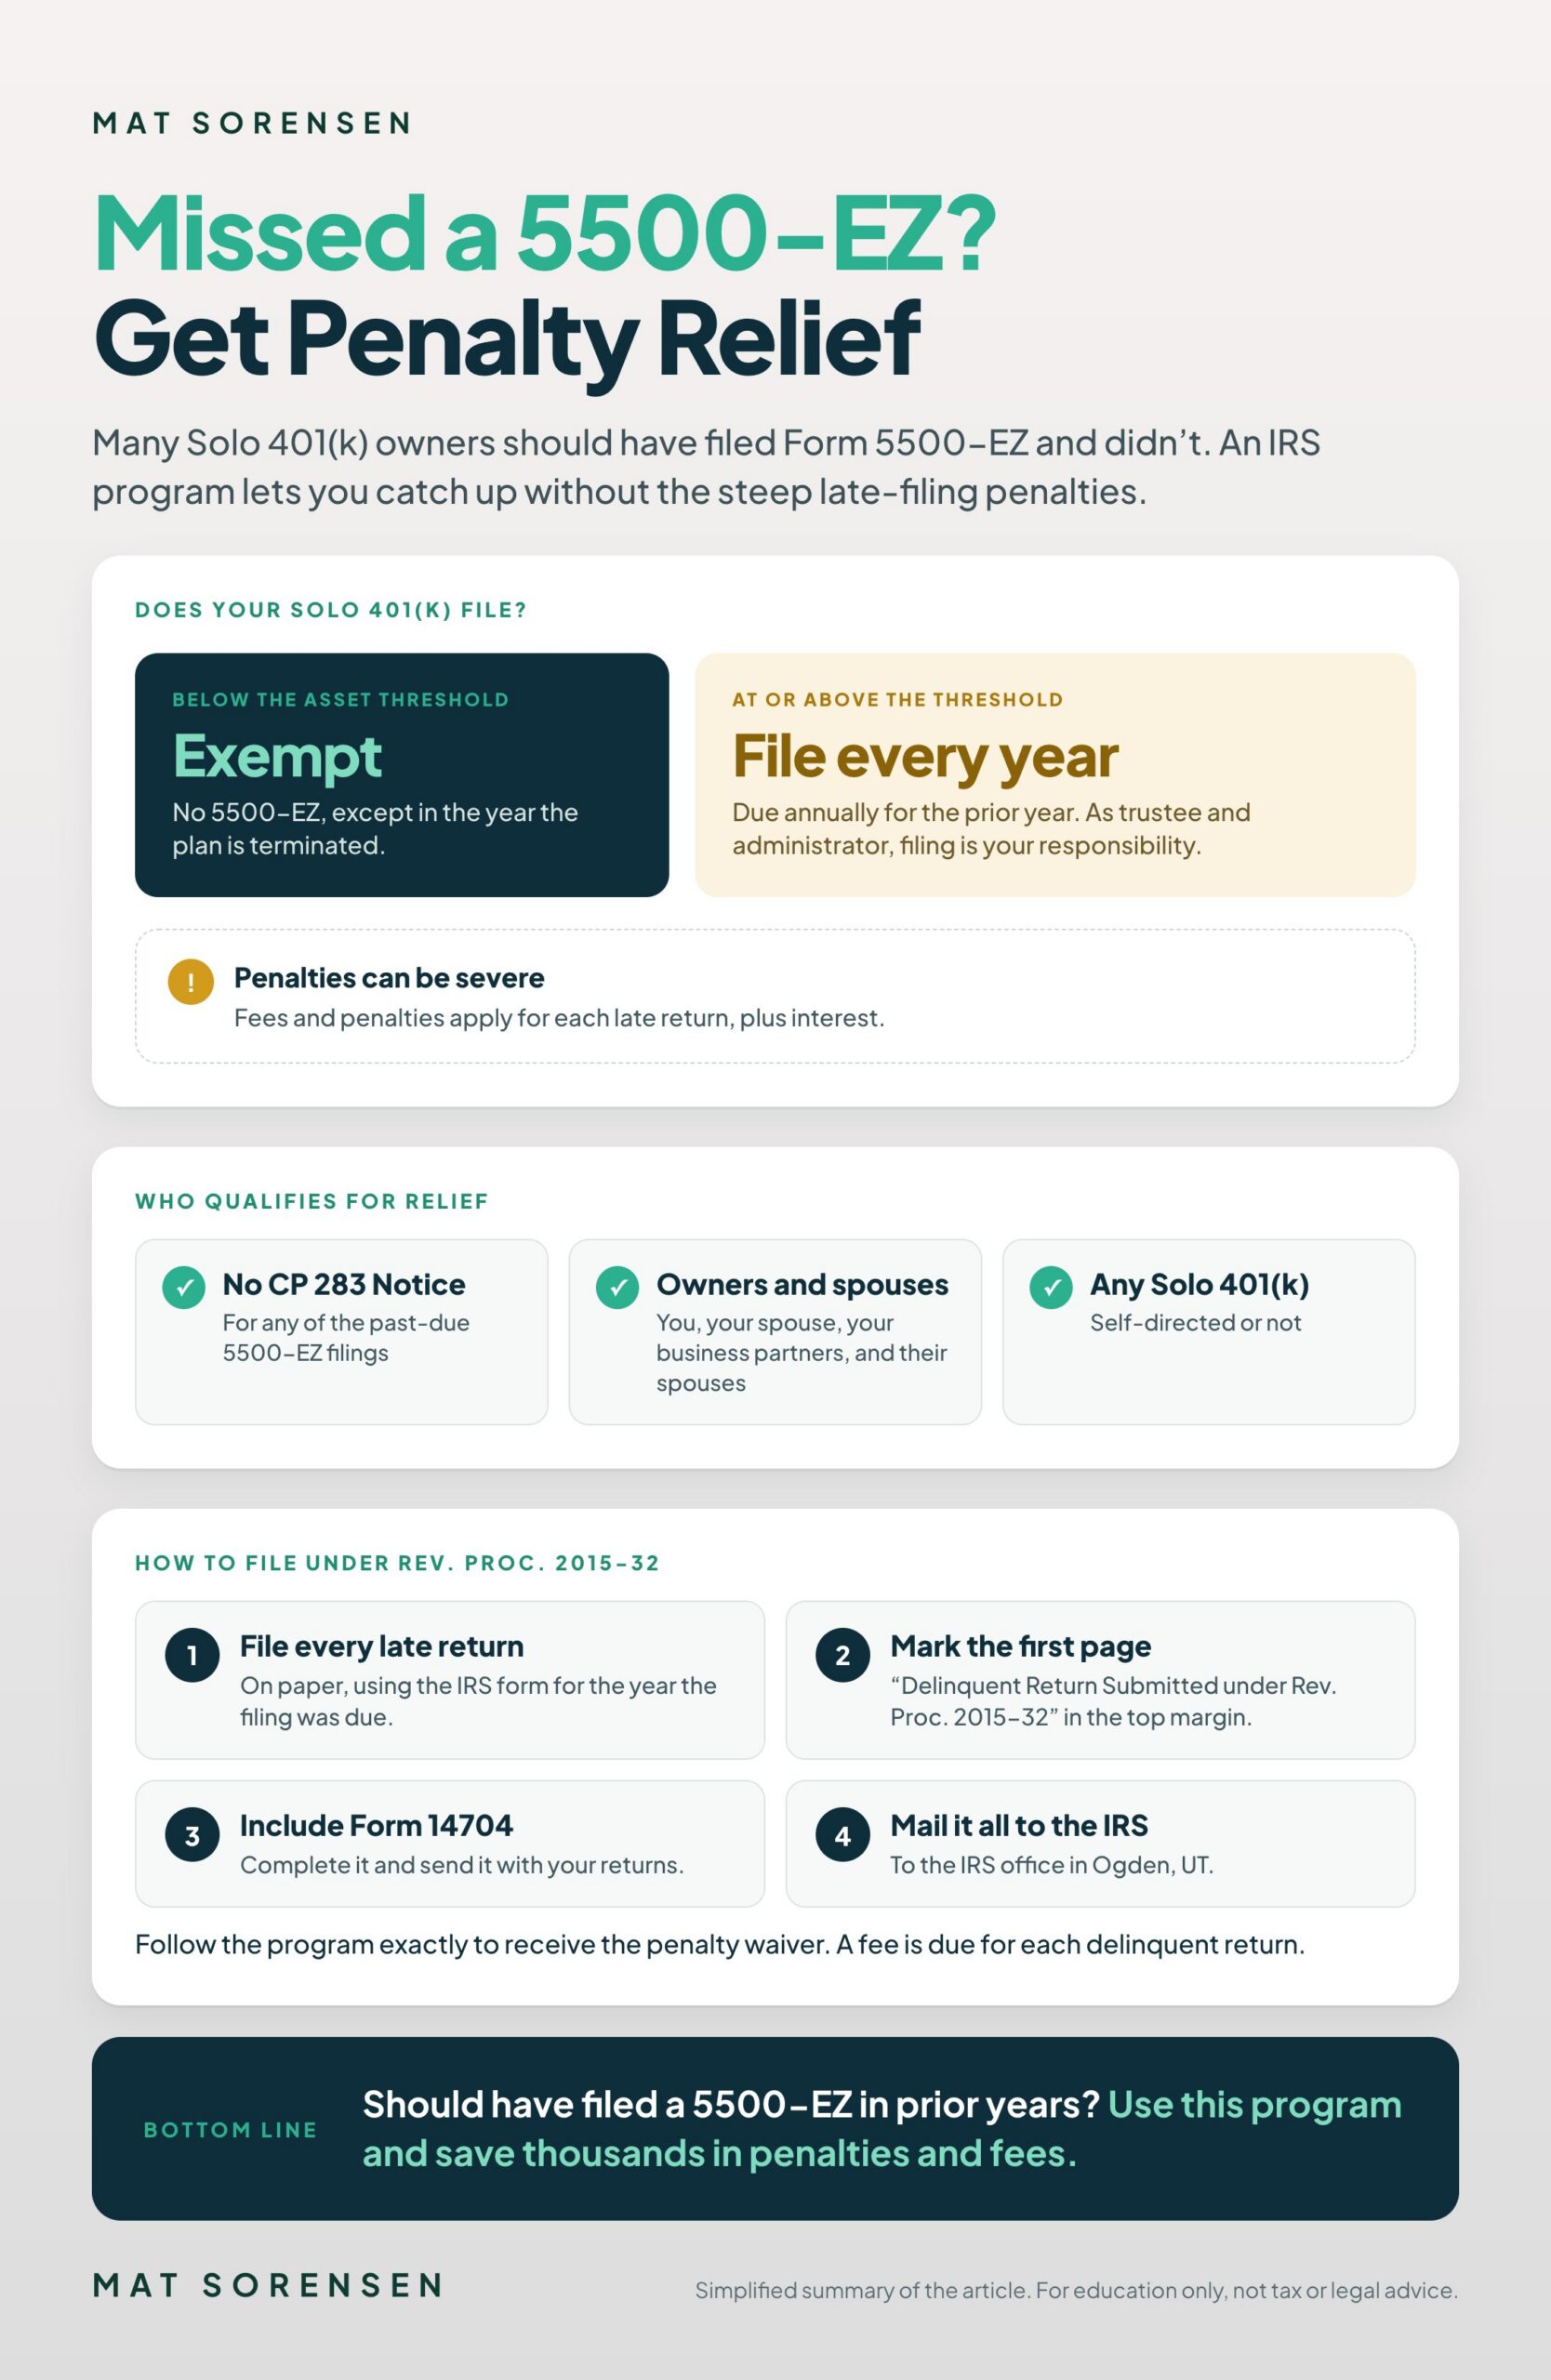
Infographic: when a Solo 401(k) must file Form 5500-EZ, who qualifies for the IRS late-filing penalty relief program, and the four steps to file under Rev. Proc. 2015-32

Benefits of Solo 401(k)s

One of the benefits of a Solo 401(k) is the ease of administration and control, because you can be the 401(k) trustee and administrator. However, as the 401(k) administrator and trustee, it is your own responsibility to make the appropriate tax filings. This would include filing any required tax returns for the 401(k).  Solo 401(k)s with less than $250,000 in assets are exempt and do not need to file a 5500-EZ. All plans with assets valued at $250,000 or greater must file a form 5500-EZ annually. A tax return is also required for a Solo 401(k) when the plan is terminated, even if the plan assets are below $250,000.

Recently, more and more Solo 401(k) owners have contacted us because they set up their Solo 401(k) online or with some other company, and were never made aware that they are supposed to file a 5500-EZ when their plan assets exceed $250,000.  Some of these individuals have multiple years in which they should have filed the 5500-EZ, but failed to do so. The penalties for failing to file a 5500-EZ when it is required can be quite severe, with fees and penalties as high as $150,000 for each late return plus interest.

Failure to File Relief

Fortunately, the IRS has a temporary pilot program that provides automatic relief from IRS Late filing penalties on past due 5500-EZ filings.  The penalty relief began as a temporary program in 2014 and was made permanent via Rev Proc 2015-32.

In order to qualify for this program, your Solo 401(k) plan must not have received a CP 283 Notice for any past due 5500-EZ filings, and the only participants of your Solo 401(k) plan can be you and your spouse, and your business partner(s) and their spouse. There is a $500 fee due for each delinquent return up to a total of $1,500 or three years.  This program is available to all Solo 401(k) plans, regardless of whether it is a self-directed plan.

The IRS has provided details via Rev Proc 15-32. In order to qualify and receive a waiver of penalties under the program, you must follow the program exactly.  In short, you must do all of the following:

  1. 1File all delinquent returns using the IRS form in the year the filing was due. This must be via paper form.
  2. 2Mark on the top margin of the first page, “Delinquent Return Submitted under Rev. Proc. 2015-32.”
  3. 3Complete and include IRS Form 14704.
  4. 4Mail all documents to the IRS, Ogden, UT office.

In sum, if you have a Solo 401(k) plan that should have filed a 5500-EZ for prior years, then you should take advantage of this program, which will save you thousands of dollars in penalties and fees.  If you have any questions about this program or would like assistance with submitting your late 5500-EZ filings under this program, please contact our law firm as we are assisting clients with current and past due 5500-EZ filings for their Solo 401(k)s.

FREE SOLO 401(K) GUIDE

Self-employed? Learn how a self-directed Solo 401(k) works and how much you can contribute.

Get the Free Solo 401(k) Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

IRA Contribution Deadlines: Two Out of Three IRA Types Can’t be Extended

You have until April 18th, 2017 to make 2016 IRA contributions for Roth and Traditional IRAs. If you’re self-employed and are using a SEP, your deadline is determined by your company’s tax filing deadline (e.g. s-corp, partnership, or sole prop). So, if you were an s-corp or partnership in 2016, then your filing deadline was March 15th, 2017. If you are a sole prop, then the deadline is April 18th, 2017. If you extended your company return, that extension will also apply to your SEP IRA contributions. The table below breaks down the deadlines and extension options for Traditional, Roth and SEP IRAs.

UPDATE (NOV 2026)

This article was written for the 2016 tax year. The same rules apply every year: Traditional and Roth IRA contributions are due by your tax return due date, not including extensions (generally April 15 of the next year), and SEP IRA contributions by the business’s tax return due date, including extensions. (Source: IRS Pub 590-A; IRS SEP FAQ)

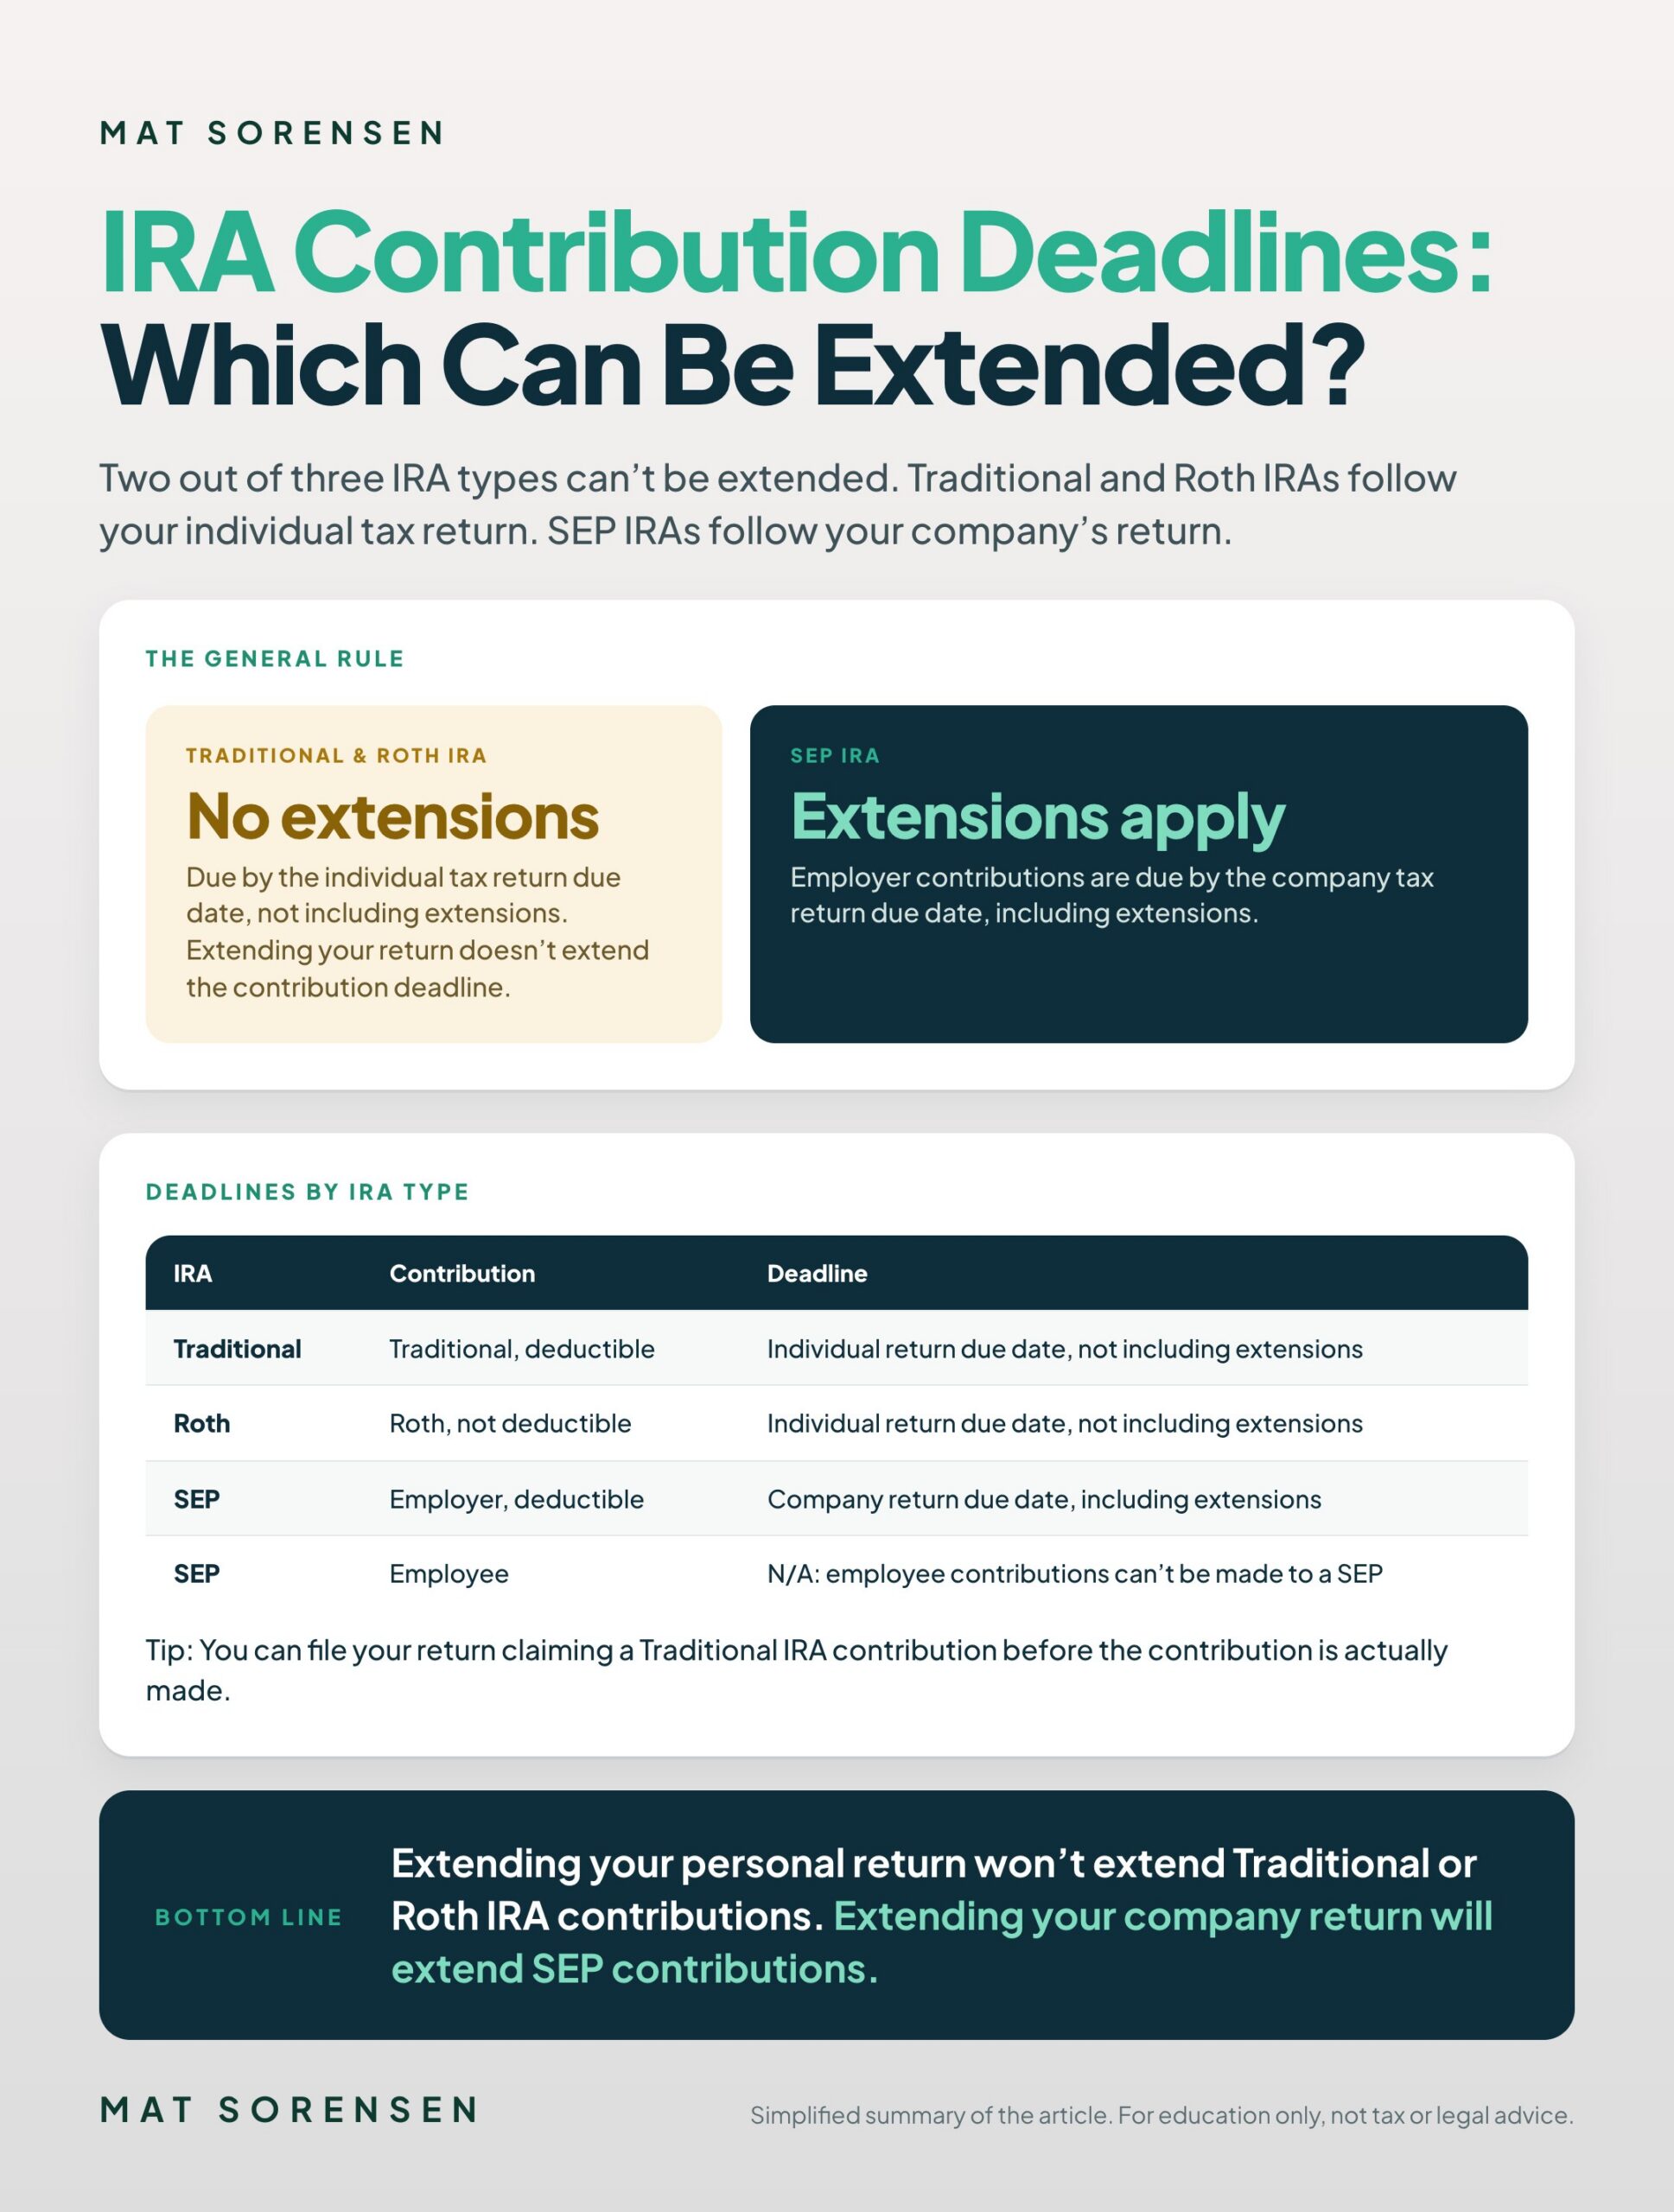
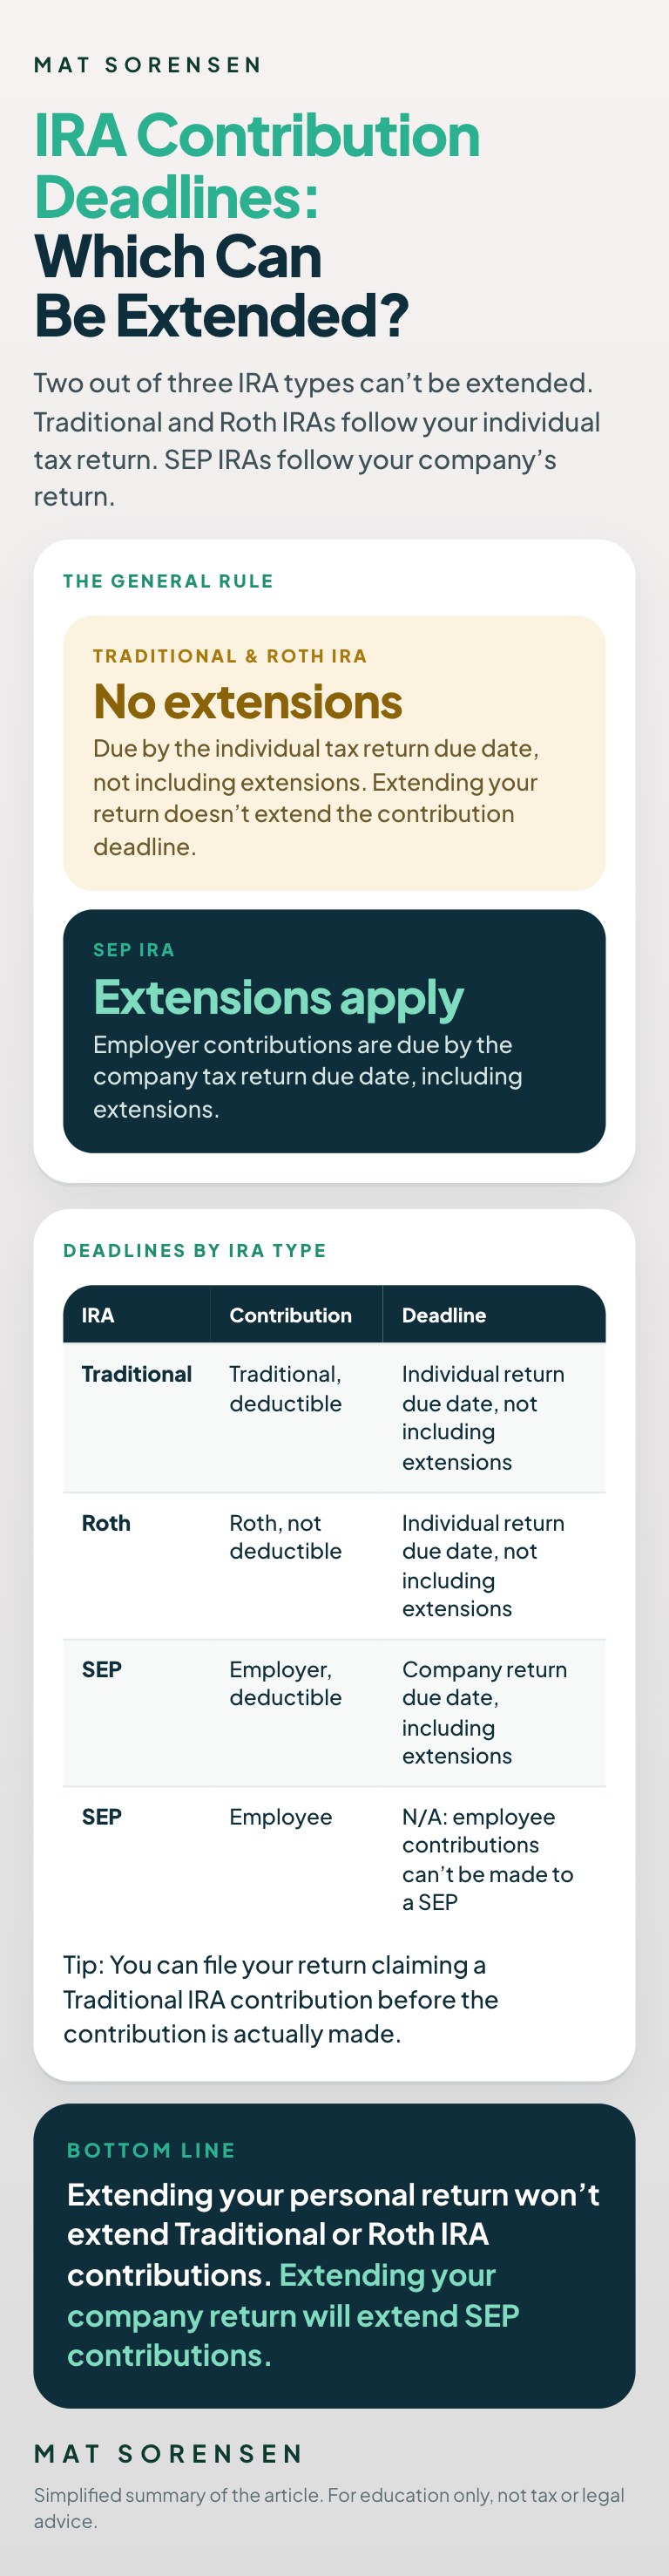
Infographic: Traditional and Roth IRA contribution deadlines do not include extensions, while SEP IRA employer contribution deadlines do
Type of IRA Contribution Type Deadline Details
Traditional IRA Traditional, Deductible April 18th, 2017: Due Date for Individual Tax Return Filing (not including extensions). IRC § 219(f)(3); You can file your return claiming a contribution before the contribution is actually made.  Rev. Rul. 84-18.
Roth IRA Roth, Not Deductible April 18th, 2017: Due Date for Individual Tax Return Filing (not including extensions). IRC § 408A(c)(7).
SEP IRA  Employee, Deductible N/A: Employee contributions cannot be made to a SEP IRA plan.
Employer Contribution, Deductible March 15/April 15th: Due Date for Company Tax Return Filing (including extensions). IRC § 404(h)(1)(B).

As outlined above, you have until the 2016 individual tax return deadline of April 18th, 2017 to make 2016 Traditional and Roth IRA contributions. The deadline for Traditional and Roth IRAs, however, does not include extensions. So, even if you extend your 2016 tax return, your 2016 Traditional and Roth IRA contributions are still due on April 18th, 2017.

SEP IRA contribution deadlines are based on the company tax return deadline, which could be March 15th if the company is taxed as an s-corporation or partnership, and April 15th if it is a c-corporation or sole proprietorship. Keep in mind that this deadline includes extensions, so if you extend your company tax return filing, you will extend the time period to make 2016 SEP IRA contributions.

FREE SELF-DIRECTED IRA GUIDE

Learn how to invest your IRA in real estate, private companies, notes, precious metals, and more.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist