LLC Masterclass Part 2: How to Set Up an LLC the Right Way

You need to make sure your LLC is set up the right way—otherwise, all those benefits you thought you were getting? Asset protection, tax savings, legitimacy… you might not be getting any of it.

This is where a lot of people mess up. After 20+ years and thousands of LLCs formed for clients nationwide, I’ve seen how small mistakes at the start can turn into expensive problems later.

In this article—I’ll walk you through the four steps to properly set up your LLC and the key decisions you don’t want to get wrong.
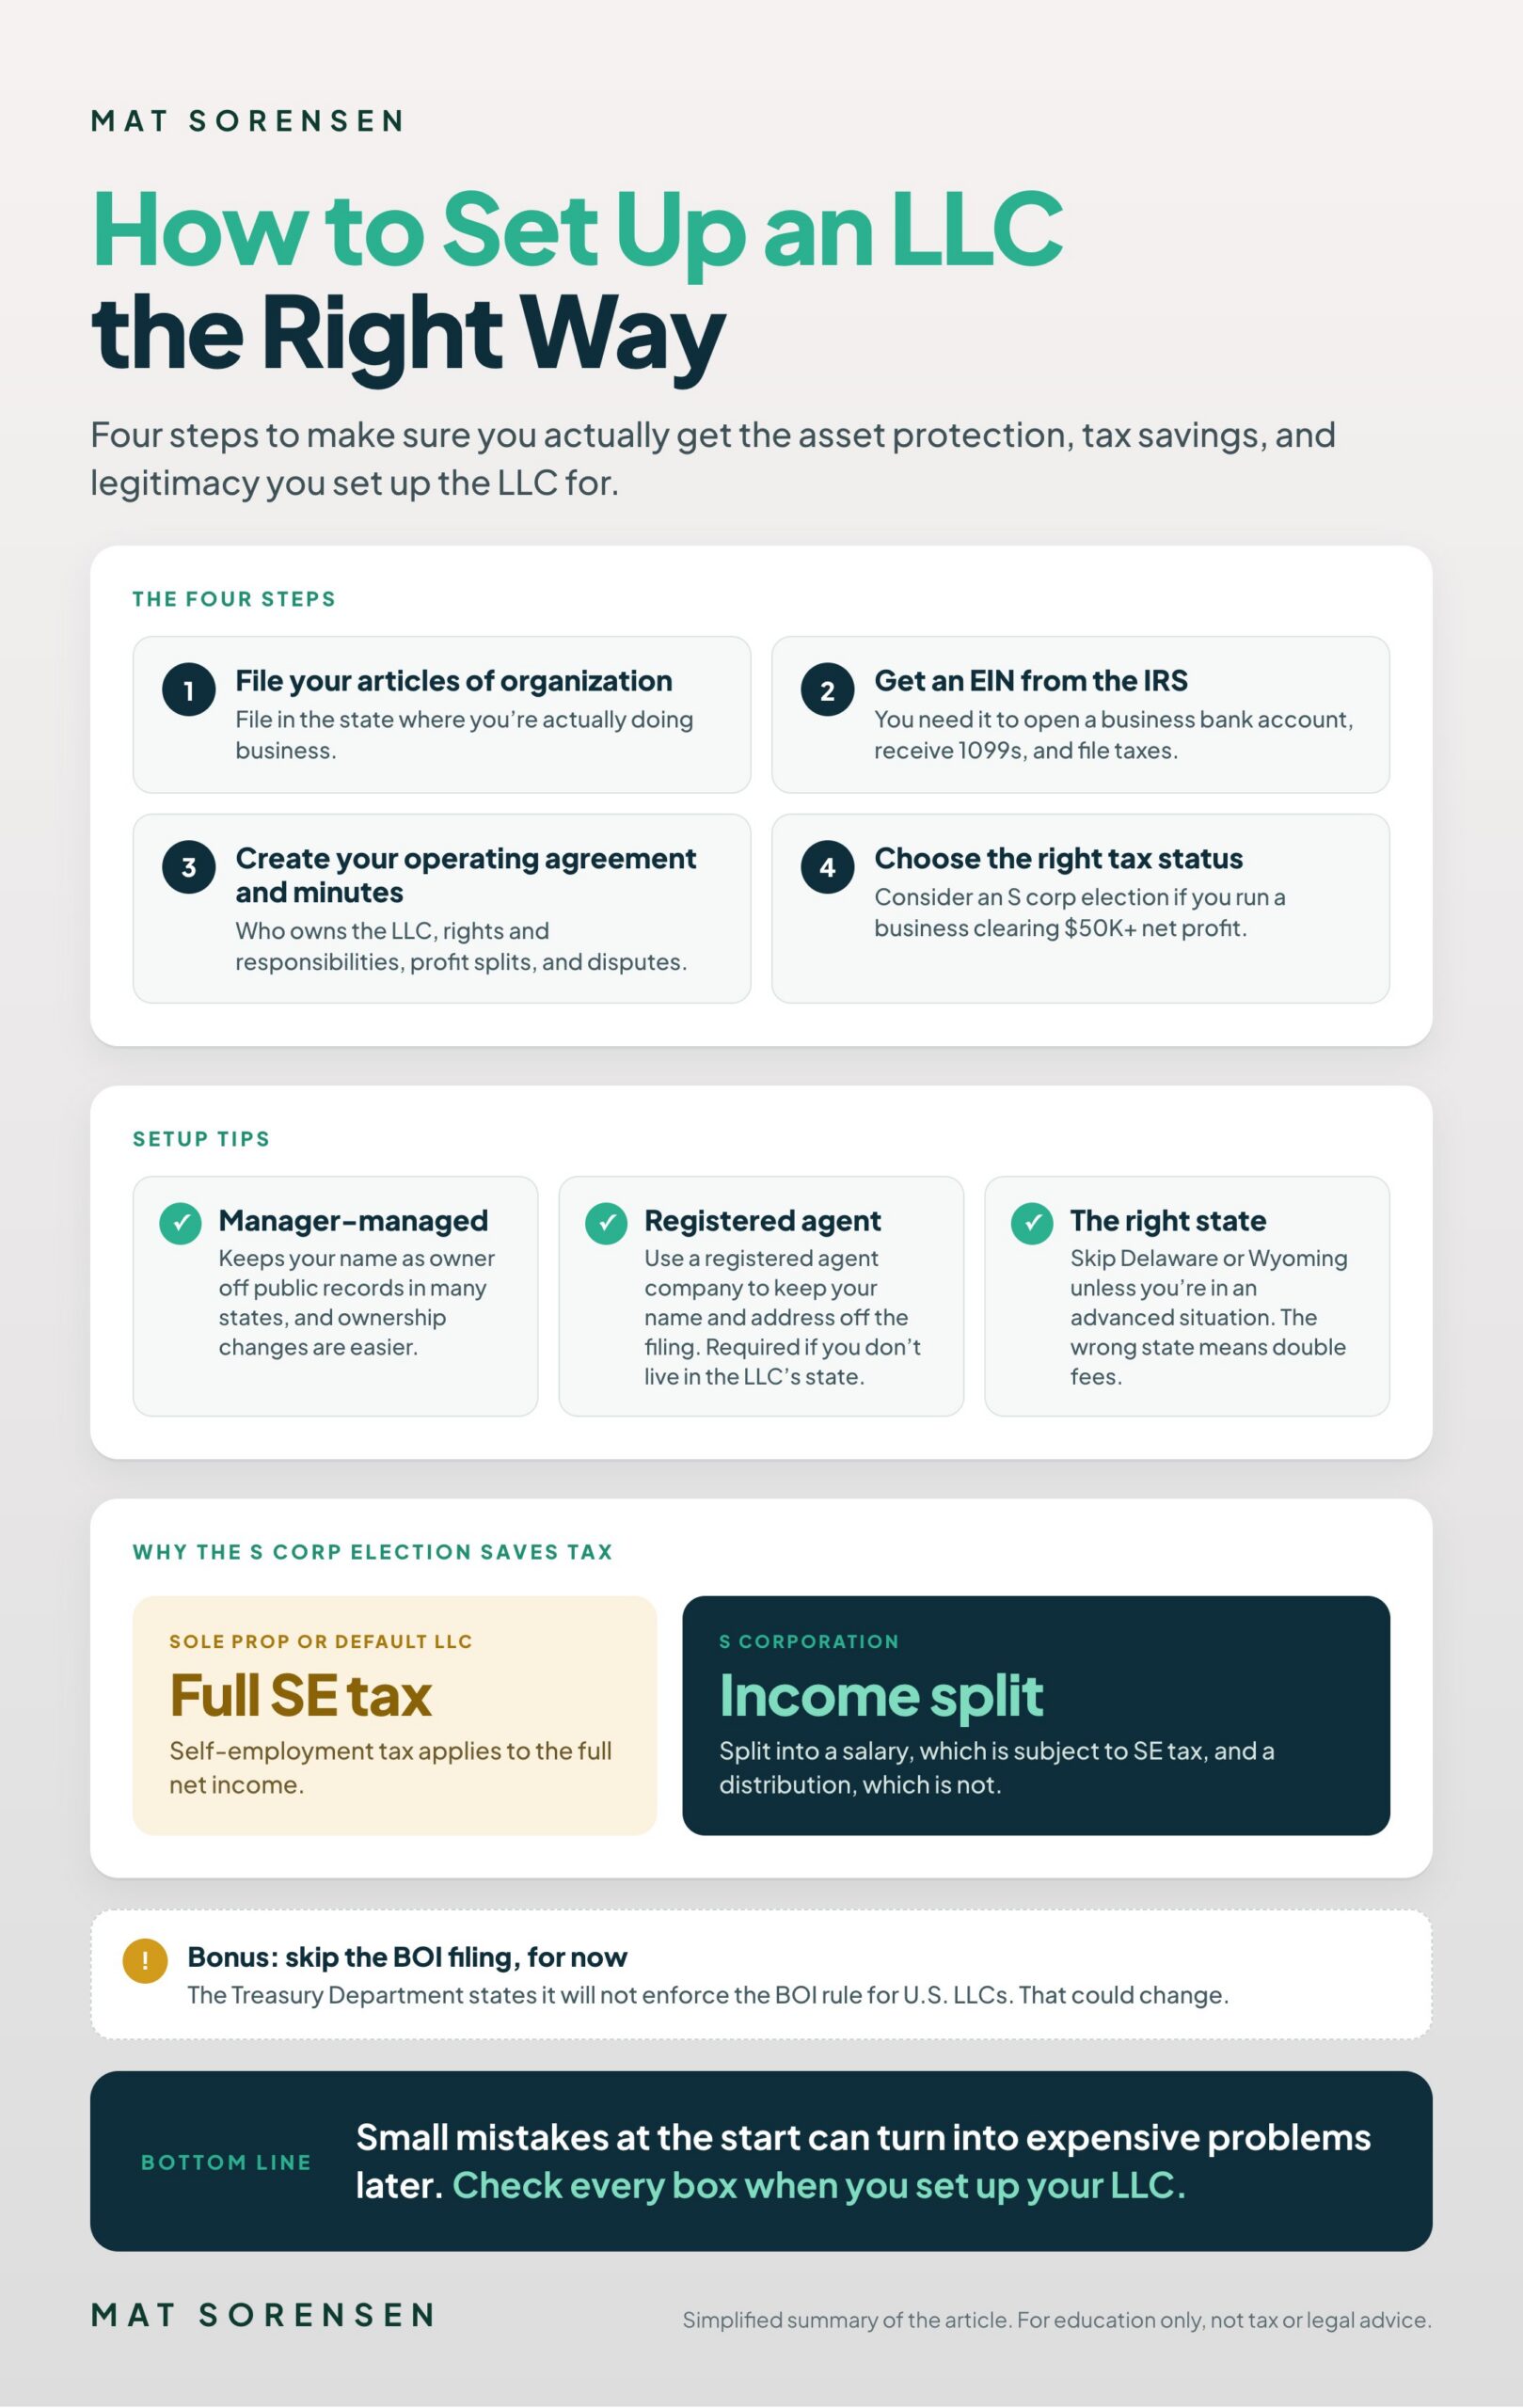
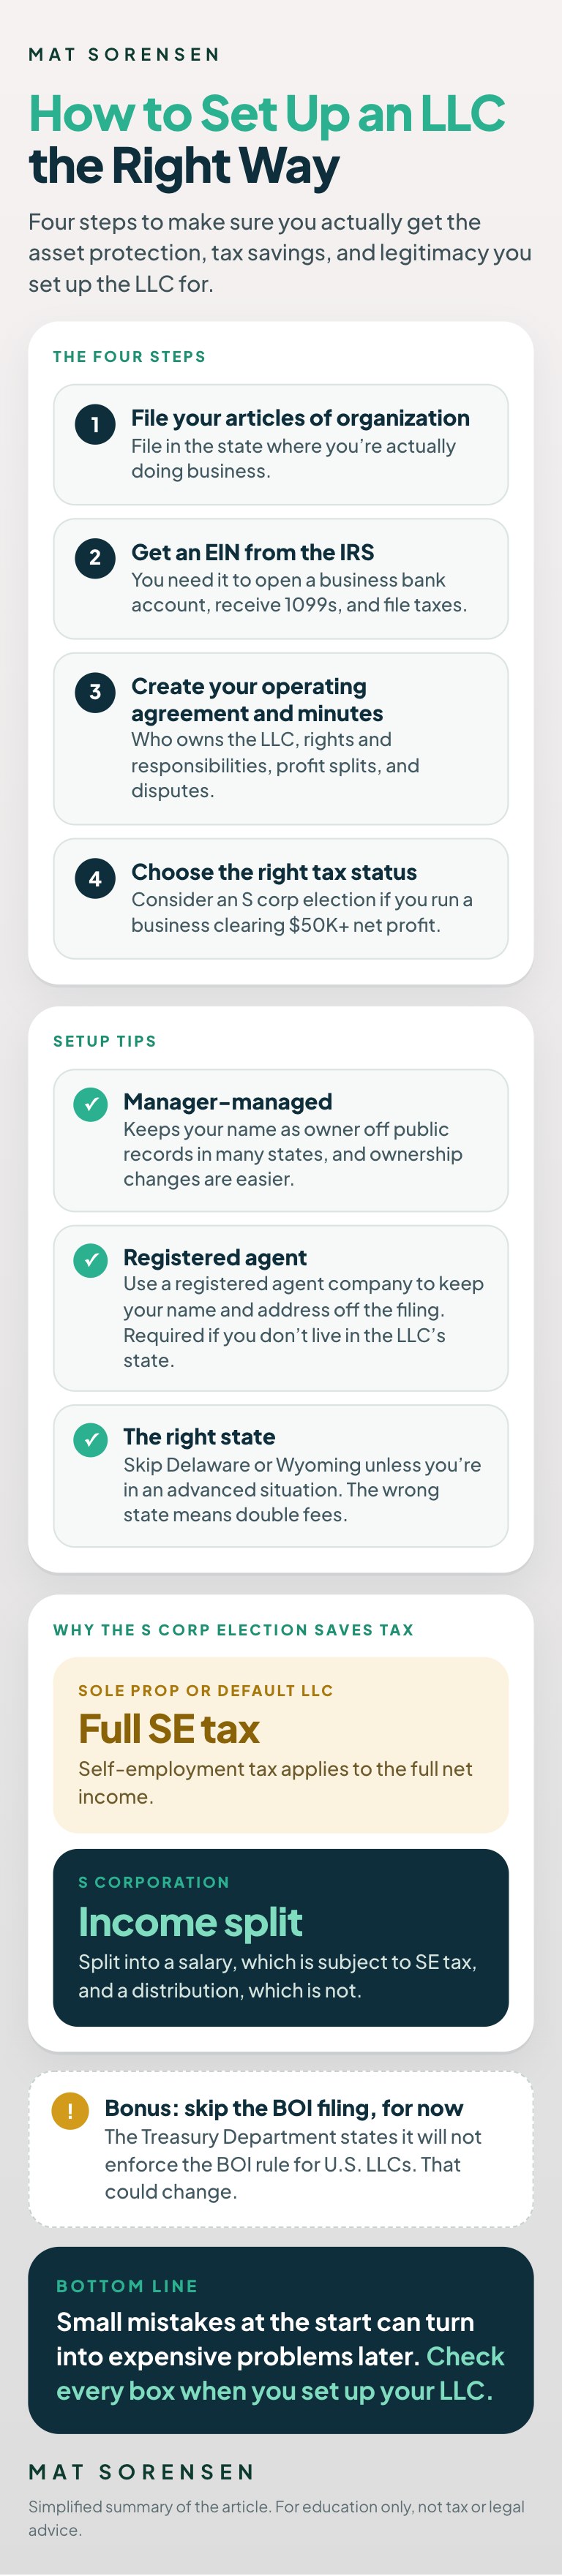
Infographic: the four steps to set up an LLC, setup tips on management, registered agents, and choosing a state, and why an S corp election can save tax

Step 1: File Your Articles of Organization

The articles of organization is the official document filed with your state that forms the LLC. It includes:

  • ✓Your business name
  • ✓Registered agent (who gets served lawsuits and legal notices)
  • ✓Management structure (manager vs. member-managed) – Member is LLC lingo for “owner”
  • ✓Principal address

What state should you file in?

File in the state where you’re actually doing business. If you live in California and own a rental in Ohio, file in Ohio. Don’t fall for the “Delaware or Wyoming” structure unless you’re in an advanced situation and you’re intentionally layering for privacy, capital raising, or charging order protection (more on that in another video). Otherwise, filing in the wrong state means double fees and extra registrations.

Tip: Choose manager-managed. It gives you more privacy and flexibility—you list yourself as the manager, not as the owner, which keeps your name as owner off public records in many states. It’s also easier to change ownership as the member owner isn’t listed and doesn’t need to change if say your revocable trust becomes owner of the LLC – or if you add a partner.

Tip: Choose a registered agent company to serve as your registered agent to keep your name and address off the public filing and to avoid getting a lawsuit or served at your home. If you’re setting up an LLC in a state where you do not reside you must use a registered agent company as every state requires a physical address (no PO Box) and a person or company AT that address be listed. This can cost you from $125/yr to $350/year depending on the company. My clients use our registered agent company, Main Street Business Services who serves as Registered Agent in all 50 states.

Step 2: Get an EIN (Tax ID) from the IRS

An EIN (Employer Identification Number) is like a Social Security number for your business. It’s how the IRS identifies the company for tax purposes. It is also called a tax ID. You’ll need it to:

  • ✓Open a business bank account
  • ✓Receive 1099s
  • ✓File taxes for the business

You can get this directly from the IRS. Our law firm includes this in our LLC setup service.

Step 3: Create Your Operating Agreement & Initial Minutes

The operating agreement is a much more detailed document than the articles. It documents:

  • ✓The Limited Liability protection.
  • ✓Who owns the LLC
  • ✓How much each person owns
  • ✓Rights and responsibilities of members and managers
  • ✓Profit splits and dispute resolution

If you have partners or investors, this is critical. Your operating agreement is your partnership agreement. It’s your roadmap—and skipping it leads to confusion and legal chaos down the line.

Step 4: Choose the Right Tax Status

LLCs don’t save taxes by default. The savings come from how your LLC is structured for tax planning.

By default:

  • ✓A single-member LLC is taxed as a sole proprietorship
  • ✓A multi-member LLC is taxed as a partnership

But you can elect to be taxed as an S corporation, and that’s where real tax strategy comes into play—especially if you’re earning more than $50,000 in net income and running a service-based business.

Here’s how it works:

S Corporation Tax Strategy

If you make $100,000 as a sole prop or default LLC, you pay 15.3% self-employment tax to the IRS on the full amount—$15,300 just in SE tax.

With an S corporation, you can split that $100K into:

  • ✓$40K salary (subject to self-employment tax)
  • ✓$60K distribution (not subject to SE tax)
Portion Treated As Tax Impact
$40,000 W-2 Salary 15.3% self-employment tax = $6,120
$60,000 Net Profit ❌ No SE tax

Annual savings: ~$9,000

You still pay regular income tax based on your tax bracket on both, but avoiding SE tax on the net profit portion is a significant win.

Important: Only elect S corp if you’re operating a business and clearing $50K+ net profit. If you own rentals or only make a few thousand (cost of s-corp return not worth saving), the S election doesn’t help and might hurt.

You can make the election later if needed—just don’t wait too long and miss your opportunity to save on taxes.

BONUS: Skip the BOI Filing (For Now)

You may have heard about the Beneficial Ownership Information (BOI) filing with FinCEN. It was set to apply to most LLCs in 2024—but due to federal court rulings and guidance from the U.S. Treasury Department, you do not need to file a BOI report in 2025 if you’re a U.S. LLC or corporation. The Treasury Department states that they will not enforce the BOI rule.

That could change in future administrations, but for now—skip it.

Recap: The Right Way to Set Up Your LLC

To do it right, make sure you check all these boxes:

  • ✓Articles of Organization in the correct state
  • ✓Manager-managed structure for ownership privacy and ease of use
  • ✓EIN from the IRS
  • ✓Operating Agreement & Minutes (even if it’s just you)
  • ✓S Corp election (if you’re earning over $50K from services)
  • ✓No BOI filing required (for now)

Need Help?

Our law firm, KKOS Lawyers, can handle all of this for you—proper filing, EIN, operating agreement, S election, and more. We’ve set up thousands of LLCs and know how to tailor the setup for your unique situation.

👉 Get Started with KKOS Lawyers

Key Takeaways

  • ✓File in the state where you do business – Not where influencers say. Avoid double fees.
  • ✓Go manager-managed – Gives you privacy and keeps your ownership off public record.
  • ✓EIN and bank account are essential – You need both to operate cleanly and separate business from personal finances.
  • ✓Operating agreement matters – Especially with partners. Don’t skip this documentation.
  • ✓Elect S Corp if you’re earning $50K+ in net income – It can save you $9,000/year in self-employment tax.
  • ✓Skip the BOI filing for now – It’s not required in 2025 due to U.S. Treasury guidance.
  • ✓Choose a Registered Agent company to keep your name and address off the state filing and to avoid getting served lawsuits or legal notices at your home or business. It’s also required to use a R.A. company if you don’t live in the state of the LLC.

LLC Masterclass, Part 1: Do You Really NEED an LLC for Your Business or Real Estate Investment?

Do you need an LLC for your business or your real estate investments?

This is the most common question we get from entrepreneurs, side hustlers, and real estate investors—and for good reason. LLCs are one of the powerful tools for protecting assets, building legitimacy, and structuring ownership the right way.

But not everyone needs one.

After setting up over 10,000 LLCs nationwide through my law firm, KKOS Lawyers here are the four key scenarios where you absolutely should have an LLC—and what you’re risking if you don’t.

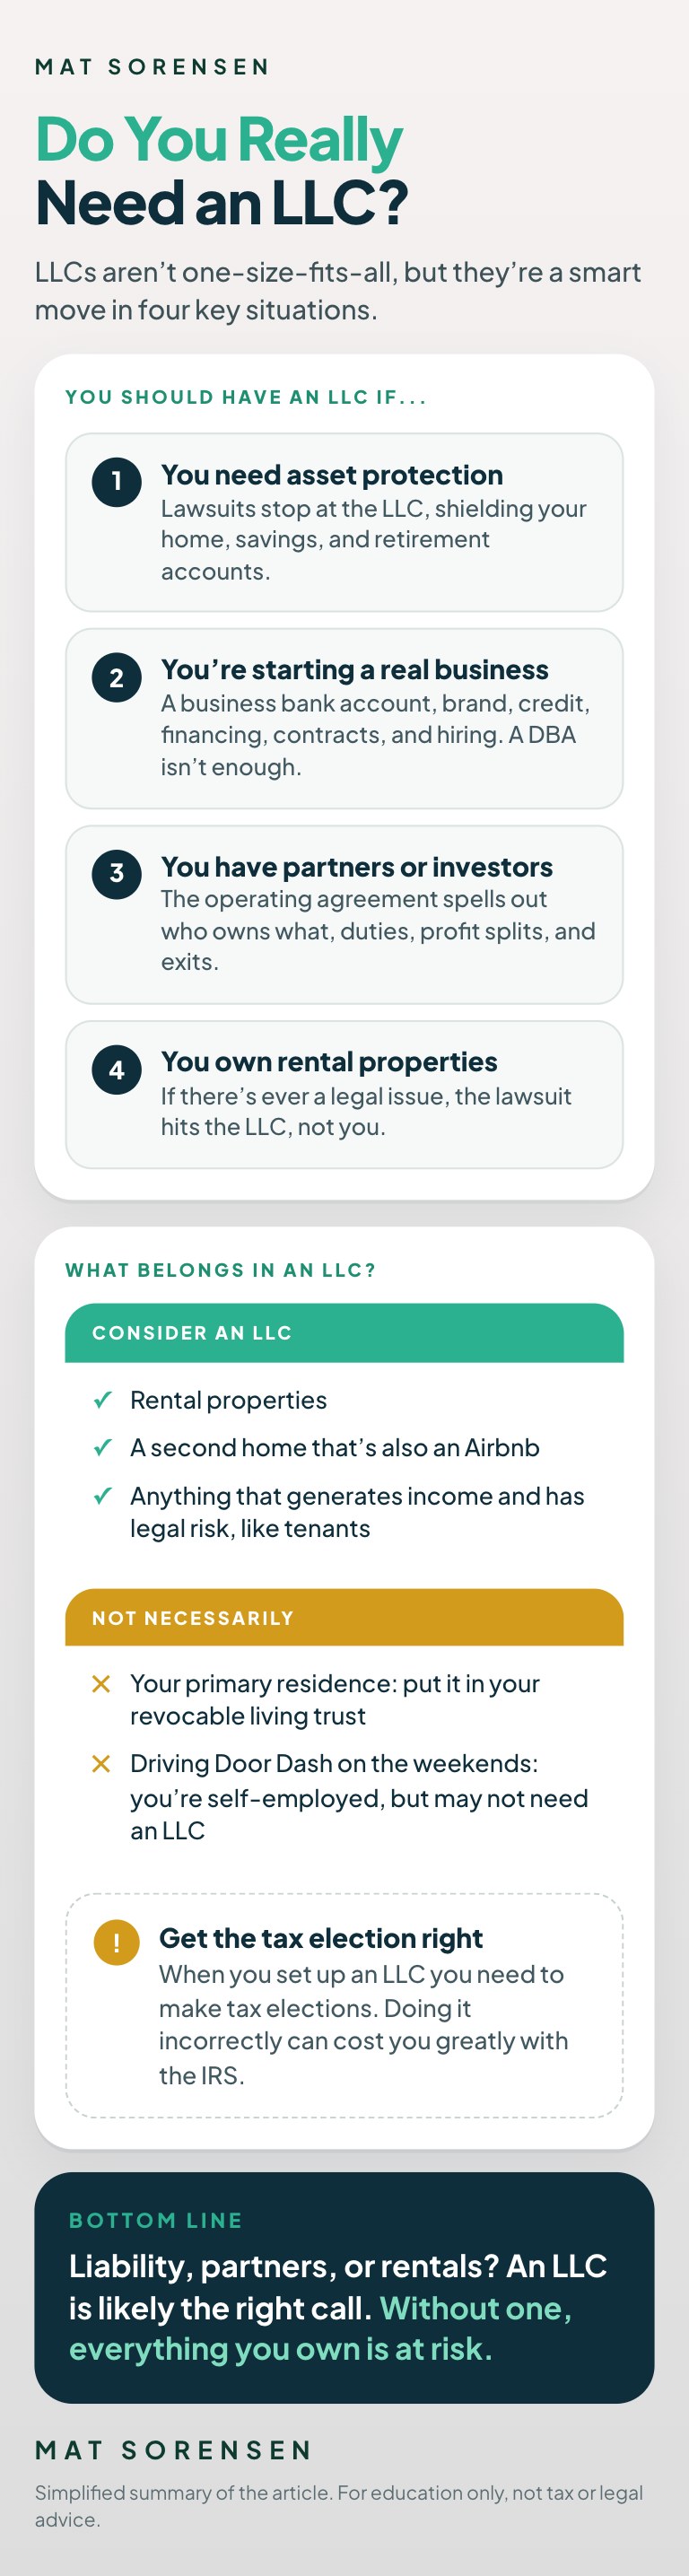
Infographic: four situations where you should have an LLC, what property belongs in one, and why the tax election matters

1. You Need Asset Protection

The #1 reason to form an LLC is to protect yourself from liability. LLC stands for Limited Liability Company—and the “limited” part is the whole point.

If something goes wrong in the business—whether it’s a tenant slip-and-fall, a customer lawsuit, or a product dispute—the lawsuit is forced to stop at the LLC. The suing plaintiff can only go after the LLC and its assets. That means your personal assets (home, savings, retirement accounts) are shielded.

Without an LLC, everything you own is at risk. And if you’re running a business or managing real estate, it’s not a matter of if liabilities arise—it’s when.

2. You’re Starting a Business and Want to Be Taken Seriously

If you’re working with customers, contractors, or vendors—or you want to hire employees—you need a real business structure. A DBA (“doing business as”) isn’t enough.

People take you more seriously when you have an LLC. It adds credibility and gives your business a professional structure for:

  • ✓Opening a business bank account
  • ✓Establishing a company name and brand
  • ✓Tracking business income and expenses- separate from your personal life
  • ✓Establishing business credit
  • ✓Applying for financing
  • ✓Contracting with potential customers
  • ✓Hiring Employees or Contractors

You want to build a legit business? Act like one. Set up an LLC. That being said, if you’re driving Door Dash on the weekends, you’re self-employed, but don’t necessarily need an LLC

3. You Have Business Partners or Investors

Anytime there’s another party involved—whether it’s a service-based partnership or a financial investor—you need clear documentation.

That’s where the operating agreement for your LLC comes in. It spells out:

  • ✓Who owns what
  • ✓What everyone’s responsibilities are
  • ✓How profits (and losses) are split
  • ✓What happens if someone leaves or needs to invest more capital

If you skip this step, you’re begging for a future dispute. This is your company’s prenup—don’t run a partnership without one.

4. You Own (or Plan to Own) Rental Properties

Rental properties come with liability risk—tenants, contractors, injuries, and more. That’s why real estate investors should use an LLC to hold their properties. If there’s ever a legal issue, the lawsuit hits the LLC, not you.

But be careful: you don’t want to put every property in an LLC.

  • ✓Primary residence? No—your name should be put into your revocable living trust for estate planning.
  • ✓Second home that’s also an Airbnb? Yes—consider an LLC for asset protection. If it generates income and has legal risk (e.g. tenants), it probably belongs in an LLC.

Ask Yourself These 4 Questions

Still unsure whether you really need an LLC? Ask yourself these four questions:

  1. 1Do I need asset protection?
    If there’s risk involved in what you’re doing—customers, clients, employees, tenants—you probably do.
  2. 2Am I starting a company?
    You’ll need an LLC to open a business account, to keep finances clean, to establish your company name and brand, and build legitimacy.
  3. 3Do I have partners or investors?
    Then you absolutely need an operating agreement (aka partnership agreement) to define roles and protect everyone involved.
  4. 4Do I own rental property or other risk-based assets?
    If it has liability exposure (e.g. tenants), it needs to be in an LLC.

If you answered yes to any of these, it’s time to consider forming an LLC.

Tax Considerations

When you set up an LLC you need to make tax elections. Doing this incorrectly will cost you greatly with the IRS. In general you should make the following S-Corp elections:

  • ✓Operating Businesses: If you sell goods or services at more than $50K per year – choose to be taxed as an S-Corp – See vid above for why
  • ✓Partnership: If you have a partner or more than 1 owner you’ll typically opt partnership
  • ✓Sole Proprietorship: If you have a rental or an operating business making less than $50K per year

Final Thoughts

LLCs aren’t one-size-fits-all—but they’re a smart move in the right situations.

At KKOS Lawyers, we’ve helped thousands of clients form, fix, and optimize their LLCs in all 50 states. Whether you’re starting something new or need to clean up an existing structure, we can help.

Contact KKOS Lawyers to Get Started

Key Takeaways

  • ✓LLCs protect your personal assets – If something goes wrong in the business, lawsuits stop at the LLC.
  • ✓A real company needs a real structure – An LLC adds legitimacy, helps you get financing, and separates business from personal finances.
  • ✓Partners and investors = operating agreement – Don’t run a business with others unless you have the terms spelled out.
  • ✓Rental properties should be in an LLC – It protects your other assets and keeps your real estate investments legally insulated.
  • ✓Ask the right questions – If you’re dealing with liability, growth, partnerships, or rental income, an LLC is likely the right call.
  • ✓LLCs can be taxed differently – Choose the right tax election for your situation to minimize your tax liability

Stock Market Falling…These 3 Strategies Could SAVE You!

What to Do When the Stock Market Drops

The market’s dropping, and your portfolio’s taking a hit. If you’re like most investors, your first instinct might be to panic—maybe even pull everything out and wait it out in cash.

But before you make a move, take a breath. Let’s talk strategy.

The S&P 500 is now down more than 15% from its recent high. That means a $100,000 account might be sitting at $85,000 today. But this isn’t the time to get emotional. It’s time to get smart.

Here are three critical things you should do when the market drops—because corrections are part of the cycle, and smart investors use them to build wealth, not lose it.

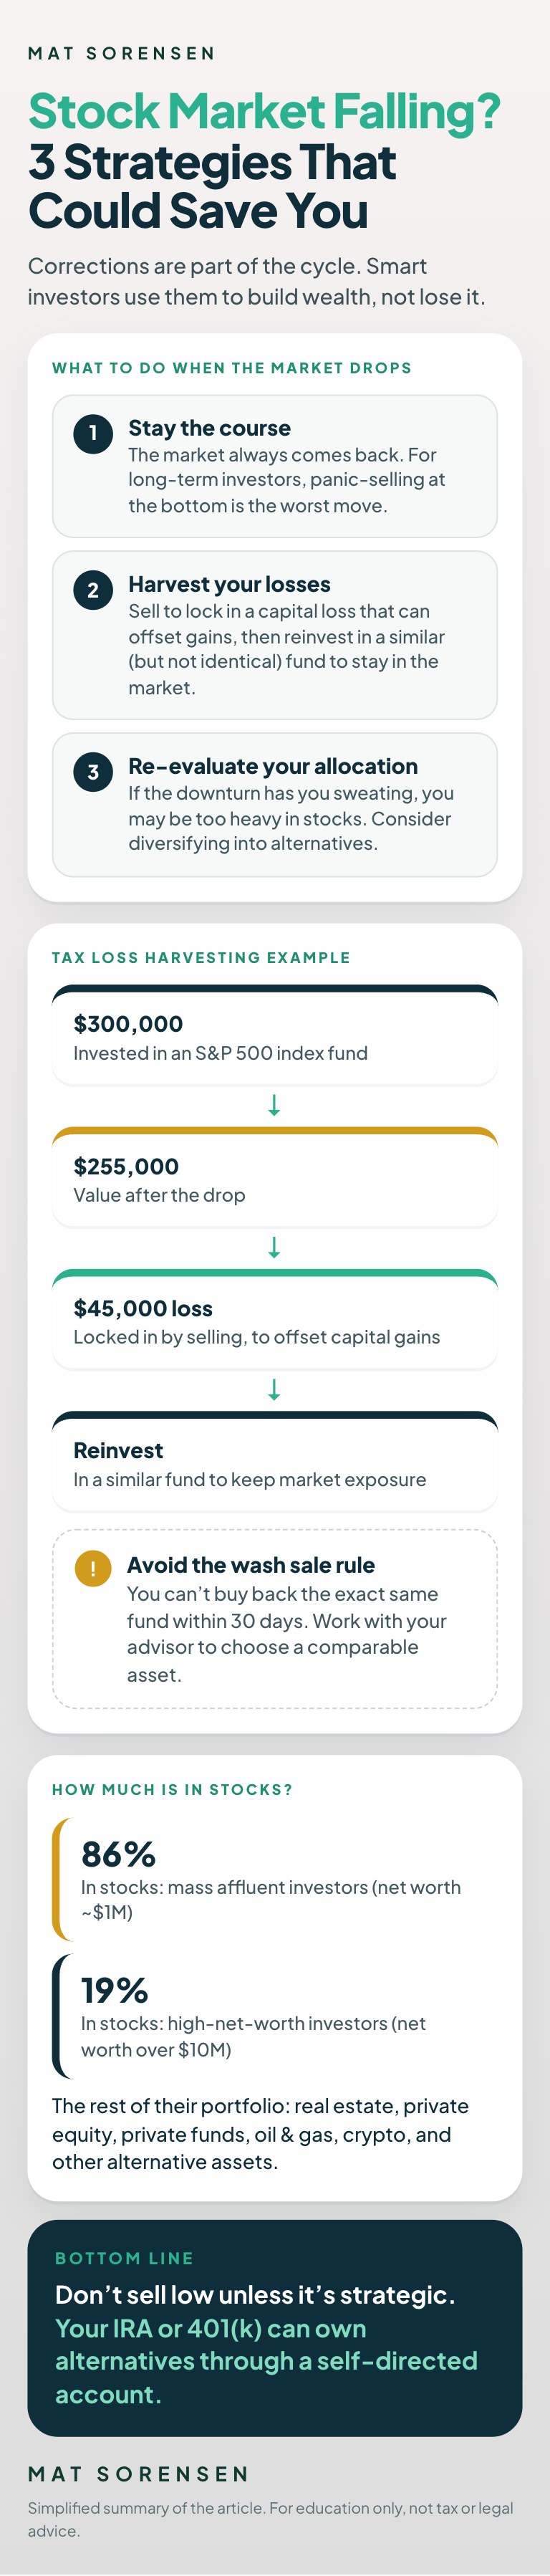
Infographic: three things to do when the stock market drops, a tax loss harvesting example, and how much wealthy investors hold in stocks

1. The Market Always Comes Back

Let’s get this straight: the market always recovers. That’s not wishful thinking—it’s data.

In the last 20 years, the S&P 500 has experienced 26 market corrections. That’s more than one a year. In 2022, the S&P dropped 27%… and came back within 282 days. In 2024? A 6% dip. Again, it bounced back.

Today we’re in a 15% correction. History tells us what happens next: recovery.

If you’re a long-term investor, the worst move you can make is panic-selling at the bottom. Wealth is built by staying the course through the downturns—because that’s how you’re still holding the bag when it starts climbing again.

That said, not every sale is a panic move. Which brings us to…

2. Use the Downturn to Your Advantage: Tax Loss Harvesting

Let’s add some nuance here: not all selling is bad. Smart investors know how to use a market decline to create opportunity—without abandoning their investment strategy.

Enter: tax loss harvesting.

EXAMPLE

Let’s say you bought $300,000 of an S&P 500 index fund. It’s now worth $255,000. If you sell today, you lock in a $45,000 capital loss.

That $45,000 can be used to offset capital gains from other investments—reducing your tax bill now or in future years.

But here’s the key: you’re not leaving the market. You take that $255,000 and reinvest it in a similar (but not identical) fund—maintaining your market exposure, while locking in the tax benefit.

$300,000

Invested in an S&P 500 index fund

$255,000

Value after the drop

$45,000

Capital loss locked in

This is not panic selling. It’s strategic repositioning.

WATCH OUT

Just make sure you avoid the wash sale rule—you can’t buy back the exact same fund within 30 days. Work with your advisor to choose a comparable asset.

3. Re-Evaluate Your Allocation: Are You Too Heavy in Stocks?

If this downturn has you sweating bullets, it might be a sign that your portfolio is overallocated to the stock market.

And here’s a stat that should make you pause:

  • ✓Mass affluent investors (net worth ~$1M) have 86% of their portfolio in stocks
  • ✓High-net-worth investors (net worth over $10M) have just 19% in stocks

What’s in the rest of their portfolio?

  • ✓Real estate
  • ✓Private equity
  • ✓Private funds
  • ✓Oil & gas
  • ✓Crypto
  • ✓Other alternative assets

The ultra-wealthy diversify intentionally—and for good reason. These assets often deliver higher returns with lower volatility than the public markets.

Even JP Morgan agrees: their recommended “modern portfolio” now includes:

  • ✓40% stocks
  • ✓30% bonds
  • ✓30% alternatives

At Directed IRA, we’ve helped thousands of investors shift their retirement dollars into alternatives—real estate, private funds, even crypto. These are all assets your IRA or 401(k) can legally own through a self-directed account.

Want to Diversify with Your IRA?

If you’ve never heard of using your IRA to invest in alternatives, you’re not alone—but you’re missing a massive opportunity.

📞 Book a call with our team at Directed IRA
We’ll show you how to use your IRA or solo 401(k) to invest beyond the stock market—with full IRS compliance.

Key Takeaways

  • ✓The market always comes back – 26 corrections in 20 years, and every one recovered.
  • ✓Tax loss harvesting can be smart – Strategic selling lets you lock in losses for tax benefits—without exiting the market.
  • ✓Diversify like the wealthy – Ultra-wealthy investors allocate less to stocks and more to alternatives like real estate, private equity, venture capital, private funds, and even crypto.
  • ✓Don’t sell low—unless it’s strategic – Stay invested to benefit from the rebound. If you’re selling, have a plan (like tax-loss harvesting or reallocating to alternatives).

FREE SELF-DIRECTED IRA GUIDE

Learn how to invest your IRA in real estate, private companies, notes, precious metals, and more.

Get the Free Self-Directed IRA Guide

Prefer to talk it through? Book a call with a Directed IRA specialist

How the “Buy, Borrow, Die” Strategy Builds Wealth and Avoids Taxes

What if you could access millions in wealth without selling your assets—or paying a dime in taxes? That’s exactly what the wealthiest Americans have been doing for decades using a strategy called Buy, Borrow, Die.

While it may sound like a clickbait slogan, this approach is a time-tested way to build and preserve wealth. And despite what you may think, it’s not just for billionaires. Everyday investors use the same strategy with brokerage accounts, real estate, and small businesses.

In this article, we’ll break down how Buy, Borrow, Die works, why it’s so effective, and how you can start using it to grow your wealth while minimizing taxes—legally.

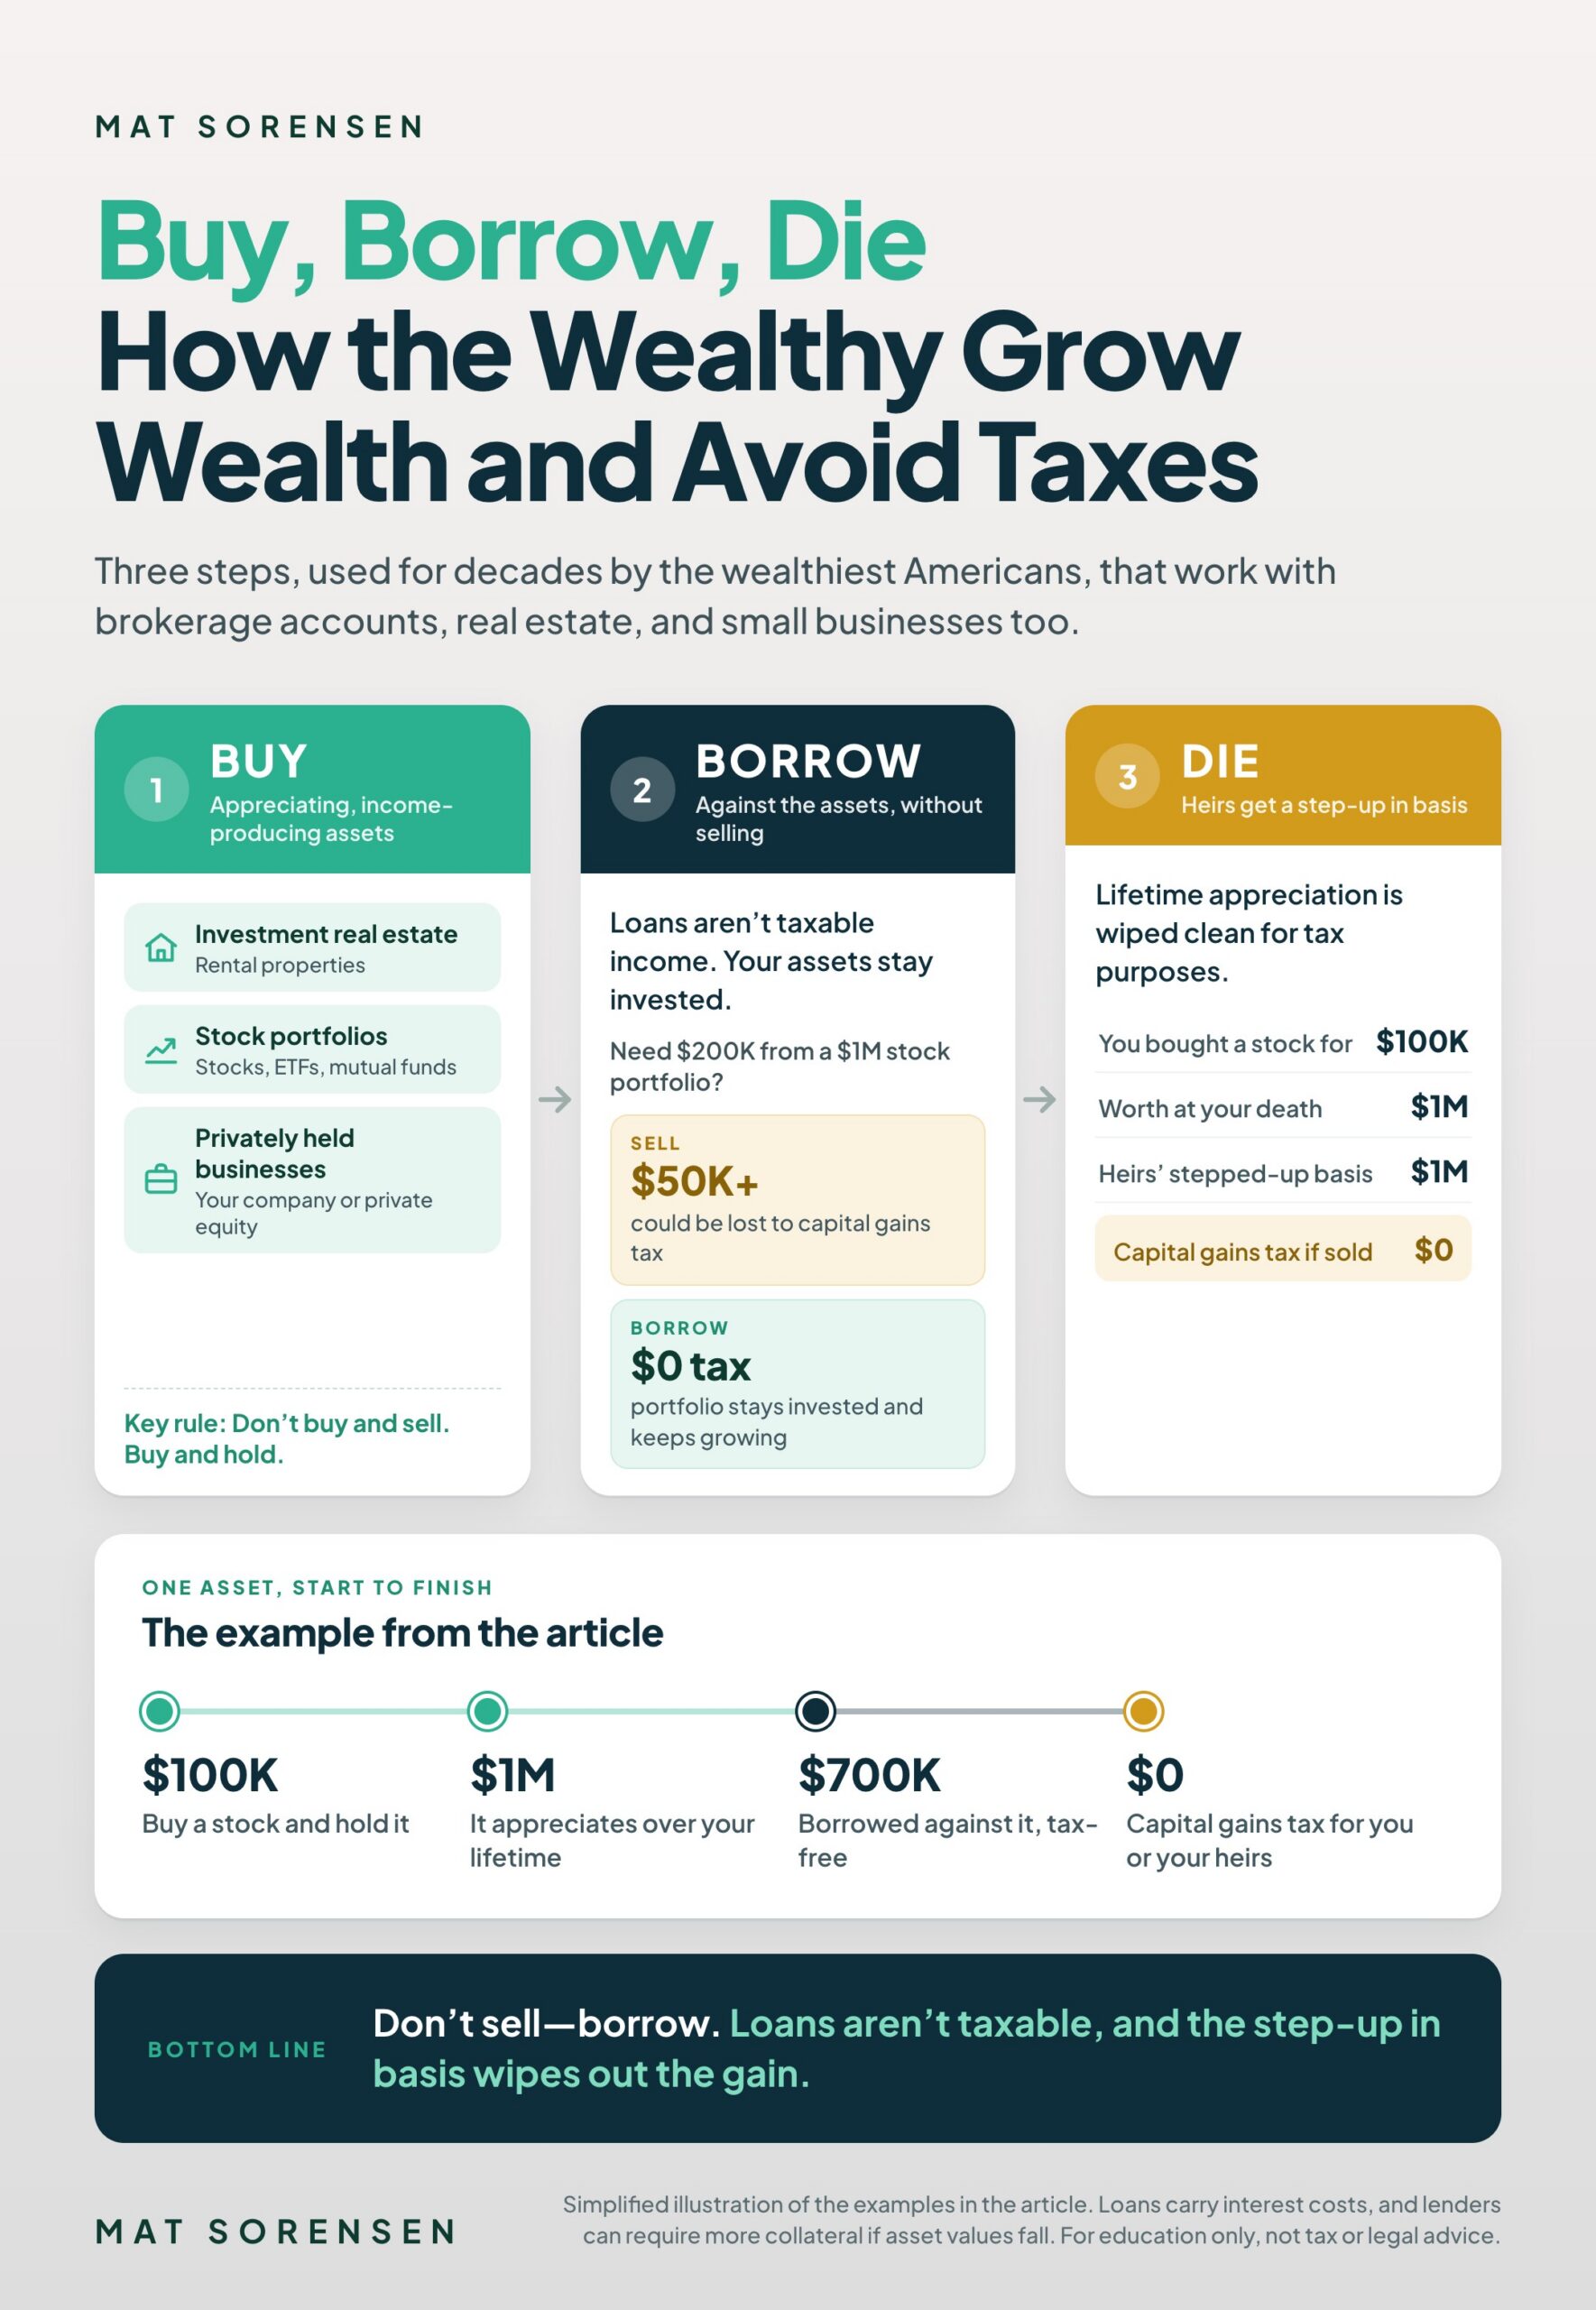
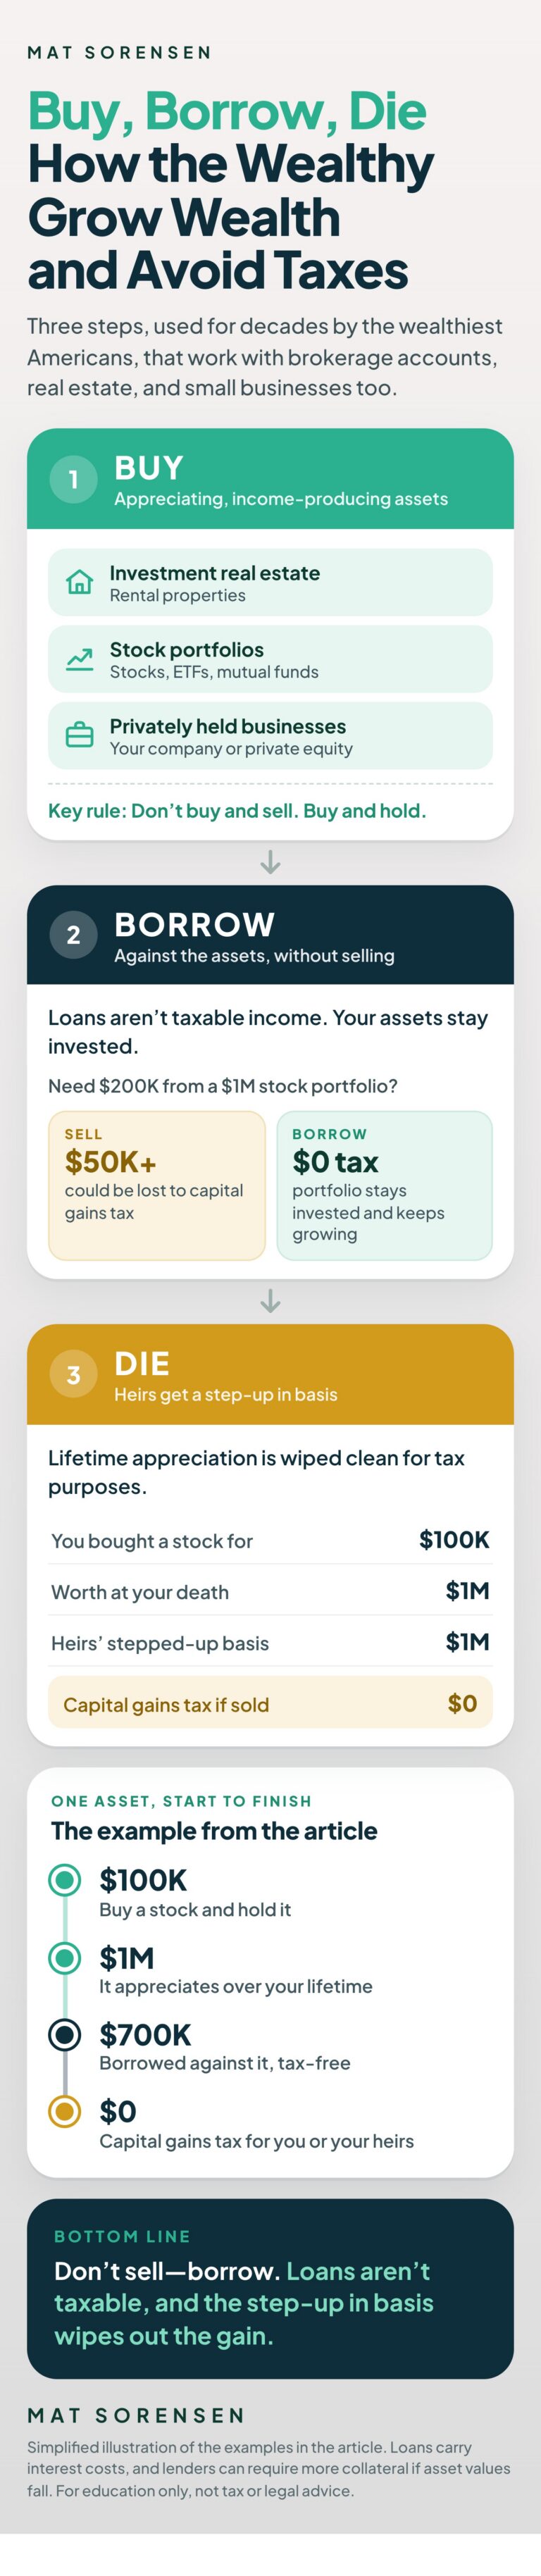
Infographic: the Buy, Borrow, Die strategy in three steps. Buy appreciating assets, borrow against them instead of selling, and heirs receive a step-up in basis

Step 1: Buy Appreciating, Income-Producing Assets

The first step is buying assets you understand—those that generate income and have the potential to appreciate over time.

Think:

Investment real estate (rental properties)

Stock Portfolios (stocks, ETFs, mutual funds)

Privately held businesses (your own company or private equity)

These assets grow over time and, in many cases, generate cash flow along the way via rental income or dividends. That means they not only increase your net worth, they also create ongoing income—which sets the stage for the “borrow” part of the strategy.

Key Rule: Don’t buy and sell. Buy and hold. That’s where real wealth is built.

Step 2: Borrow Against the Assets (Without Selling)

This is where most of the tax planning magic happens.

Rather than selling your appreciated assets—and triggering capital gains tax—you borrow against them. Equity in assets accessed via a loan isn’t taxable income. That means you can unlock your wealth without selling assets or owing the IRS.

Two Common Borrowing Scenarios for Building Wealth

1

Brokerage Account

Let’s say you’ve built a $1M stock portfolio. You need $200K for a large expense—could be taxes, a business opportunity, or even a major life event.

Option A: Sell investments

You trigger capital gains tax. Depending on your bracket and state, you could lose $50K or more just in taxes.

Option B: Borrow against your portfolio

You pay no tax. Your portfolio stays fully invested and continues to grow.

This strategy is called securities-based lending. With a securities-backed line of credit, firms like JP Morgan, Wells Fargo, or your private bank will lend you 70–90% of your portfolio’s value, using your stocks, bonds, or mutual funds as collateral.

  • ✓Stay invested
  • ✓Access low-interest liquidity
  • ✓Avoid triggering capital gains tax

Bottom line: You get the cash you need—without dismantling your long-term investment plan.

Borrowing vs. Liquidating a $10M Portfolio
Client ANot using a line of credit Client BUsing a line of credit
Balanced portfolio $10,000,000 $10,000,000
Liquidation amount $3,000,000 $0
Remaining investment $7,000,000 $10,000,000
Total portfolio return $483,000 $690,000
Total loan cost $0 ($58,500)
Net portfolio return $483,000 $631,500
Value added by using a line of credit — $148,500
Source: J.P. Morgan Private Bank illustration. Rather than liquidating investments, Client B used a line of credit to cover an unexpected liquidity need.

📉 See chart above: Client B uses a line of credit instead of liquidating assets. They keep their portfolio fully invested, pay minimal loan interest, and walk away with $148,500 more in net returns.

2

Investment Real Estate (Cash-Out Refi)

Own a $1M rental property with equity? Use a cash-out refinance to pull $700K without selling. You still own the asset, still collect rent, and you pay no tax on the money you borrowed.

Step 3: Die (and Pass It on Tax-Free)

Let’s be honest—this is the least fun part of the strategy. But it’s one of the most powerful.

When you die, your heirs receive a step-up in basis. That means all of the appreciation during your lifetime—stocks, real estate, businesses—is wiped clean from a tax standpoint.

Let’s say:

You bought a stock for $100K

It’s worth $1M when you pass away

You borrowed $700K against it during your lifetime

Your heirs inherit the asset at a $1M stepped up basis – which means they can sell it the next day for $1M and pay zero capital gains tax. The $700K loan is paid off, and the rest goes to them tax-free. In the end neither you nor your heirs paid capital gains tax.

Why This Strategy Works (Even If You’re Not a Billionaire)

You don’t need a $10M portfolio to use this. In fact, many investors use this strategy with:

$250K brokerage accounts

A single rental property

Business equity

Here’s why it works:

  • ✓Loans are not taxable
  • ✓Assets keep appreciating
  • ✓You avoid selling (and shrinking) your net worth
  • ✓Your heirs benefit from a tax-free step-up in basis

Congress has taken notice and bills have been introduced to limit or eliminate the step-up in basis. There have even been bills intended to tax you when you access equity in an asset via a loan. Those bills have all failed. For now, Buy, Borrow, Die remains one of the most powerful—and legal—wealth-building and tax-saving strategies available.

Key Takeaways

  • ✓Buy assets that appreciate and produce income
  • ✓Don’t sell—borrow
  • ✓Loans are not taxable income
  • ✓Borrowing allows you to enjoy your wealth without shrinking your net worth
  • ✓Your heirs can inherit assets tax-free with a step-up in basis
  • ✓This strategy works for real estate, stock portfolios, and even businesses

Ready to Build Your Wealth—Step by Step?

The Buy, Borrow, Die strategy is just one piece of a bigger picture. If you want to know where to start and what to do next, download Mat’s guide on the Ideal Order of Investing.

Whether you’re just getting started or ready to expand into real estate, Roth IRAs, or alternative assets—this is the roadmap.

Download the Free Guide: The Ideal Order of Investing

Take control of your financial future—one smart move at a time.

What to Do with a 401(k) When You Leave Your Employer

For many Americans, their 401(k) is their largest investment account—and the main source of income they’re counting on for retirement. But when you leave your job, what happens to that money? What’s the best move to keep your savings protected and growing?

The wrong decision could cost you thousands in taxes, penalties, or missed investment opportunities. In this guide, we’ll break down everything you need to know about your 401(k) after leaving an employer—including vesting rules, rollover options, and tax implications—so you can make the best choice for your financial future.

Let’s go over your options, the pros and cons of each, and how to roll over your 401(k) the right way—without triggering unnecessary taxes or penalties.

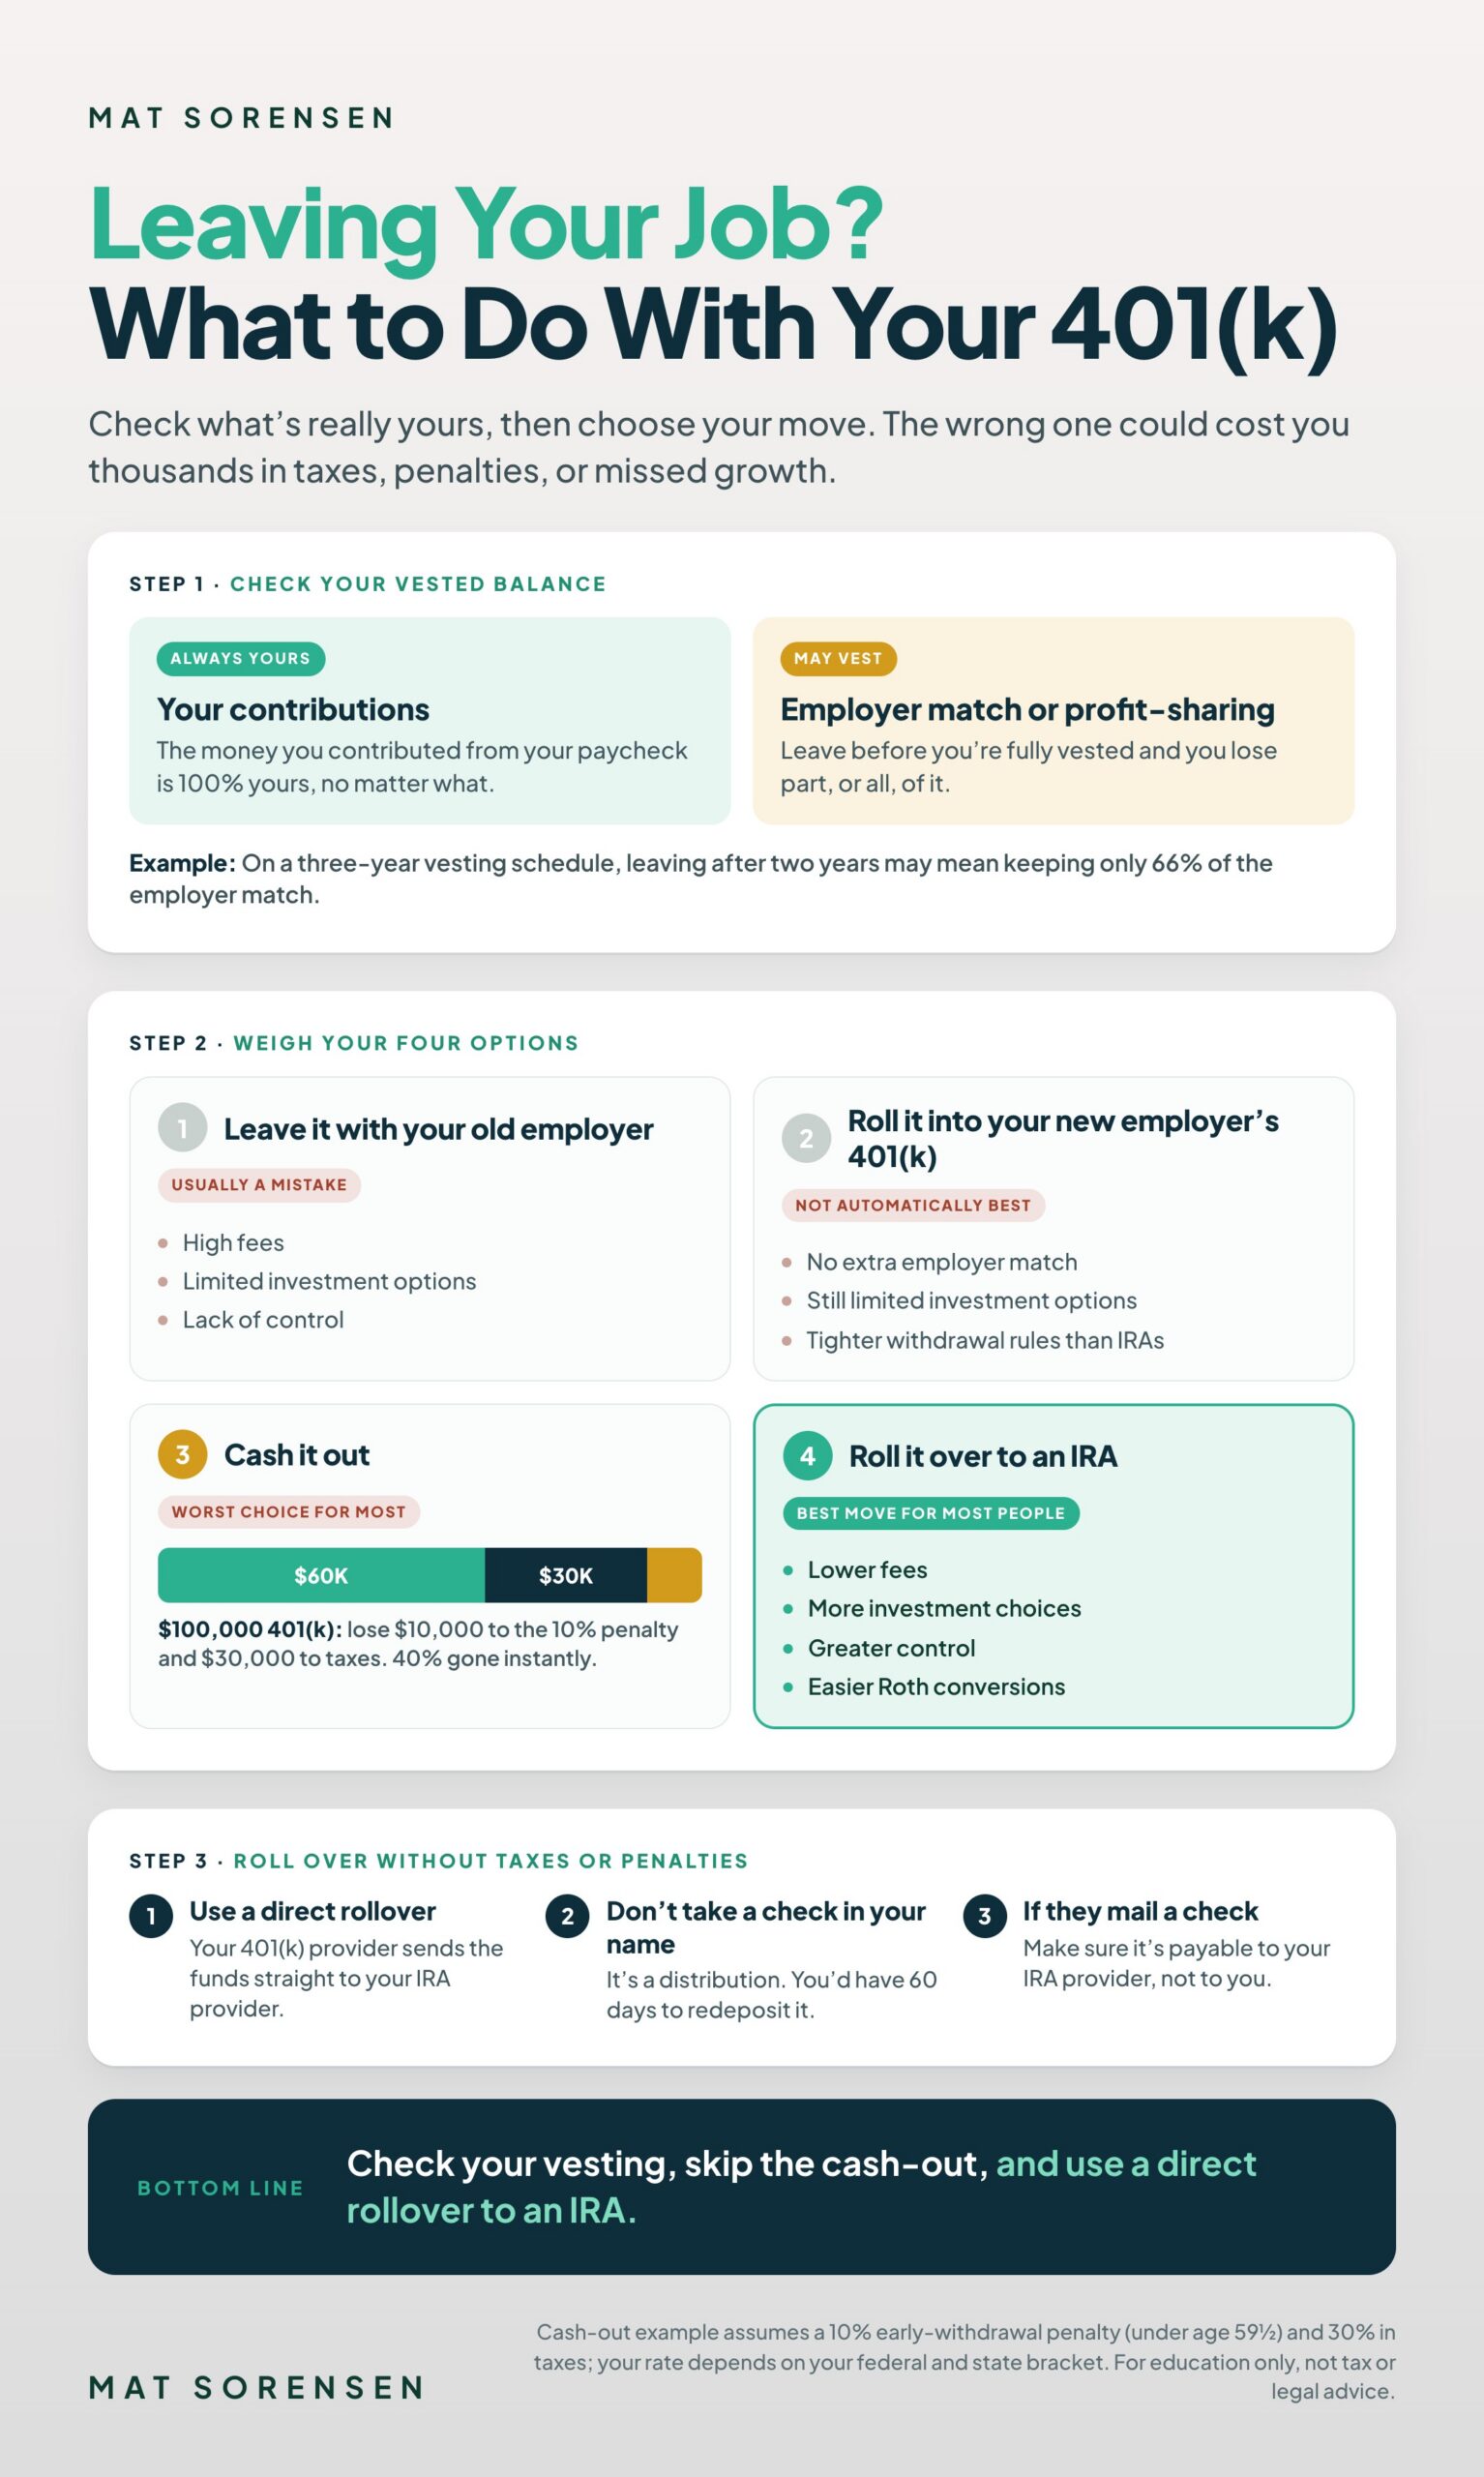
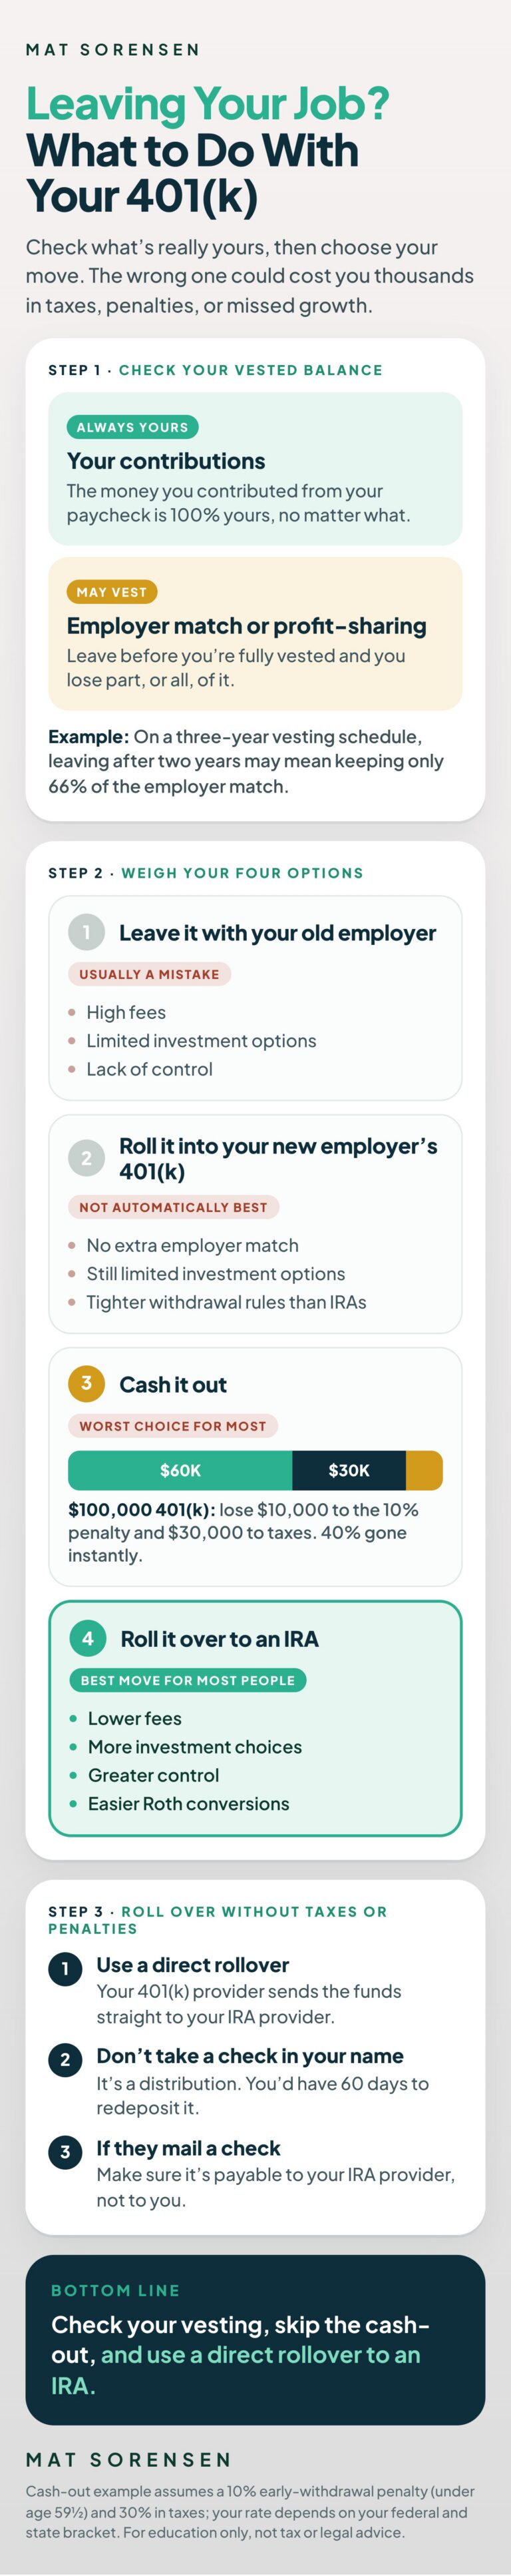
Infographic: what to do with your 401(k) when you leave your job. Check your vested balance, compare four options, and use a direct rollover to an IRA

Step 1: Check Your Vested Balance

Before making a move, the first thing you need to do is determine how much of your 401(k) actually belongs to you.

Understanding Vesting

Your 401(k) balance is split into two parts:

1. Your Contributions

The money you contributed from your paycheck. This is 100% yours, no matter what.

2. Employer Contributions (Match or Profit-Sharing)

This money may be subject to a vesting schedule. If you leave before you’re fully vested, you lose part (or all) of the employer contributions.

How to Check Your Vested Balance:

  • 1Get your latest 401(k) statement – It will show vested vs. unvested balance.
  • 2Review your company’s vesting schedule – This is outlined in your Summary Plan Description (SPD).

Know what you’re walking away with – Unvested employer contributions do NOT transfer when you leave.

Example: If your employer has a three-year vesting schedule and you leave after two years, you may only keep 66% of the employer match. If you leave too soon, you could be walking away from thousands of dollars in unvested money.

Once you know your true balance, you’re ready to decide where to move your funds.

Step 2: Weigh Your 401(k) Rollover Options

When you leave your employer, you have four main choices for handling your 401(k). Let’s go through each one.

Option 1: Leave Your 401(k) with Your Old Employer

Some people leave their 401(k) behind at their old job because it seems like the easiest choice. But in most cases, this is a mistake.

Cons of Keeping Your 401(k) at Your Old Job:

  • ✕High fees – The average small business 401(k) charges 1.5% in fees, which could cost you thousands over time.
  • ✕Limited investment options – Most plans restrict you to mutual funds and target-date funds—often with subpar performance.
  • ✕Lack of control – You can’t make quick investment decisions, and accessing funds requires employer approval.

Bottom Line: If you no longer work there, why should your money stay there?

Option 2: Roll It Into Your New Employer’s 401(k)

If your new job offers a 401(k) plan, you may have the option to roll over your old 401(k) into the new one.

Cons of Moving to a New 401(k):

  • ✕No financial benefit – Rolling over doesn’t give you extra employer matching.
  • ✕Still limited investment options – You’re typically stuck with mutual funds or target-date funds.
  • ✕More restrictive withdrawal rules – 401(k) plans often have tighter restrictions than IRAs.

Key Insight: Just because your new job has a 401(k) does NOT mean you should roll your old one into it.

Option 3: Cash Out Your 401(k)

You can withdraw your 401(k) as a lump sum when you leave—but this is one of the worst financial mistakes you can make.

Why Cashing Out Is a Disaster:

  • ✕10% Early Withdrawal Penalty – If you’re under 59½, you automatically lose 10% to the IRS.
  • ✕Massive Taxes – Your withdrawal is treated as ordinary income, which could push you into a higher tax bracket. For traditional 401(k)s the entire distribution is taxable. For Roth 401(k) balances, only the earnings are taxable if distributed early.

Example: If you cash out a $100,000 401(k):

$60,000
$30,000
10% Penalty -$10,000
30% in Taxes -$30,000 (depends on your state/federal tax bracket)
Final Amount Received $60,000

That’s 40% gone instantly.

When Cashing Out Might Make Sense:

  • ✓You’re 59½ or older and ready for retirement.
  • ✓You have no other financial options in an emergency.

For most people, this is the worst choice.

Option 4: Roll Over to an IRA

Rolling your 401(k) into an IRA gives you more control, lower fees, and better investment choices.

Why an IRA Is the Best Move for Most People:

  • ✓Lower fees – No employer plan fees eating into your returns.
  • ✓More investment choices – Could be a brokerage IRA for stocks/ETFs (like Schwab or Fidelity), or a Self-Directed IRA for real estate, private companies, and funds (like at Directed IRA).
  • ✓Greater control – No employer restrictions.
  • ✓Easier Roth conversions – Convert to a Roth IRA for future tax-free growth.

How to Rollover to an IRA Without Taxes or Penalties:

  • 1Use a direct rollover – This is critical to avoiding taxes. Your 401(k) provider should send the funds directly to your new IRA provider.
  • 2Do NOT take a check in your name – If the check is made out to you, it’s a distribution. You have 60 days to redeposit it into an IRA—or the IRS treats it as taxable income.
  • 3Some providers still mail checks – If they do, make sure it’s made out to your IRA provider, not to you personally.

Example: A 401(k) account owner requested a rollover, but the provider sent the check to the account owner. He didn’t redeposit it into an IRA and is now subject to taxes and penalties—and those funds can’t go back into a tax-advantaged account like an IRA.

Best Practice: Always request a direct rollover to the IRA provider to avoid a distribution, penalties, and taxes.

Special Situations to Check Before You Move Your 401(k)

A few situations change the math. Check these before you sign any rollover paperwork.

Leaving at 55 or Older: The Rule of 55

If you leave your job in or after the year you turn 55, withdrawals from that employer’s 401(k) aren’t hit with the 10% early withdrawal penalty. You still owe regular income tax on them. For qualified public safety employees in a government plan, and for private-sector firefighters, the age drops to 50 (or 25 years of service under the plan, if that comes first).

WATCH OUT

This exception only covers money that stays in that employer’s plan. It doesn’t apply to IRAs. If you roll everything into an IRA and later need cash before 59½, the 10% penalty can apply again. If you might need some of this money before 59½, factor that in before you roll it all over.

Leaving With an Unpaid 401(k) Loan

If you still owe on a 401(k) loan when you leave, the unpaid balance is often taken out of your account and treated as a distribution, called a loan offset. That makes it taxable, and the 10% penalty can apply if you’re under 59½.

You can avoid that by depositing the same amount into an IRA by your tax return due date, including extensions, for the year of the offset. For the full rules, see What Happens to a 401(k) Loan When You Leave Your Job?

Rolling Over a Roth 401(k)

Match each type of money to the right account. Pre-tax 401(k) money goes to a Traditional IRA, and Roth 401(k) money goes to a Roth IRA (or your new employer’s Roth 401(k)). If your plan holds both, you may need two rollover requests, one for each.

One timing catch: the years your money spent in the Roth 401(k) don’t count toward the Roth IRA’s five-year clock for tax-free earnings. If you contributed to a Roth IRA in an earlier year, your clock started with that first contribution.

If the Plan Pays You Instead: The 20% Withholding Trap

When your old plan pays the money to you rather than directly to your IRA, it must withhold 20% of the taxable amount for federal income tax, even if you plan to roll it over. To roll over the full amount, you have to make up that 20% from other money within 60 days.

EXAMPLE

You have $100,000 in your 401(k), and the plan sends you a check. It withholds $20,000 for taxes, so you receive $80,000.

To roll over the full $100,000, you deposit the $80,000 plus $20,000 of your own savings into an IRA within 60 days. The $20,000 that was withheld is credited toward your taxes when you file your return.

If you deposit only the $80,000, the missing $20,000 is treated as a taxable distribution. If you’re under 59½, it can also face the 10% penalty.

$100,000

Balance in your 401(k)

$20,000

Withheld for taxes

$80,000

Check you receive

A direct rollover avoids all of this, because nothing is withheld.

Small Balances Can Be Moved Without You

If your balance is small, your old plan may be allowed to cash it out or move it into an IRA in your name without waiting for your instructions. After you leave, watch for plan notices so you get to choose where your money goes.

How a Rollover to a Self-Directed IRA Works

Rolling into a self-directed IRA works the same way as rolling into any other IRA. A self-directed IRA is a Traditional or Roth IRA held with a custodian that allows alternative assets like real estate, private companies and funds. Here’s how it works with Directed IRA:

  1. 1Sort your money. Check your 401(k) statement for pre-tax and Roth balances.
  2. 2Open the matching IRA. Open a Traditional IRA for pre-tax money and a Roth IRA for Roth money.
  3. 3Request a direct rollover. Use your 401(k) provider’s rollover form (sometimes one per type of money) and have the funds sent to Directed Trust Company for your IRA, not to you.
  4. 4Give Directed IRA a heads-up. Let the team know a rollover is on the way so it lands in the right account.
  5. 5Invest. Once the funds arrive, you choose the investments and direct the IRA to make them.

Frequently Asked Questions

Do I have to move my 401(k) when I leave my job?

No. You can usually leave it in your old plan. The exception is small balances, which the plan may cash out or move to an IRA for you.

Is rolling a 401(k) into an IRA taxable?

No, not if you use a direct rollover and keep the money in the same tax bucket: pre-tax into a Traditional IRA, Roth into a Roth IRA. Rolling pre-tax money into a Roth IRA is a Roth conversion, so it’s taxable in the year you do it.

Does a 401(k) rollover count toward the once-a-year IRA rollover limit?

No. The one-rollover-per-year limit applies to IRA-to-IRA rollovers, not rollovers from an employer plan to an IRA.

Can I roll my 401(k) into a self-directed IRA?

Yes. A self-directed IRA isn’t a separate type of IRA under the tax code. It’s a Traditional or Roth IRA held with a custodian that allows alternative investments, so an old 401(k) can roll into it like any other IRA.

What if I already got a check made out to me?

You have 60 days from the day you received it to deposit it into an IRA. To roll over the full amount, add back the 20% that was withheld. The IRS can waive the 60-day deadline in some situations outside your control.

Key Takeaways

  • ✓Check your vested balance first. Make sure you know how much of your 401(k) you actually own.
  • ✓Leaving your 401(k) at your old employer is usually a bad idea – High fees and limited investment options make it less appealing.
  • ✓Rolling your 401(k) into your new employer’s plan may not be the best move – You’ll still be stuck with high fees and limited investment options.
  • ✓Cashing out your 401(k) is a terrible idea for most people under 59½ – Taxes and penalties could take 40% or more of your money.
  • ✓Rolling over to an IRA is the best option for most people – It gives you lower fees, more investment options, and complete control over your retirement funds.
  • ✓Use a direct rollover to avoid taxes and penalties – Never take a check in your name unless it’s your only option, and if you do, you must redeposit the same amount into an IRA within 60 days.

FREE ROLLOVER GUIDE

Learn how to move an old 401(k) or IRA into a self-directed IRA, tax-free.

Get the Free Transfers & Rollovers Guide

Prefer to talk it through? Book a call with a Directed IRA specialist